
Gaja Alternative Asset Management IPO 2026 – Can a Private Equity Manager Become a Scalable Listed Investment Platform?
Most IPO companies raise capital to build factories, open stores or buy equipment.
Gaja Alternative Asset Management Limited is very different.
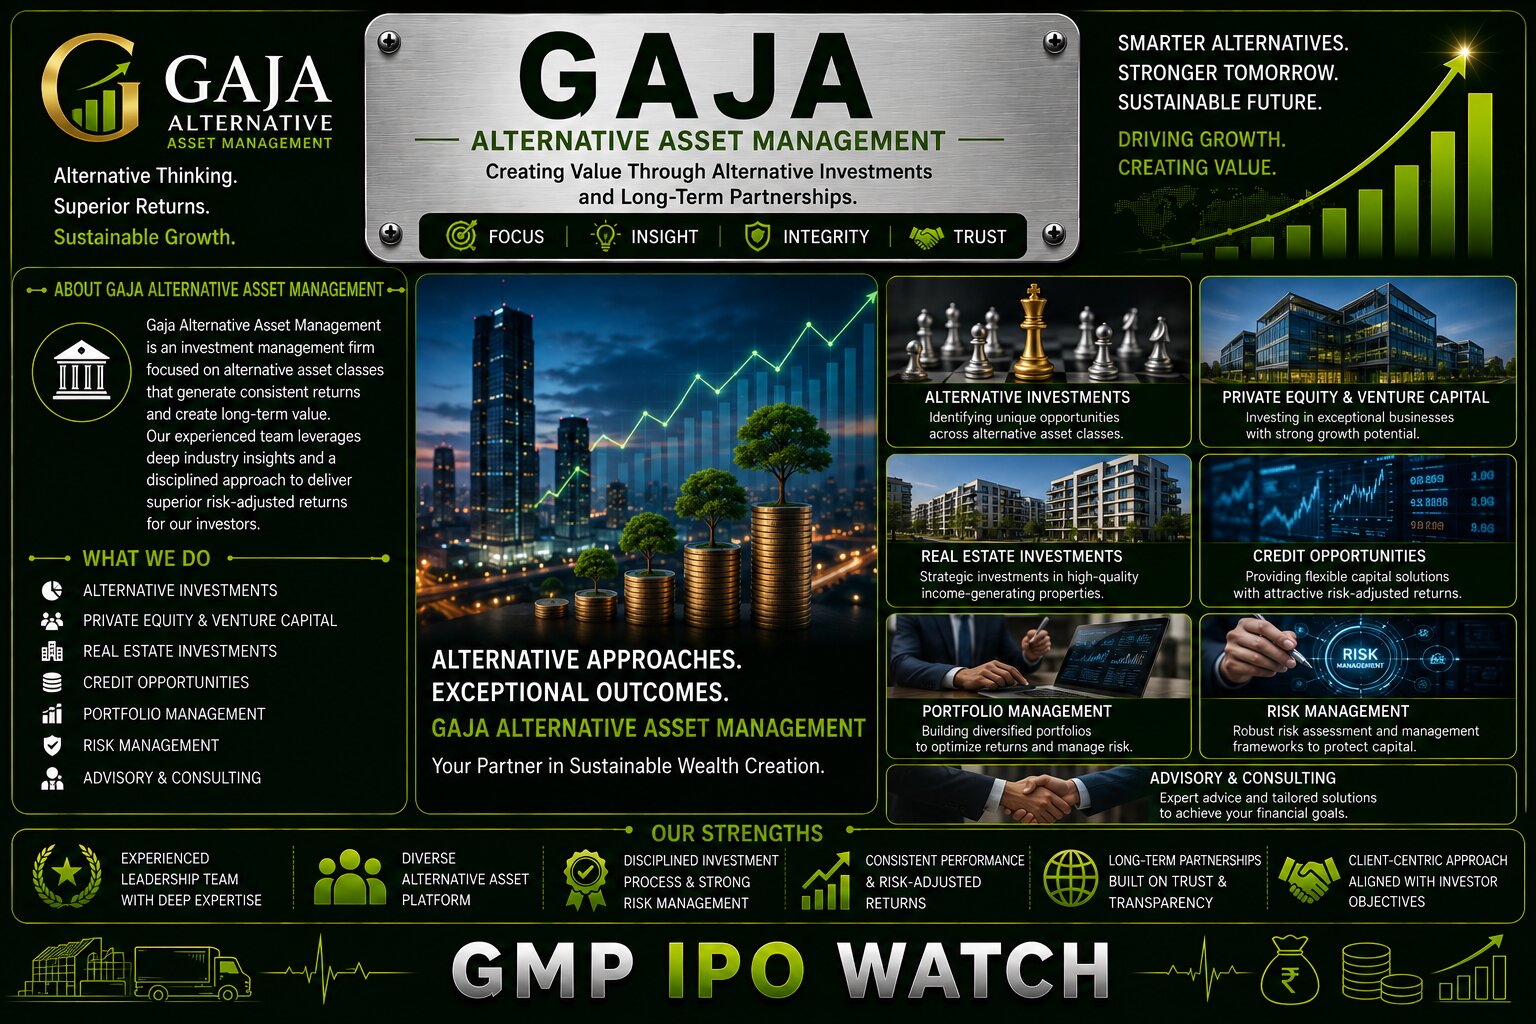
The company, better known through the Gaja Capital brand, manages and advises India-focused alternative investment funds. Its business is built around raising money from investors, investing that capital into private businesses and ultimately generating returns through successful exits.
Gaja's investors are spread across more than 20 countries, including India, the US, Europe and the Middle East. The company focuses mainly on mid-market transactions, with typical deal sizes in the range of ₹50 crore to ₹250 crore.
The IPO opened today, August 19, 2026.
But the real investment question is not simply whether the ₹550 crore IPO gets oversubscribed.
It is:
Can Gaja continue delivering attractive investment returns, raise progressively larger funds and convert its track record into sustainable management fees, carried interest and sponsor-investment income?
That is the core story.
Gaja Alternative Asset Management IPO Details
| Particular | Details |
|---|---|
| Company | Gaja Alternative Asset Management Ltd. |
| Brand | Gaja Capital |
| IPO Type | Book Built Mainboard IPO |
| Listing | BSE & NSE |
| Issue Size | ₹550 Crore |
| Fresh Issue | ₹450 Crore |
| Offer for Sale | ₹100 Crore |
| Price Band | ₹152 – ₹160 |
| Face Value | ₹10 Per Share |
| Lot Size | 93 Shares |
| Retail Minimum | 93 Shares |
| Retail Investment | ₹14,880 at ₹160 |
| IPO Open Date | August 19, 2026 |
| IPO Close Date | August 21, 2026 |
| Allotment Date | August 24, 2026 |
| Refund Date | August 25, 2026 |
| Demat Credit | August 25, 2026 |
| Listing Date | August 26, 2026 |
| Lead Managers | JM Financial, IIFL Capital Services |
| Registrar | MUFG Intime India |
The ₹550 crore IPO comprises approximately ₹450 crore of fresh shares and ₹100 crore through Offer for Sale. At the upper price band, the minimum retail application is 93 shares requiring ₹14,880.
Gaja Alternative Asset Management IPO Day 1 Subscription
The IPO opened for subscription today and saw a moderate start during the first few hours.
As of 11:50 AM on August 19, the issue was subscribed approximately:
| Category | Subscription |
|---|---|
| QIB | 0.00× |
| NII | 0.35× |
| Retail | 0.47× |
| Overall | 0.31× |
The company had approximately 2.53 crore shares available for public subscription, while the retail portion consisted of about 1.26 crore shares.
These are intraday Day 1 numbers and can change materially before the IPO closes on August 21.
Institutional bids in particular frequently arrive closer to the final day.
Retail Investors Are Leading Early Demand
The retail category had reached approximately 47% subscription by the late-morning update, compared with about 35% for NIIs. QIB bidding had not started at that point.
This means retail investors are currently providing the strongest visible early demand.
However, Gaja is an unusual IPO because the underlying business itself revolves around institutional and alternative investment capital.
Final QIB demand will therefore be particularly interesting.
Gaja Alternative Asset Management IPO GMP Today
The latest reported grey-market premium is around:
₹30 per share.
Against the ₹160 upper price:
₹160 + ₹30 = ₹190
This indicates an unofficial premium of approximately:
18.75%, or roughly 19%.
| Particular | Current Position |
|---|---|
| Upper IPO Price | ₹160 |
| Latest GMP | ₹30 |
| Indicative Price | ₹190 |
| Indicative Premium | ~19% |
This is a clear improvement from the lower GMP levels seen before the IPO opened.
However, GMP is unofficial and unregulated and should not be interpreted as a guaranteed listing return.
Gaja Raised ₹165 Crore From Anchor Investors
Ahead of the public opening, Gaja Capital raised approximately ₹165 crore through its anchor allocation.
Anchor participation provides an early institutional-demand signal.
But investors should still focus primarily on:
fund performance + future fundraising + earnings quality + valuation.
For an alternative asset manager, those factors matter much more than one day's subscription.
What Does Gaja Alternative Asset Management Actually Do?
Gaja Capital is essentially a private equity and alternative asset management company.
Its business involves:
- Raising capital from institutional and wealthy investors.
- Creating investment funds.
- Identifying private companies.
- Investing those funds into selected businesses.
- Working with portfolio companies.
- Selling those investments after several years.
- Generating returns for investors.
Gaja manages India-focused Category I and Category II AIFs and advises offshore funds investing in India.
This model is very different from a bank.
Gaja does not primarily lend its own balance sheet.
It manages third-party capital and invests some of its own sponsor capital alongside investors.
Gaja Has Three Major Income Streams
The company's economics can be understood through three broad income sources:
Management fees
Carried interest
Income from sponsor commitments.
Each has a different risk profile.
Management fees are generally more predictable.
Carried interest can be much more profitable but depends on investment performance.
Sponsor income depends on how Gaja's own money invested in its funds performs.
Management Fees Create the Recurring Base
Suppose Gaja manages a large investment fund.
Investors commit capital, and Gaja charges agreed management fees for running that fund.
These fees help finance:
- Investment professionals
- Research
- Administration
- Compliance
- Operations
The bigger the fee-paying asset base becomes, the larger the potential recurring revenue pool.
This is why AUM and fee-paying AUM growth should become important post-listing metrics.
Carried Interest Is the High-Upside Revenue Stream
Carried interest refers to Gaja's share of investment profits when funds generate returns above the contractual structure.
This can create very attractive economics.
Imagine a fund invests ₹1,000 crore and eventually produces substantial gains.
Part of the profits may belong to the investment manager as carried interest.
This can create significant earnings without proportionately higher operating costs.
But there is a major downside:
carried interest is not guaranteed.
Nearly 48% of FY2026 Income Came From Carried Interest
This is one of the most important details in the IPO.
Economic Times reports that carried interest accounted for nearly 48% of Gaja's total income in FY2026.
That helps explain the company's exceptionally high profitability.
But it also means current earnings contain a meaningful performance-linked component.
Investors should not automatically assume every future year will produce exactly the same carried-interest contribution.
Why Carried Interest Can Make Earnings Volatile
Consider two years.
Year A
Several portfolio companies are successfully exited.
Gaja may recognise substantial carried interest.
Year B
No major exits happen.
Management-fee revenue may remain stable, but carried interest can be much lower.
The business can still be healthy.
But reported PAT may fluctuate.
Therefore, investors should evaluate Gaja across complete fund cycles, not just quarterly earnings.
Sponsor Commitment Gives Gaja Skin in the Game
As of March 31, 2026, Gaja had committed approximately ₹274 crore of its own capital to Gaja Capital Funds.
That represented around 6.4% of the total size of those funds.
This alignment can be attractive.
Gaja is not simply earning fees from outside investors.
Its own money is invested alongside them.
If portfolio investments perform well, both:
fund investors + Gaja
benefit.
But Sponsor Capital Also Increases Investment Risk
Alignment is positive, but it also creates exposure.
If portfolio investments perform poorly, Gaja can suffer through:
- Lower carried interest
- Lower sponsor-investment returns
- Weaker reputation
- Harder future fundraising
This means Gaja's earnings are more directly linked to investment performance than those of a conventional fee-only mutual fund manager.
₹372 Crore of Fresh Proceeds Is Central to the IPO
Gaja plans to use approximately ₹372 crore of the ₹450 crore fresh issue toward sponsor commitments to existing and proposed funds and repayment of a bridge loan.
The planned use includes:
- Balance sponsor commitments to existing Gaja Capital funds
- Repayment of bridge financing
- Sponsor commitment to proposed Fund V
- Sponsor commitment to a proposed Secondaries Fund.
This is the most important use-of-proceeds item.
Fresh IPO Capital Can Help Gaja Raise Larger Funds
An alternative asset manager often invests some of its own capital alongside limited partners.
This demonstrates alignment.
Suppose Gaja wants to launch a much larger new fund.
Its own sponsor commitment may also need to increase.
Fresh IPO capital can help support that.
The financial leverage effect can be substantial:
Gaja invests ₹100 crore of sponsor capital → external investors potentially commit many multiples of that amount.
If executed successfully, a relatively small amount of company capital can support a much larger fee-paying asset base.
Fund V Could Be a Major Future Growth Driver
The IPO proceeds specifically include sponsor commitments toward a proposed Fund V.
This is important because alternative asset managers grow in fund cycles.
The progression might look like:
Fund II → Fund III → Fund IV → Fund V.
If each successful fund becomes larger, management-fee revenue can compound.
Therefore, the size, fundraising progress and investment performance of Fund V may become among the most important post-listing developments.
Secondaries Could Add a New Growth Engine
Gaja also plans sponsor commitments toward a Secondaries Fund.
Private-market secondaries involve buying and selling existing interests in private investments or funds rather than only making new primary investments.
This can broaden the company's product offering.
A successful secondaries strategy could allow Gaja to attract additional investor capital without relying exclusively on its traditional mid-market private equity funds.
Gaja Focuses on Mid-Market Companies
The company primarily targets deal sizes of approximately ₹50 crore to ₹250 crore.
This places Gaja in the Indian mid-market.
These businesses may already have meaningful operations but still have considerable growth ahead.
They can benefit from:
- Professionalisation
- Management strengthening
- Expansion
- Technology
- New markets
Gaja's objective is to invest before those improvements are fully reflected in valuation.
Sector Diversification Is Broad
Gaja's investment focus includes sectors such as:
- Education
- Energy and environment
- Financial services
- Consumer businesses
- Digital technology.
This provides sector diversification.
A downturn in one industry does not automatically affect every portfolio company in the same way.
However, most investments remain exposed to India's broader economic and private-market environment.
AUM Growth Is the Core Long-Term Opportunity
Asset management becomes powerful when assets under management compound.
Consider a simplified example.
Suppose Gaja manages:
₹5,000 crore
and eventually grows to:
₹10,000 crore.
If its fee economics remain broadly similar, management-fee income can expand substantially without requiring twice as much physical infrastructure.
The company may need more investment professionals, but it does not need:
- Double the factories
- Double the warehouses
- Double the inventory
This gives the business significant scalability.
India's Alternative Investment Industry Is Growing Rapidly
Economic Times cites a CRISIL forecast that India's alternative-investment AUM could grow at approximately 25%–27% annually, reaching around ₹41 lakh crore to ₹44 lakh crore by March 2030.
This creates a favourable industry backdrop.
More wealth, institutional allocations and private-company funding can create additional opportunities for established alternative asset managers.
Gaja does not need to capture the entire market.
Even maintaining a modest share of a rapidly expanding industry can support growth.
Global Limited Partners Expand the Fundraising Opportunity
Gaja's fund investors are spread across more than 20 countries, including India, the US, Europe and the Middle East.
This matters because the company is not dependent only on Indian high-net-worth investors.
Its fundraising pool can include:
- Institutional investors
- Family offices
- International investors
- Wealthy individuals
A diversified limited-partner base can improve fundraising resilience.
Investment Performance Is Gaja's Biggest Competitive Advantage
Across previous investments and funds, Gaja has generated an average Multiple on Invested Capital of approximately 3.3×.
Its three funds have generated MOICs ranging approximately from:
1.7× to 3.8×.
MOIC measures how much investment value has been generated relative to original capital.
For example:
₹100 invested becoming ₹330 corresponds to approximately 3.3× gross value.
A strong historical track record can make future fundraising easier.
But Historical Returns Do Not Guarantee Future Returns
This point is particularly important for Gaja.
A private equity manager can have an excellent historical record.
Future funds may still perform differently because:
- Entry valuations change
- Competition increases
- Economic cycles shift
- Portfolio companies underperform
- Exit markets weaken
Therefore, investors should not apply the historical 3.3× MOIC automatically to future funds.
The quality of new investments will determine future economics.
Successful Exits Drive the Entire Flywheel
The strongest Gaja growth cycle looks like:
good investments → portfolio growth → profitable exits → strong fund returns → higher carried interest → stronger reputation → larger future funds.
This creates a reinforcing cycle.
Each successful fund makes the next fundraising exercise easier.
Poor Exits Can Reverse the Flywheel
The opposite is equally important.
weak investments → poor exits → lower investor returns → reduced carried interest → difficult fundraising.
This is why alternative asset management is partly a reputation business.
Once institutional investors lose confidence in a manager's investment process, rebuilding that confidence can take years.
FY2026 Total Income Reached ₹157.80 Crore
Gaja reported:
| Financial Year | Total Income | PAT |
|---|---|---|
| FY2025 | ₹123.31 Cr | ₹61.95 Cr |
| FY2026 | ₹157.80 Cr | ₹81.96 Cr |
Total income increased approximately 28% year-on-year, while PAT increased by about 32%.
This is healthy growth.
More importantly, profit increased faster than income.
FY2024 to FY2026 Shows Stronger Multi-Year Growth
Economic Times reports total income increasing from approximately:
₹104 crore in FY2024
to:
₹158 crore in FY2026.
PAT increased from approximately:
₹45 crore
to:
₹82 crore over the same period.
This means the company's financial expansion is not limited to one year.
PAT Margin Reached Around 52%
FY2026 PAT of ₹81.96 crore against total income of ₹157.80 crore produces a margin of approximately:
52%.
That is exceptionally high compared with:
- Manufacturing
- Retail
- Logistics
- Most financial businesses
This is possible because Gaja's model has low physical capital requirements and substantial performance-linked income.
Cost-to-Income Ratio Improved to 44.6%
Gaja's cost-to-income ratio declined to approximately:
44.6% in FY2026
from:
52.3% in FY2025.
This indicates operating leverage.
Income grew faster than costs.
For a scalable asset manager, this is an attractive pattern.
If AUM and fee income expand while the investment team grows more slowly, margins can remain strong.
ROE Improved to 16.5%
Return on equity increased to approximately:
16.5% in FY2026
from:
14.5% in FY2024.
This is healthy, although it is not extraordinarily high compared with some other asset-light financial businesses.
Fresh IPO equity will increase the capital base considerably.
Therefore, post-IPO ROE may initially decline unless the new sponsor commitments begin generating higher earnings.
Only 37 People Supported the Business in FY2026
As of March 31, 2026, Gaja had just 37 personnel, comprising:
- 23 permanent employees
- 14 contractual personnel.
This is an unusually small workforce relative to the company's profit.
It demonstrates how asset-light alternative asset management can be.
But it also creates significant dependency on a relatively small group of experienced investment professionals.
Key-Person Risk Is Especially Important
A factory's machinery remains even if one manager resigns.
A private equity firm's intellectual capital is concentrated in people.
Senior professionals often maintain:
- Investor relationships
- Entrepreneur networks
- Investment judgement
- Deal sourcing relationships
If several key professionals leave, the impact could be substantial.
Talent retention is therefore one of the most important risks in the business.
Gaja's Assets Are Mostly Intangible
The company's real economic assets include:
track record + reputation + investor relationships + deal sourcing + investment expertise.
These do not appear neatly as factories or machinery on the balance sheet.
But they determine whether future investors will trust Gaja with billions of rupees.
This makes governance and reputation especially important.
Promoter Holding Will Fall to Around 54%
Economic Times reports promoter holding declining from approximately:
71% before the IPO
to:
54% after the issue.
Promoters therefore retain control, but public ownership increases meaningfully.
For investors, governance standards become increasingly important as the business transitions into the listed market.
The IPO Is Fresh-Issue Heavy
The offer includes:
₹450 crore fresh issue
and:
₹100 crore OFS.
Therefore, approximately 82% of the headline IPO size is fresh capital.
That is an important positive structural feature.
Most of the transaction is intended to strengthen the company rather than simply allowing existing shareholders to cash out.
OFS Proceeds Do Not Go to Gaja
The ₹100 crore Offer for Sale is paid to selling shareholders.
It does not fund:
- Sponsor commitments
- Fund V
- Secondaries Fund
- Business growth
Therefore, investors should distinguish between:
₹550 crore headline IPO size
and:
₹450 crore capital actually being raised by Gaja.
Gaja IPO Valuation Is Around 27.5× FY2026 Earnings
At the ₹160 upper band, Gaja is valued at approximately:
27.5× FY2026 P/E
and:
2.1× FY2026 price-to-book.
The post-issue market capitalisation is estimated around:
₹2,256 crore.
This is not a bargain valuation.
Investors are paying for:
- Strong track record
- High margins
- Alternative investment growth
- Future fundraising potential
Gaja Has No Direct Listed Private Equity Peer
Economic Times notes that Gaja would be the first standalone private equity firm to list on Indian exchanges, meaning there is no directly comparable domestic listed peer.
Traditional listed asset managers trade at roughly 25×–40× earnings, according to the same analysis.
But comparisons have limitations.
A mutual fund AMC usually derives more revenue from recurring management fees.
Gaja has much greater exposure to:
- Carried interest
- Sponsor investment returns
- Private-market exits
That can create both higher upside and greater earnings volatility.
Gaja Is Not the Same as a Mutual Fund AMC
This distinction matters.
A traditional mutual fund manager may have thousands or millions of retail investors whose money remains invested in liquid funds.
Gaja's funds are typically:
- Long-duration
- Private-market
- Institutionally oriented
The revenue model therefore depends much more heavily on investment cycles.
That makes the earnings profile less predictable but potentially more lucrative.
Exit Markets Are a Major Risk
Private equity ultimately needs to sell investments.
Exit routes can include:
- IPOs
- Strategic acquisitions
- Secondary sales
- Promoter buybacks
If capital markets weaken, exits can be delayed.
That can reduce:
- Carried interest
- Cash distributions
- Investor returns
and may slow future fundraising.
Therefore, Gaja is indirectly exposed to equity-market and M&A conditions even though it invests mainly in private companies.
Entry Valuation Matters as Much as Exit Valuation
Suppose Gaja buys a company at ₹500 crore and later exits at ₹1,500 crore.
That creates excellent value.
But if the same company is purchased at ₹1,200 crore and eventually sells for ₹1,500 crore, the return is much weaker.
Private equity returns therefore depend heavily on paying the right price when investments are made.
As more capital flows into Indian private markets, competition for attractive companies can push valuations higher.
Competition for Deals Is Increasing
Gaja competes with:
- Domestic private equity firms
- Global PE funds
- Sovereign wealth funds
- Family offices
- Large institutional investors
More capital chasing high-quality Indian businesses can increase entry prices.
This can reduce future returns unless portfolio companies grow sufficiently.
The company's historical 3.3× MOIC is strong, but maintaining similar performance may become increasingly difficult in a more competitive market.
Regulatory Risk Is Important
Alternative Investment Funds operate under a regulated framework.
Changes in regulations involving:
- AIF structures
- Fees
- taxation
- investor eligibility
- leverage
- valuation
- disclosures
can affect Gaja's business.
Economic Times specifically identifies regulatory changes as one of the key risks to the investment case.
Revenue Concentration by Income Type Matters
Because carried interest represented nearly 48% of FY2026 total income, investors should separate:
recurring management-fee income
from:
performance-linked income.
A company with ₹100 crore of recurring management fees may deserve a different valuation from one with ₹100 crore of one-time carried interest.
This revenue-quality distinction will be important after listing.
AUM Growth Alone Is Not Enough
Suppose Gaja doubles AUM but invests poorly.
Management-fee income may rise temporarily.
But future fundraising can become harder if returns deteriorate.
Therefore, the strongest model is not:
largest possible AUM.
It is:
high-quality AUM producing attractive long-term returns.
That is how sustainable asset-management franchises are created.
Competitive Strengths
Gaja enters the IPO with several significant strengths.
Long operating history: Incorporated in 1999 and operating for more than two decades.
Strong historical investment returns: Average MOIC around 3.3× across prior investments and funds.
International investor base: Limited partners across more than 20 countries.
Strong FY2026 profitability: ₹157.80 crore total income and ₹81.96 crore PAT.
High margins: Net margin around 52%.
Asset-light model: Only 37 employees/contract personnel supported the business at FY2026 year-end.
Fresh-issue-heavy IPO: ₹450 crore of the ₹550 crore issue is fresh capital.
Industry growth: India's alternatives AUM is projected by CRISIL to grow rapidly through 2030.
Major Risks
Carried-Interest Volatility
Nearly 48% of FY2026 income came from carried interest, making earnings sensitive to investment exits and fund performance.
Investment Performance
Poor portfolio returns can reduce future fundraising and sponsor income.
Exit-Market Risk
Weak IPO and M&A markets can delay portfolio exits.
Key-Person Dependence
The company has a small specialist workforce and depends heavily on experienced investment professionals.
Regulatory Risk
Changes in the alternative investment framework could affect the business.
Valuation
At approximately 27.5× FY2026 earnings, investors are already paying for future growth.
Competitive Private Markets
More global and domestic capital competing for Indian companies may compress future investment returns.
What Could Drive Gaja Capital's Next Growth Phase?
Fund V
A successful larger fifth fund could materially increase fee-paying assets.
Secondaries Fund
This can broaden Gaja's strategy beyond its existing private-equity products.
Strong Portfolio Exits
Successful exits can generate carried interest while improving Gaja's fundraising track record.
India's AIF Growth
The overall alternatives market is projected to expand rapidly.
International LPs
Existing relationships across more than 20 countries create a large fundraising network.
Sponsor Capital
Fresh IPO proceeds can help Gaja participate meaningfully in future funds.
What Investors Should Track After Listing
| Metric | Why It Matters |
|---|---|
| Total AUM | Platform scale |
| Fee-Paying AUM | Recurring revenue |
| Management Fees | Earnings stability |
| Carried Interest | Investment performance |
| Sponsor Income | Return on own capital |
| Fund V Size | Future growth |
| New Fundraising | Investor confidence |
| Portfolio Exits | Realised returns |
| MOIC | Investment quality |
| Cost-to-Income | Operating leverage |
| ROE | Capital efficiency |
| Key Employee Retention | Franchise strength |
For Gaja, AUM, realised returns and recurring fee income will be more useful long-term indicators than quarterly revenue alone.
The Most Important Post-IPO Equation
The strongest scenario looks like:
IPO capital → larger sponsor commitments → bigger funds → successful investments → profitable exits → higher management fees + carried interest → stronger future fundraising.
The weaker scenario looks like:
larger funds → expensive investments → weaker returns → lower carried interest → harder future fundraising.
Both scenarios can initially increase AUM.
Only the first creates a stronger asset-management franchise.
Should Investors Consider Gaja Alternative Asset Management IPO?
The positive investment case includes:
- More than 20 years of operating experience
- ₹157.80 crore FY2026 total income
- ₹81.96 crore FY2026 PAT
- Approximately 52% net margin
- Historical 3.3× average MOIC
- International investor base across 20+ countries
- Asset-light business model
- ₹450 crore fresh issue
- Exposure to India's fast-growing alternative investment industry
- Current ₹30 GMP.
The caution case includes:
- Nearly half of FY2026 income coming from carried interest
- Dependence on investment performance
- Exit-market risk
- Key-person risk
- Regulatory risk
- Competitive deal valuations
- IPO valuation around 27.5× FY2026 earnings.
Gaja should therefore be evaluated as a listed private equity and alternative asset management franchise, rather than as a conventional mutual fund AMC or finance company.
Final View on Gaja Alternative Asset Management IPO 2026
The Gaja Alternative Asset Management IPO opened today, August 19, 2026, and will remain open until August 21. The ₹550 crore mainboard issue has a price band of ₹152–₹160 per share, a minimum lot of 93 shares and an investment requirement of ₹14,880 at the upper band. Allotment is expected August 24, with listing scheduled for August 26 on BSE and NSE.
The issue contains ₹450 crore of fresh shares and ₹100 crore OFS. Approximately ₹372 crore of fresh proceeds will support sponsor commitments to existing and proposed funds and repayment of bridge financing.
Today's early bidding shows moderate interest. As of 11:50 AM, the issue was approximately 0.31× subscribed overall, with retail at 0.47×, NII at 0.35× and QIB yet to receive bids.
Grey-market sentiment is significantly stronger. The latest reported GMP is around ₹30, implying an unofficial price near ₹190 and approximately 19% premium over the ₹160 upper band.
Fundamentally, Gaja enters the IPO with a differentiated business model and strong FY2026 numbers. Total income increased to ₹157.80 crore, while PAT reached ₹81.96 crore, producing a net margin close to 52%. Its historical investments and funds have generated an average MOIC of about 3.3×.
The most important caution is the composition of those profits.
Nearly 48% of FY2026 total income came from carried interest, which is inherently dependent on successful portfolio exits and investment performance.
This means future earnings may not move smoothly every year.
The long-term thesis is nevertheless compelling if Gaja can continue the cycle:
strong investment returns → successful exits → larger Fund V and new strategies → higher AUM → higher recurring fees → more carried interest → stronger future fundraising.
At the ₹160 upper band, the company is valued at around 27.5× FY2026 earnings, with an estimated post-issue market capitalisation of approximately ₹2,256 crore.
Loading comments...