
Lumino Industries IPO 2026 – Power Transmission Player Prepares for Mainboard Listing
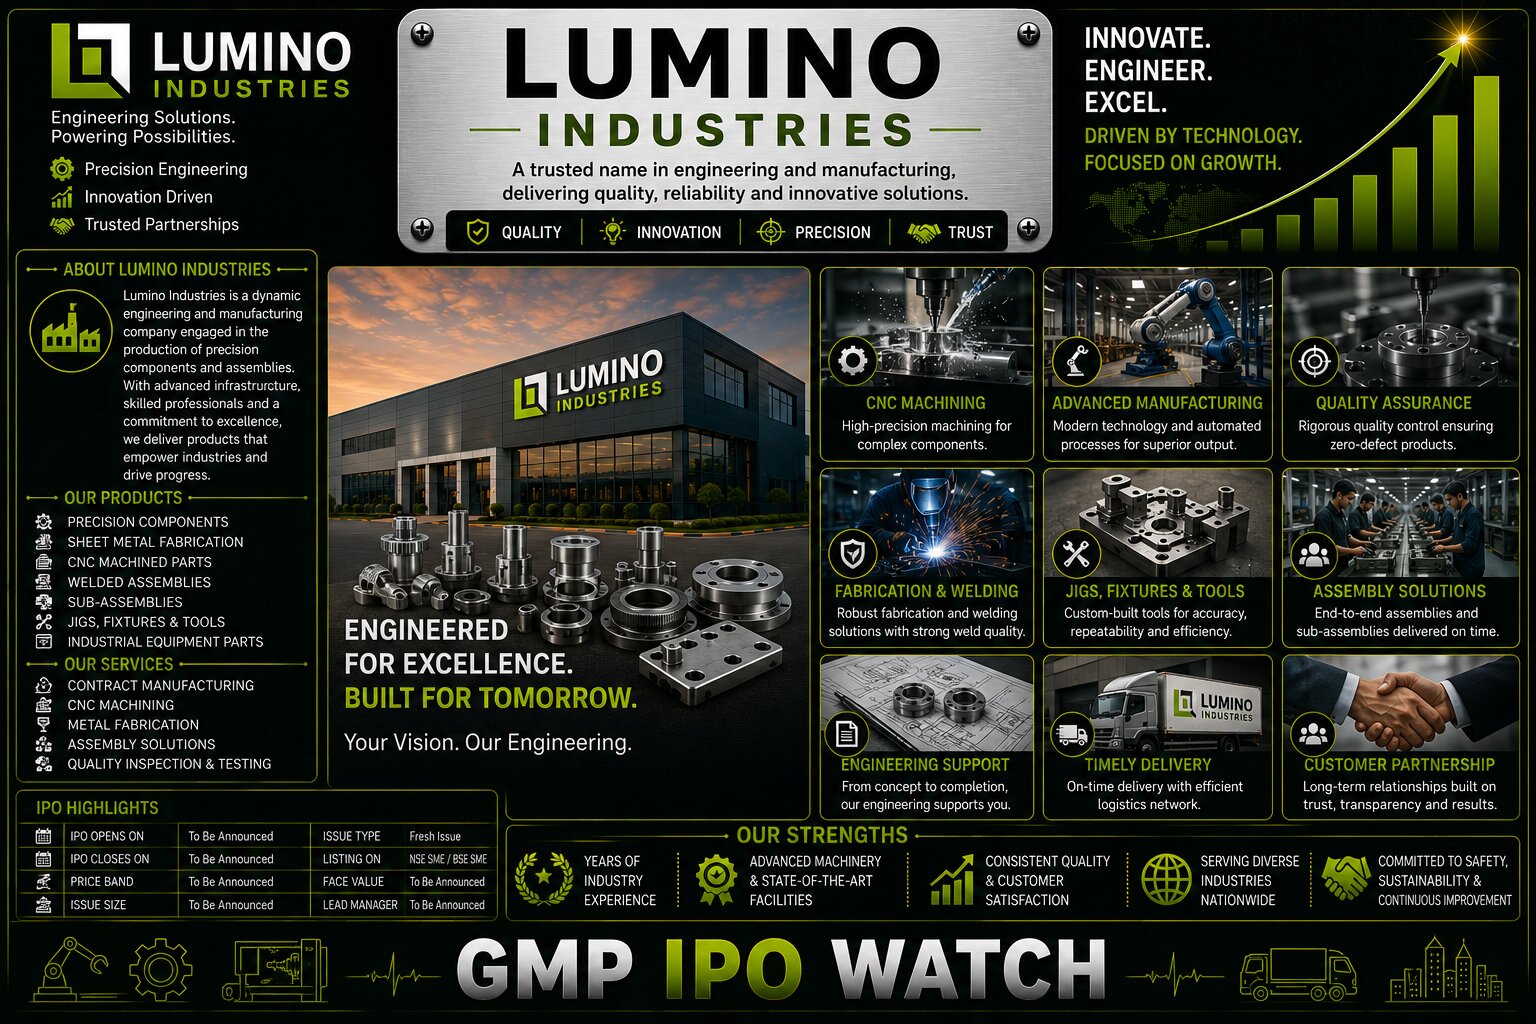
Lumino Industries Limited is preparing to launch its ₹700 crore mainboard IPO on August 27, 2026, with bidding scheduled to close on August 31.
The company operates in India's power transmission and distribution ecosystem through a combination of manufacturing and EPC activities. Its products include conductors, power cables, electrical wires and specialised high-temperature low-sag conductors, while its EPC operations cover transmission, distribution, substations, railway electrification and other infrastructure projects.
This makes Lumino Industries more than a conventional cable manufacturer.
Its business is positioned around:
power equipment manufacturing + EPC execution + grid modernisation + renewable-energy infrastructure + international customers.
Lumino Industries IPO Details
| Particular | Details |
|---|---|
| Company | Lumino Industries Limited |
| IPO Type | Mainboard IPO |
| Issue Type | Book Built Issue |
| Issue Size | ₹700 Crore |
| Fresh Issue | ₹500 Crore |
| Offer for Sale | ₹200 Crore |
| Price Band | ₹78 – ₹82 |
| Face Value | ₹5 |
| Lot Size | 182 Shares |
| Minimum Retail Investment | ₹14,924 |
| Anchor Investor Date | August 25, 2026 |
| IPO Open Date | August 27, 2026 |
| IPO Close Date | August 31, 2026 |
| Allotment Date | September 1, 2026 |
| Refund / Demat Date | September 2, 2026 |
| Listing Date | September 3, 2026 |
| Listing | BSE & NSE |
At the upper price band, one lot of 182 shares requires ₹14,924. The ₹700 crore offer comprises ₹500 crore of fresh shares and a ₹200 crore OFS by promoter shareholders Devendra Goel and Jay Goel.
SEBI's public-issue records show that Lumino Industries' RHP and abridged prospectus were filed on August 21, 2026.
Lumino Industries IPO GMP
Grey-market activity has already started ahead of the issue opening.
One current tracker reported a ₹46 GMP as of August 22, against the upper issue price of ₹82. That represents an indicative premium of roughly 56%, although GMP can change substantially before listing.
| GMP Particular | Details |
|---|---|
| Upper Issue Price | ₹82 |
| Reported GMP | ₹46 |
| Indicative Price | ₹128 |
| Indicative Premium | ~56.1% |
| IPO Status | Upcoming |
GMP is unofficial and unregulated, so it should not be treated as a guaranteed listing return.
What Does Lumino Industries Do?
Lumino Industries was established in 2005 and operates as an integrated engineering, procurement and construction and manufacturing company focused mainly on the power transmission and distribution sector.
Its manufacturing portfolio includes:
conductors + power cables + electrical wires + HTLS conductors.
These products are used to move electricity through transmission and distribution networks.
At the same time, Lumino executes EPC projects across several infrastructure categories.
Manufacturing and EPC Create Two Business Engines
Lumino's business model has an interesting combination.
The manufacturing side produces components required by electricity networks.
The EPC side participates directly in building infrastructure.
This can create a broader revenue opportunity:
manufacture power products → supply infrastructure projects → execute EPC contracts → participate in grid expansion.
The combination can also allow the company to capture a larger portion of power-infrastructure spending than a manufacturer selling only individual components.
EPC Business Covers Multiple Infrastructure Segments
Lumino's EPC capabilities extend across:
- Power transmission
- Power distribution
- EHV substations
- HTLS reconductoring
- Railway electrification
- Solar power projects
- Water-management projects.
This diversification is important because the company's growth is not tied exclusively to one type of power project.
For example, traditional grid expansion and renewable-energy development can both create demand for transmission infrastructure.
HTLS Conductors Are an Interesting Product Category
High-Temperature Low-Sag or HTLS conductors are designed to carry higher electrical loads while limiting excessive conductor sag.
This can be particularly useful when utilities need to increase the capacity of existing transmission corridors.
Instead of constructing an entirely new transmission line, utilities may sometimes upgrade existing infrastructure through reconductoring.
For Lumino, this creates exposure not only to new transmission projects but also to grid modernisation and capacity upgrades.
FY2026 Profit Increased Faster Than Revenue
Lumino Industries delivered an improvement in its latest financial year.
| Financial Metric | FY2025 | FY2026 |
|---|---|---|
| Total Income | ₹1,946.68 Cr | ₹2,089.31 Cr |
| PAT | ₹124.59 Cr | ₹160.00 Cr |
| Income Growth | — | ~7% |
| PAT Growth | — | ~28% |
Total income increased around 7%, while profit after tax increased approximately 28% in FY2026.
The faster growth in profit is significant.
It suggests that Lumino generated better earnings from a relatively moderate increase in its overall business scale.
₹337 Crore Will Be Used for Debt Repayment
The most important use of the fresh issue is deleveraging.
Lumino plans to deploy approximately:
₹337 crore
toward prepayment or repayment of certain outstanding borrowings.
Use of Fresh IPO Proceeds
| Purpose | Approx. Amount |
|---|---|
| Debt Repayment / Prepayment | ₹337.00 Cr |
| Capital Expenditure | ₹15.01 Cr |
| General Corporate Purposes | Balance |
| Total Fresh Issue | ₹500.00 Cr |
Debt repayment therefore represents approximately 67% of the ₹500 crore fresh issue.
This is one of the most important factors in the IPO.
Deleveraging Could Improve Future Profitability
Power infrastructure and EPC businesses can require substantial capital.
Companies need funds for:
raw materials + project execution + receivables + bank guarantees + inventory + manufacturing operations.
Debt is often used to bridge these requirements.
Lumino's proposed ₹337 crore repayment could reduce finance costs and strengthen its balance sheet.
The potential equation is:
lower debt → lower interest expense → stronger cash flow → improved financial flexibility.
This could become particularly useful if the company wants to pursue larger EPC projects after listing.
₹15.01 Crore Is Planned for Manufacturing Capex
Lumino also plans to invest approximately ₹15.01 crore in capital expenditure.
The expenditure includes equipment and machinery purchases along with civil works and interior development at an existing manufacturing facility.
Although this amount is much smaller than the debt-repayment allocation, it indicates that part of the IPO capital will directly support manufacturing infrastructure.
India's Electricity Demand Creates a Large Opportunity
India's electricity consumption continues to expand alongside:
industrialisation + urbanisation + data centres + manufacturing + electric mobility + household demand.
More electricity generation eventually requires more infrastructure to move that electricity.
That means:
generation growth → transmission expansion → distribution upgrades → demand for conductors, cables and EPC services.
Lumino operates directly within this chain.
Renewable Energy Also Needs Transmission Infrastructure
Solar and wind projects are often built far from major consumption centres.
Electricity therefore needs to be transported from renewable-generation locations to cities and industrial areas.
This creates requirements for:
transmission lines + substations + conductors + grid upgrades.
As India's renewable-energy capacity grows, transmission infrastructure must expand alongside it.
Lumino's exposure to both transmission equipment and EPC projects positions it to participate in this broader infrastructure build-out.
Railway Electrification Adds Another Demand Source
Lumino's EPC operations also include railway electrification.
This provides another infrastructure vertical beyond conventional utility projects.
Diversification can help reduce dependence on a single source of project demand.
However, EPC diversification also requires strong execution capabilities because different infrastructure categories can involve different technical requirements and project timelines.
International Customers Expand the Addressable Market
Lumino serves customers outside India as well, including government-owned electricity companies, public enterprises and electricity boards across several countries.
International operations can provide:
geographic diversification + larger addressable market + export revenue opportunities.
But overseas projects can also introduce additional risks involving foreign exchange, logistics, political conditions and payment collection.
890 Permanent Employees Support Operations
As of March 31, 2026, Lumino Industries had approximately 890 permanent employees.
For an engineering and EPC business, technical capabilities are important because project execution requires:
engineering + procurement + manufacturing + project management + quality control.
The company's ability to maintain experienced teams will therefore matter as its project portfolio grows.
IPO Valuation Looks Lower Than the Reported Peer Average
At the IPO price band, Lumino is valued at approximately:
11.87× P/E at ₹78
and:
12.48× P/E at ₹82
based on diluted FY2026 earnings.
The offer document's reported peer-group average P/E is approximately 48.55×.
| Valuation Metric | Multiple |
|---|---|
| P/E at ₹78 | 11.87× |
| P/E at ₹82 | 12.48× |
| Reported Peer Average | 48.55× |
This headline comparison makes the IPO valuation appear considerably lower than the stated peer average.
However, P/E alone should not determine valuation.
Investors should also compare business mix, margins, debt, working-capital intensity, order-book quality and return ratios because an EPC-heavy company can have different economics from a pure cable or electrical-equipment manufacturer.
Fresh Issue Is the Majority of the IPO
Of the ₹700 crore total IPO:
₹500 crore is fresh issue
and:
₹200 crore is OFS.
That means approximately:
| IPO Component | Amount | Share of Issue |
|---|---|---|
| Fresh Issue | ₹500 Cr | ~71.4% |
| OFS | ₹200 Cr | ~28.6% |
| Total | ₹700 Cr | 100% |
A majority of the IPO capital therefore goes into the company.
The OFS portion is being sold by promoters Devendra Goel and Jay Goel.
Working Capital Will Remain Important
EPC businesses frequently experience a timing gap between spending money and receiving customer payments.
A project may require Lumino to:
purchase materials → manufacture equipment → mobilise employees → execute work → complete milestones → raise invoices → collect payment.
That means accounting profits and operating cash flows can differ substantially.
Investors should therefore track receivable days and operating cash flow rather than focusing only on PAT.
Raw-Material Prices Can Affect Margins
Conductors, wires and cables require commodities such as aluminium, copper and other industrial materials.
Price movements can influence:
manufacturing cost + working-capital requirements + project margins.
If input prices rise sharply while project contracts have limited price-escalation protection, profitability can come under pressure.
Procurement and contract management are therefore important parts of Lumino's business economics.
EPC Execution Risk Cannot Be Ignored
Large infrastructure projects can experience:
- Land-related delays
- Customer approvals
- Material shortages
- Labour issues
- Regulatory delays
- Weather disruption
- Cost escalation
- Payment delays
Any of these can extend project timelines.
For an EPC company, winning orders is only the first step.
The more important task is completing projects on time and within the expected margin.
Key Strengths of Lumino Industries
Lumino enters the IPO with several attractive characteristics.
Integrated model: The company combines manufacturing with EPC capabilities across the power transmission and distribution sector.
Large operating scale: FY2026 total income exceeded ₹2,089 crore.
Strong recent profit growth: PAT increased approximately 28% to ₹160 crore in FY2026.
Power-sector exposure: India's grid expansion and renewable-energy development can support long-term demand.
Diversified EPC capabilities: Transmission, distribution, substations, railway electrification, solar and water projects provide multiple demand sources.
International presence: The company serves overseas electricity companies and public-sector customers.
IPO deleveraging: Approximately ₹337 crore is earmarked for debt repayment.
Major Risks
Investors should also monitor several important risks:
- EPC project execution delays
- High working-capital requirements
- Customer receivable delays
- Raw-material price volatility
- Dependence on infrastructure spending
- Competitive bidding pressure
- Government and utility customer exposure
- International project risks
- Foreign-exchange movements
- Order-book conversion
- Manufacturing utilisation
- Project margin volatility
The company's ability to convert reported profits into cash will be particularly important.
What Investors Should Track After Listing
| Metric | Why It Matters |
|---|---|
| Order Book | Future revenue visibility |
| New Order Wins | Growth momentum |
| Revenue Growth | Business expansion |
| EBITDA Margin | Operating profitability |
| PAT Growth | Earnings performance |
| Operating Cash Flow | Earnings quality |
| Receivable Days | Collection efficiency |
| Debt | IPO deleveraging |
| Finance Cost | Debt-repayment benefit |
| Manufacturing Utilisation | Asset efficiency |
| Export Revenue | International expansion |
| ROCE | Capital productivity |
For Lumino Industries, one of the most important post-listing combinations will be:
order-book growth + stable margins + lower debt + stronger operating cash flow.
Final View on Lumino Industries IPO 2026
The Lumino Industries IPO will open on August 27 and close on August 31, 2026, with a price band of ₹78–₹82 per share. The ₹700 crore mainboard issue comprises a ₹500 crore fresh issue and ₹200 crore OFS, with tentative listing scheduled for September 3 on BSE and NSE.
Financial performance improved in FY2026. Total income increased around 7% to ₹2,089.31 crore, while PAT increased approximately 28% to ₹160 crore, compared with ₹124.59 crore in FY2025.
The most important immediate benefit of the IPO could be deleveraging. Lumino intends to use approximately ₹337 crore for repayment or prepayment of borrowings, while ₹15.01 crore is planned for manufacturing-related capital expenditure.
The longer-term opportunity comes from India's requirement for additional transmission and distribution infrastructure as electricity demand and renewable generation increase.
Loading comments...