
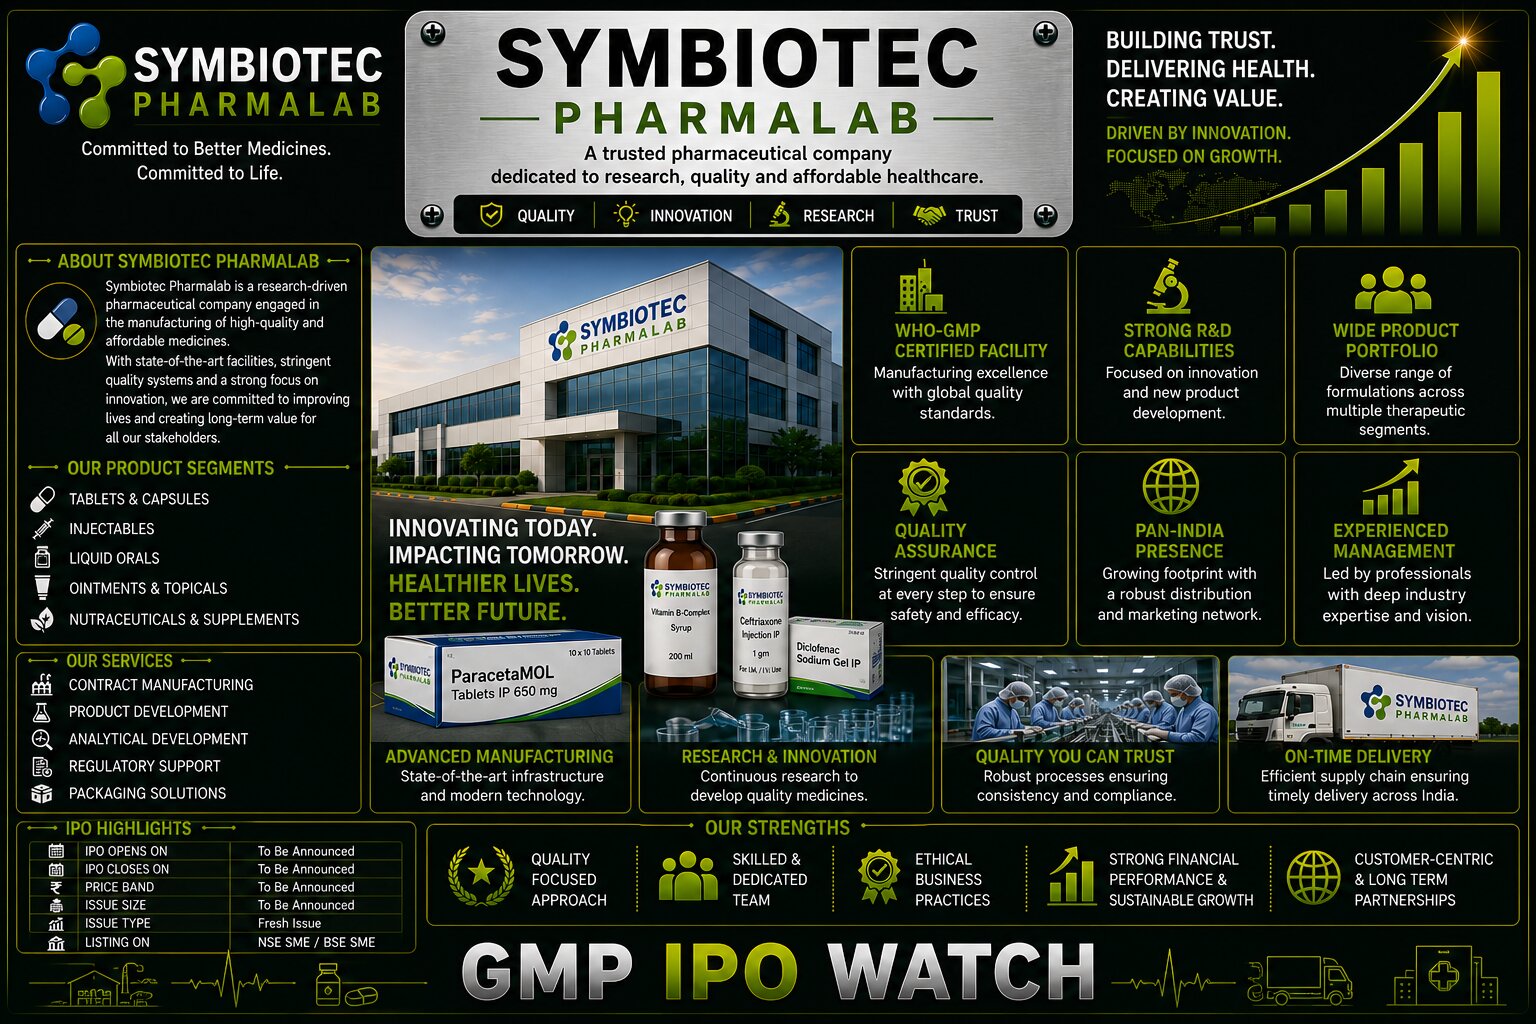
Symbiotec Pharmalab IPO 2026 – Day 2 Demand Picks Up
Symbiotec Pharmalab Limited's IPO entered its second subscription day today, August 25, 2026, with investor participation strengthening considerably.
The IPO opened on August 24 and will remain available for bidding until August 27. On Day 1, it closed at approximately 0.80 times subscription. By around 10:50 AM today, demand had increased to approximately 1.12 times, taking the IPO past full subscription.
The company operates as a pharmaceutical contract development and manufacturing organisation (CDMO) and has a particularly strong position in corticosteroid and steroidal-hormone APIs.
Symbiotec Pharmalab IPO Details
| Particular | Details |
|---|---|
| IPO Type | Mainboard IPO |
| Issue Size | ₹1,757 Crore |
| Fresh Issue | ₹150 Crore |
| Offer for Sale | ₹1,607 Crore |
| Price Band | ₹938 – ₹988 |
| Face Value | ₹2 |
| Lot Size | 15 Shares |
| Minimum Investment | ₹14,820 |
| IPO Open Date | August 24, 2026 |
| IPO Close Date | August 27, 2026 |
| Allotment Date | August 28, 2026 |
| Refund / Demat | August 31, 2026 |
| Listing Date | September 1, 2026 |
| Listing | BSE & NSE |
The ₹1,757 crore offer consists primarily of an OFS, while only ₹150 crore represents fresh capital being raised by the company.
Symbiotec Pharmalab IPO GMP Today
Grey-market sentiment remains positive on Day 2, although the premium has moderated from the stronger levels reported when the IPO opened.
Current reports indicate an unofficial GMP suggesting approximately 34% to 34.4% potential upside over the upper issue price.
| GMP Particular | Day 2 Update |
|---|---|
| Upper Issue Price | ₹988 |
| Indicative GMP Trend | ~34% |
| Approx. Indicative Price | ~₹1,328 |
| IPO Status | Open |
| Subscription Day | Day 2 |
This is lower than the roughly 41% GMP reported on the opening day, showing that grey-market sentiment can move significantly even while subscription demand improves.
GMP is unofficial and should not be considered a guaranteed listing return.
IPO Crosses Full Subscription on Day 2
The most important update today is the improvement in subscription.
Day 1 ended with bids for approximately 1.05 crore shares against 1.31 crore shares available, translating into overall subscription of about 0.80 times.
By 10:50 AM on August 25, overall subscription had increased to around 1.12 times, according to NSE data cited by Moneycontrol.
| Subscription Stage | Overall Demand |
|---|---|
| Day 1 Closing | ~0.80× |
| Day 2 – 10:50 AM | ~1.12× |
| Current Status | Fully Subscribed |
These are live figures and can change significantly as bidding continues through August 27.
What Does Symbiotec Pharmalab Do?
Symbiotec is a research-driven pharmaceutical and biotechnology company operating as a CDMO for global specialty pharmaceutical and nutraceutical companies.
Its capabilities span three major technology platforms:
Organic Chemistry + Biotechnology + Complex Injectables.
The company also manufactures its own products, giving it a business model broader than simply providing contract manufacturing services.
Its manufacturing expertise is particularly strong in specialised steroid-based APIs.
Strong Position in Steroidal APIs
One of the most distinctive aspects of Symbiotec's business is its global position in steroid APIs.
According to the Frost & Sullivan data cited in IPO materials, the company held approximately:
| API Category | Global Volume Market Share |
|---|---|
| Corticosteroid APIs | 38.2% |
| Steroidal-Hormone APIs | 23.8% |
Symbiotec is also reported to be the only company globally with a presence across the top 10 products in both categories.
This creates a specialised pharmaceutical manufacturing position that is difficult to replicate quickly because steroid APIs require technical capabilities, regulatory compliance and complex manufacturing processes.
International Markets Drive the Business
Symbiotec has developed a substantial global customer base.
More than two-thirds of its revenue comes from international markets, with Europe alone contributing approximately 30%.
| Revenue Exposure | Approx. Contribution |
|---|---|
| International Markets | 66%+ |
| Europe | ~30% |
| India | Less than one-third |
This makes Symbiotec fundamentally an export-oriented pharmaceutical business.
International exposure provides access to a much larger addressable market, but it also creates foreign-exchange, regulatory and geopolitical risks.
FY2026 Revenue Reached ₹869 Crore
Symbiotec entered the IPO after reporting another year of revenue and profit growth.
| Financial Metric | FY2025 | FY2026 |
|---|---|---|
| Revenue | ₹751.6 Cr | ₹869.1 Cr |
| Profit After Tax | ₹96.8 Cr | ₹109.9 Cr |
| Revenue Growth | — | ~15.6% |
| PAT Growth | — | ~13.6% |
Revenue increased approximately 15.6%, while PAT grew around 13.6% during FY2026.
Another financial presentation reports total income of ₹872.26 crore and EBITDA of approximately ₹231.97 crore for FY2026, translating into an EBITDA margin of around 26.6%.
Manufacturing Capacity Supports Future Growth
Symbiotec currently has two operational API manufacturing facilities with maximum chemical-synthesis capacity of approximately 584.67 metric tonnes and fermentation capacity of around 300 KL.
The company has also commissioned additional manufacturing facilities at Ujjain and Mhow in Madhya Pradesh.
It is further expanding biologics capabilities at Ujjain.
This gives the company several potential growth engines:
existing APIs + additional manufacturing capacity + biotechnology + biologics + complex injectables.
The challenge will be achieving sufficient utilisation while maintaining pharmaceutical quality standards.
Product Concentration Remains an Important Risk
Despite its broad capabilities, Symbiotec's revenue remains concentrated among a relatively small number of products.
Its top five products contribute approximately 63% of total revenue.
| Concentration Indicator | Exposure |
|---|---|
| Top 5 Products | ~63% of Revenue |
| International Markets | 66%+ |
| Europe | ~30% |
This is one of the most important risks investors should monitor.
If demand, pricing or competition changes materially for one or more major products, the impact on overall financial performance could be meaningful.
New Products Can Reduce Concentration
The company's R&D capabilities become especially important because of this concentration.
Successful development of additional APIs, biotechnology products and complex injectables could gradually create a broader revenue mix.
The long-term progression would be:
existing steroid leadership → new specialised APIs → biotechnology products → complex injectables → diversified revenue.
This could reduce dependence on the current top-selling products while opening additional markets.
IPO Is Heavily OFS Driven
The ₹1,757 crore IPO has an unusual structure because the overwhelming majority consists of shares being sold by existing investors.
| IPO Component | Amount | Approx. Share |
|---|---|---|
| Fresh Issue | ₹150 Cr | ~8.5% |
| Offer for Sale | ₹1,607 Cr | ~91.5% |
| Total IPO | ₹1,757 Cr | 100% |
The OFS is being undertaken by shareholders including Satwani Holdings LLP, Rosewood Investments and India Business Excellence Fund III.
This means approximately 91.5% of the IPO proceeds go to selling shareholders rather than directly into Symbiotec.
₹112.5 Crore Will Be Used for Debt Repayment
Of the ₹150 crore fresh issue, the company intends to use approximately ₹112.5 crore for repayment or prepayment of certain outstanding borrowings.
Use of Fresh Issue Proceeds
| Purpose | Amount |
|---|---|
| Debt Repayment / Prepayment | ₹112.50 Cr |
| General Corporate Purposes | Balance |
| Total Fresh Issue | ₹150 Cr |
As of March 2026, total outstanding borrowings were reported at approximately ₹349.7 crore.
The planned repayment therefore represents a meaningful reduction.
Debt Reduction Could Improve Future Earnings
Reducing debt can help the company lower finance costs.
The basic financial impact would be:
IPO proceeds → lower borrowings → reduced interest expense → stronger cash flow → improved financial flexibility.
This could become particularly useful as Symbiotec continues investing in manufacturing and biotechnology capabilities.
Investors should therefore compare borrowings and finance costs in the first few post-IPO results.
₹526 Crore Anchor Book Shows Institutional Interest
Before public bidding began, Symbiotec raised approximately ₹526.20 crore from anchor investors.
Reported participants included institutional investors such as Citi Group and Singularity.
Anchor participation does not guarantee listing gains, but it indicates institutional interest ahead of the IPO.
Regulatory Capability Is a Competitive Advantage
Pharmaceutical API manufacturing requires much more than production capacity.
Companies need to consistently meet requirements involving:
product quality + manufacturing processes + documentation + customer audits + regulatory standards + facility compliance.
This creates barriers for new competitors.
For an established API supplier, successful regulatory compliance and long-term customer qualification can make business relationships relatively sticky.
But Regulation Is Also a Major Risk
The same regulatory requirements that protect established manufacturers can create significant downside when something goes wrong.
Quality-control problems or regulatory observations can potentially result in production interruptions, additional compliance costs, customer losses or restrictions in important markets.
This risk becomes particularly important for Symbiotec because more than two-thirds of revenue is generated internationally.
Export Exposure Creates Currency Risk
International sales also expose Symbiotec to currency movements.
A weaker rupee can sometimes increase the rupee value of overseas revenue, while a stronger rupee can have the opposite effect.
However, the final impact also depends on:
imported inputs + hedging + currency mix + customer contracts.
Investors should therefore monitor foreign-exchange gains and losses rather than assuming exports automatically benefit from currency movements.
Key Strengths of Symbiotec Pharmalab
Symbiotec's strongest differentiator is its position in specialised steroid APIs. It holds significant global volume shares in corticosteroid and steroidal-hormone APIs and operates across organic chemistry, biotechnology and complex injectables.
Its other strengths include a sizeable international revenue base, profitable FY2026 operations, established manufacturing infrastructure and an R&D-driven business model.
The proposed ₹112.5 crore debt repayment can also strengthen the balance sheet after the IPO.
Major Risks
Investors should pay particular attention to:
- Top five products contributing around 63% of revenue
- More than two-thirds revenue dependence on international markets
- Pharmaceutical regulatory and quality-control risks
- Foreign-exchange fluctuations
- Raw-material price movements
- Customer concentration
- New-capacity utilisation
- R&D execution
- Approximately 91.5% OFS component
- Changes in GMP and short-term IPO sentiment
The large OFS and high product concentration are particularly important when evaluating the IPO beyond potential listing gains.
What Investors Should Track After Listing
| Metric | Why It Matters |
|---|---|
| Revenue Growth | Business expansion |
| Export Revenue | International demand |
| EBITDA Margin | Operating profitability |
| PAT Growth | Earnings momentum |
| Top 5 Product Share | Concentration risk |
| New Product Revenue | Diversification |
| Capacity Utilisation | Manufacturing efficiency |
| Operating Cash Flow | Earnings quality |
| Borrowings | IPO deleveraging |
| Finance Cost | Debt repayment benefit |
| R&D Pipeline | Future products |
| ROCE | Capital efficiency |
The most interesting long-term indicator may be whether Symbiotec can reduce the 63% contribution from its top five products by successfully scaling newer APIs and biotechnology products.
Final View on Symbiotec Pharmalab IPO
The Symbiotec Pharmalab IPO is on Day 2 today, August 25, 2026, and will close on August 27. The ₹1,757 crore mainboard offering carries a price band of ₹938–₹988 and a lot size of 15 shares.
Investor demand has strengthened significantly. After ending Day 1 at around 0.80× subscription, the issue crossed full subscription on Day 2 and reached approximately 1.12× by 10:50 AM.
Meanwhile, today's GMP indicates approximately 34% potential premium, lower than the roughly 41% level reported when the IPO opened.
Fundamentally, Symbiotec reported FY2026 revenue of approximately ₹869.1 crore and PAT of ₹109.9 crore, representing growth of 15.6% and 13.6%, respectively.
Loading comments...