Gaja Alternative Asset Management IPO 2026 – Can Fund Performance Translate Into Long-Term Listed Growth?
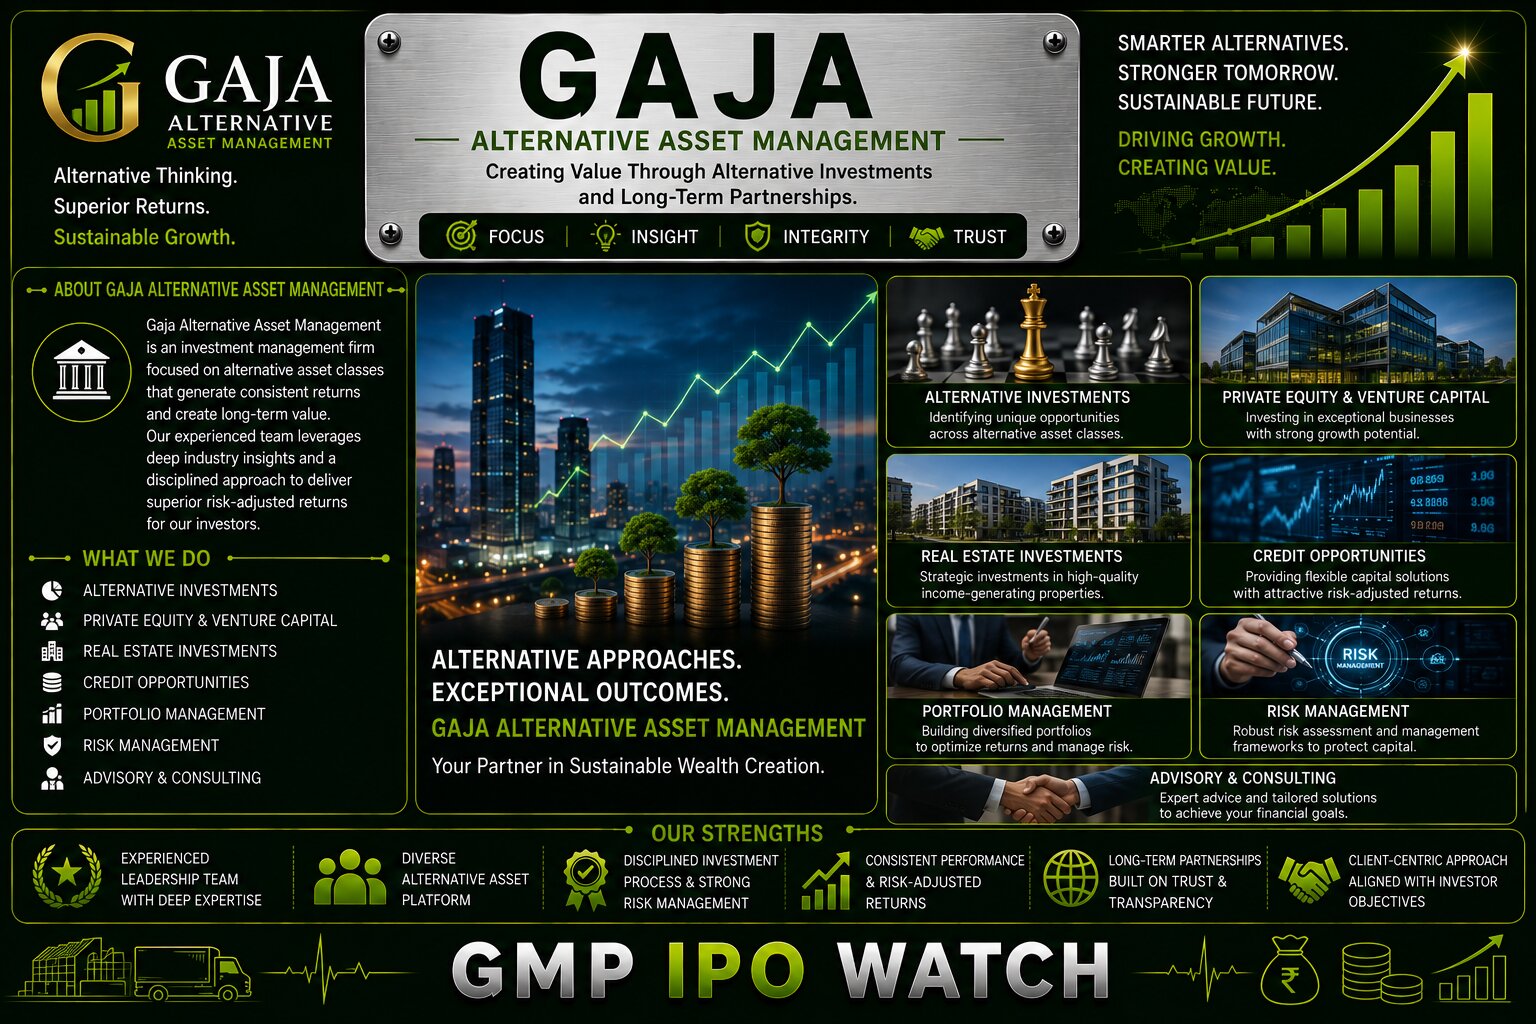
Gaja Alternative Asset Management Limited, commercially known as Gaja Capital, is currently in the second day of its ₹550 crore mainboard IPO.
Unlike manufacturing, jewellery or infrastructure IPOs, Gaja does not need factories, large inventories or extensive physical infrastructure to generate revenue.
Its most important assets are:
investment expertise + investor relationships + fund performance + assets under management.
The company is an India-focused alternative asset manager with more than two decades of experience. Its investment activities have primarily targeted mid-market companies across sectors such as education, financial services, consumer businesses, digital technology, energy and environment.
The IPO therefore gives investors exposure to the growth of India's alternative-investment industry rather than to one specific operating sector.
Gaja Alternative Asset Management IPO Details
| Particular | Details |
|---|---|
| IPO Type | Mainboard IPO |
| Issue Size | ₹550 Crore |
| Fresh Issue | ₹450 Crore |
| Offer for Sale | ₹100 Crore |
| Price Band | ₹152 – ₹160 |
| Lot Size | 93 Shares |
| Minimum Investment | ₹14,880 |
| IPO Open Date | August 19, 2026 |
| IPO Close Date | August 21, 2026 |
| Allotment Date | August 24, 2026 |
| Refund Initiation | August 25, 2026 |
| Share Credit | August 25, 2026 |
| Listing Date | August 26, 2026 |
| Listing | BSE & NSE |
| Lead Manager | JM Financial |
| Registrar | MUFG Intime India |
The issue comprises approximately 2.81 crore fresh shares worth ₹450 crore and about 0.63 crore shares worth ₹100 crore through OFS.
Gaja Alternative Asset Management IPO GMP Today
Grey-market sentiment remains positive on Day 2.
The latest available GMP tracker on August 20, 2026 reports a premium of approximately:
₹25 per share.
At the upper issue price of ₹160:
₹160 + ₹25 = ₹185
This implies an unofficial premium of approximately 15.63%.
| GMP Particular | Current Status |
|---|---|
| Upper Issue Price | ₹160 |
| Latest GMP | ₹25 |
| Indicative Price | ₹185 |
| Indicative Premium | ~15.63% |
| GMP Sentiment | Positive |
The GMP reportedly touched ₹30 on August 19 before moderating to around ₹25.
GMP is unofficial and unregulated, so the actual listing price can be substantially different.
Subscription Demand After Day 1
The IPO received a moderate response on its first bidding day.
According to the latest category-wise Day 1 data:
| Investor Category | Subscription |
|---|---|
| QIB | 0.09× |
| NII | 1.06× |
| Retail | 1.20× |
| Overall | 0.86× |
Retail investors and NIIs therefore fully subscribed their respective portions on the first day, while QIB participation remained relatively low.
Institutional investors frequently place significant bids later in an IPO, making the final-day QIB number particularly important.
What Does Gaja Alternative Asset Management Do?
Gaja is an alternative asset-management company.
Instead of managing conventional mutual funds for millions of retail investors, alternative asset managers typically raise capital from sophisticated investors and deploy that money into specialised investment opportunities.
Gaja manages and advises India-focused funds, including Category I and Category II Alternative Investment Funds as well as offshore funds investing in India.
Its model can be simplified as:
raise investor capital → identify businesses → invest → help companies grow → eventually exit investments → generate returns.
If successful, Gaja earns fees while investors participate in the returns generated by the funds.
Mid-Market Investing Is Gaja's Core Strategy
Gaja's investment strategy has historically focused on India's mid-market segment.
These businesses may already have established products and customers but still require capital and strategic assistance to reach their next stage.
The opportunity can look like:
growing private company → Gaja investment → business expansion → valuation growth → eventual exit.
This provides exposure to companies before they necessarily reach the public markets.
Gaja has invested across sectors including education, financial services, consumer, digital technology, energy and environmental businesses.
Fund Performance Is the Heart of the Business
For an asset manager, investment performance ultimately determines reputation.
If funds consistently generate attractive returns:
existing investors may reinvest + new investors may join + larger funds can be raised.
Gaja's historical funds have reportedly generated an average 3.3× multiple on invested capital (MOIC).
MOIC essentially measures how much value has been generated relative to the capital invested.
For example:
₹100 invested → ₹330 value = 3.3× MOIC.
Past performance does not guarantee similar future returns, but a long-term track record can materially influence fundraising ability.
Investor Relationships Are a Major Competitive Advantage
Alternative asset managers cannot simply advertise a new fund and expect billions of rupees to arrive.
Institutional investors evaluate:
track record + team + investment process + governance + realised returns + risk management.
Gaja has developed relationships with investors across more than 20 countries.
These relationships can become particularly valuable when the company launches new funds.
A successful existing investor relationship can potentially translate into commitments to subsequent funds.
Management Fees Can Provide Recurring Revenue
One attractive characteristic of asset management is the potential for recurring fee income.
Once investors commit money to a fund, the manager can generally earn management fees according to the fund structure.
That means Gaja does not need to sell a physical product every month to generate revenue.
Instead:
larger funds → larger fee-paying asset base → higher potential recurring revenue.
This makes growth in fee-paying assets an important metric after listing.
Performance Fees Can Create Additional Upside
Alternative asset managers may also earn performance-linked income when investments generate returns above specified thresholds.
This can create significant earnings upside during successful exit periods.
But it also introduces volatility.
Management fees may be relatively predictable.
Performance-linked income can be much less predictable.
Therefore, investors should separate:
recurring management-fee income
from:
performance-related income.
A high-quality listed asset manager ideally builds a growing recurring fee base rather than depending excessively on occasional investment exits.
₹450 Crore Fresh Issue Is Significant
Of the total ₹550 crore IPO:
₹450 crore is fresh issue
and:
₹100 crore is OFS.
That means approximately:
81.8% of the total issue is fresh capital.
This is an important structural positive because most of the money being raised goes into the company rather than entirely to selling shareholders.
Where Will the IPO Money Go?
Gaja plans to deploy fresh proceeds toward a combination of:
existing and future investment commitments + debt repayment/prepayment + general corporate purposes.
This is particularly interesting for an asset-management company.
Rather than spending the majority of IPO proceeds on factories or working capital, Gaja can use capital to support investments alongside the funds it manages.
This can align the company financially with investors in its funds.
Co-Investment Can Align Interests
Alternative asset managers often invest some of their own balance-sheet capital alongside fund investors.
This creates the principle of:
manager money + investor money → same investment exposure.
The advantage is alignment.
If Gaja itself has capital at risk, its economic interests can be more closely aligned with those of fund investors.
However, using balance-sheet capital for investments also exposes shareholders directly to investment-market risk.
Gaja's Business Is Capital-Light at the Operating Level
Compared with manufacturing companies, Gaja does not require large factories or inventory.
Its primary resources are:
- Investment professionals
- Research capabilities
- Fund-management infrastructure
- Investor relationships
- Brand and track record
This can potentially produce attractive returns on operating capital as the business scales.
The incremental cost of managing a larger fund may not rise at the same rate as assets under management.
That creates operating leverage.
But Investment Talent Is Critical
The asset-management business is highly dependent on people.
An experienced investment professional can be responsible for:
finding deals + evaluating companies + negotiating transactions + supporting portfolio businesses + managing exits.
If important senior investment professionals leave, replacing their experience and relationships can be difficult.
Talent retention is therefore a major business risk.
Fundraising Is Not Guaranteed
Strong historical performance helps, but Gaja still needs investors to commit money to future funds.
Global institutions can change their allocations because of:
- Interest rates
- Economic conditions
- Currency movements
- India's valuation environment
- Performance of earlier funds
- Global risk appetite
If fundraising slows, Gaja's future fee-paying asset base could grow more slowly.
That makes new fund closes an important post-listing indicator.
Exit Conditions Matter
Private-equity investments generally need an eventual exit.
Possible routes include:
IPO + strategic sale + secondary transaction + promoter buyback.
If capital markets are weak or buyers become cautious, Gaja may need to hold portfolio investments longer.
That can delay:
realised returns + carried interest + distributions to fund investors.
The business therefore has some exposure to capital-market cycles even though its portfolio companies are privately held.
Regulations Are an Important Risk
Alternative Investment Funds operate within a regulated framework.
Changes to:
- SEBI regulations
- Tax treatment
- Fund structures
- Foreign-investor rules
- Investment restrictions
can influence the economics of the business.
The company's earnings are therefore exposed not only to investment performance but also to changes in India's financial regulatory environment.
The Promoter Stake Will Remain Meaningful
The promoter and promoter group held approximately 71.03% before the IPO, with their stake expected to fall to around 54.23% after the issue.
This means promoters are expected to retain majority ownership after listing.
For investors, that maintains meaningful promoter alignment while introducing greater public ownership.
Key Strengths
Gaja brings several important positives to the IPO.
It has more than two decades of alternative-investment experience and an established record of managing India-focused funds.
Its historical funds have reportedly generated an average MOIC of around 3.3×, providing a meaningful track record for future fundraising.
The company also benefits from relationships with investors across more than 20 countries and exposure to multiple sectors rather than relying on one industry.
Finally, approximately ₹450 crore of the ₹550 crore IPO is fresh capital, giving the company meaningful additional balance-sheet resources.
Major Risks
The biggest risk is investment performance.
If future funds generate weak returns, fundraising and fee growth could suffer.
Other important risks include:
Fundraising risk – investors may reduce commitments to future funds.
Key-person risk – experienced investment professionals are central to the business.
Exit risk – weak capital markets can delay profitable exits.
Performance-fee volatility – some earnings can vary significantly between periods.
Regulatory risk – changes to AIF or investment rules can affect the business.
Valuation risk – private-company investments do not have continuously observable market prices.
Competition – Gaja competes with Indian and global private-equity and alternative-asset managers for both capital and attractive deals.
What Investors Should Track After Listing
| Metric | Why It Matters |
|---|---|
| Assets Under Management | Business scale |
| Fee-Paying AUM | Recurring revenue |
| Management Fees | Earnings visibility |
| Performance Fees | Investment success |
| New Fundraising | Future growth |
| MOIC | Historical returns |
| IRR | Fund performance |
| Investment Exits | Realised gains |
| Investor Retention | Fundraising strength |
| New Investors | Global expansion |
| Employee Retention | Key-person risk |
| ROE / RoNW | Shareholder returns |
For Gaja, one of the most important equations after listing will be:
strong fund returns → repeat investors → larger funds → higher fee-paying AUM → growing recurring management fees.
Final View on Gaja Alternative Asset Management IPO
The Gaja Alternative Asset Management IPO is open from August 19 to August 21, 2026, with a price band of ₹152–₹160 per share. The ₹550 crore mainboard IPO consists of a ₹450 crore fresh issue and ₹100 crore OFS, while listing is tentatively scheduled for August 26.
Day 1 ended with approximately 0.86× overall subscription, led by retail at 1.20× and NII at 1.06×, while QIB subscription stood at 0.09×.
Grey-market sentiment is currently positive. The latest reported GMP on August 20 is around ₹25, implying an unofficial premium of approximately 15.63% over the ₹160 upper price.
Fundamentally, Gaja is different from most IPO candidates. Its long-term value will not be determined by manufacturing capacity, inventory or store expansion.
Loading comments...