
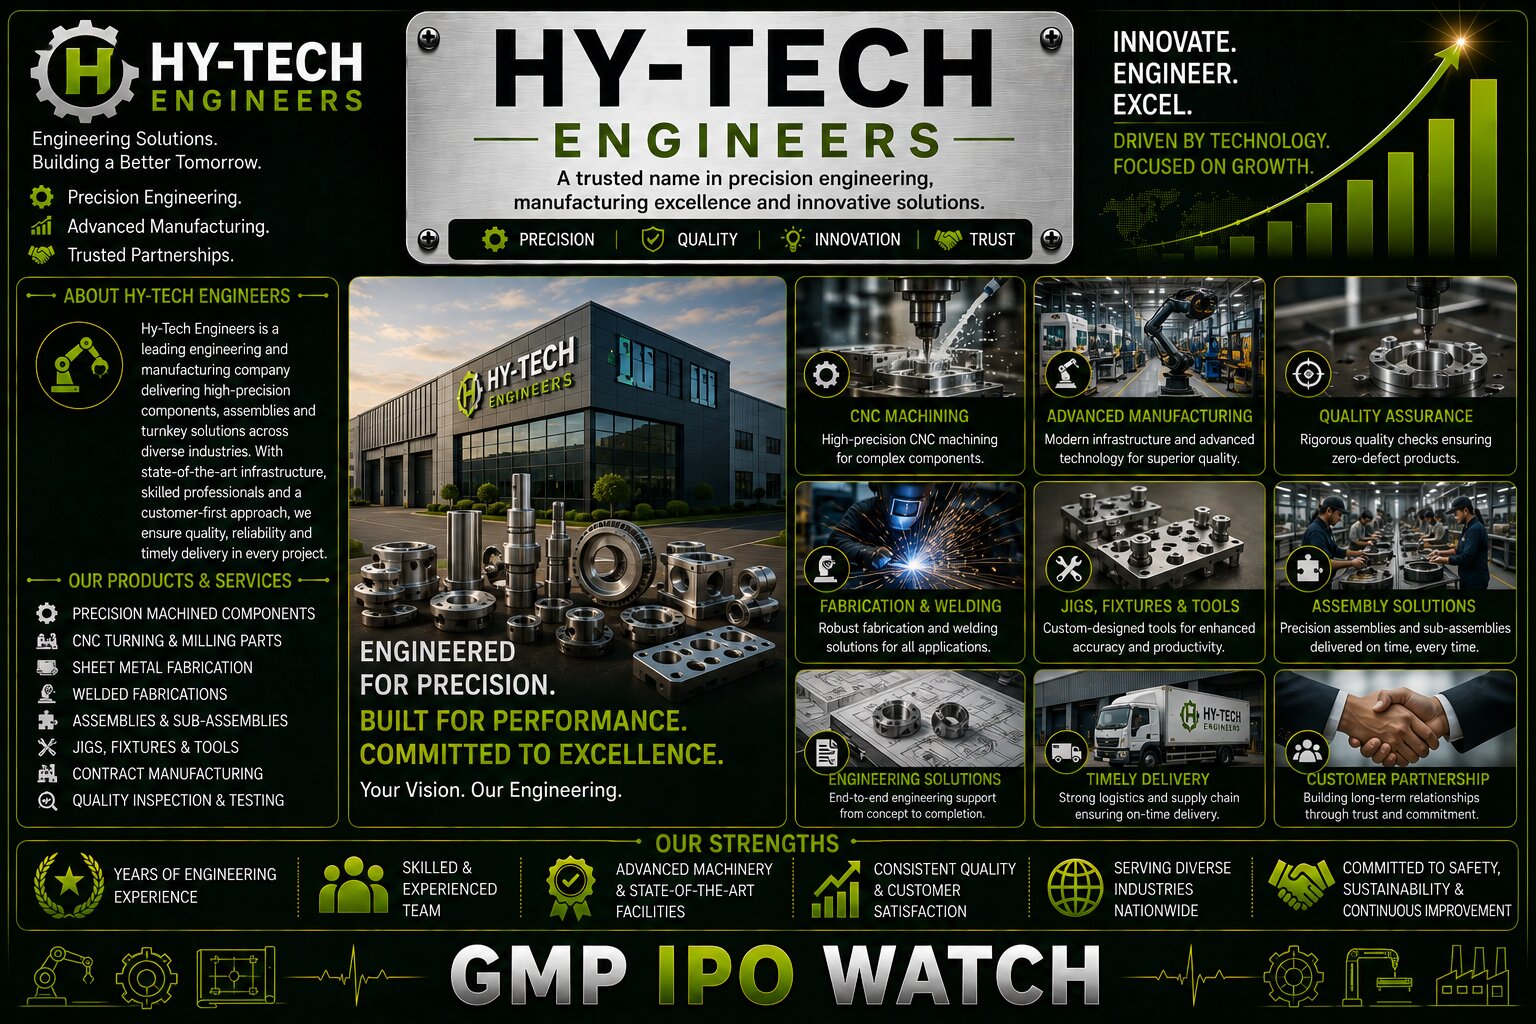
Hy-Tech Engineers IPO 2026 – Hydraulic Fittings Manufacturer Enters the Mainboard Market
Hy-Tech Engineers Limited has opened its IPO for subscription today, August 24, 2026, with bidding scheduled to continue until August 27.
The company operates in a specialised engineering segment, designing and manufacturing hydraulic fittings used across industrial machinery and equipment. Its products find applications in construction equipment, automobiles, agricultural machinery, injection moulding machines and hydraulic systems.
The IPO arrives with an interesting combination of established manufacturing operations, improving financial performance and planned capacity expansion.
Hy-Tech Engineers IPO Details
| Particular | Details |
|---|---|
| Company | Hy-Tech Engineers Limited |
| IPO Type | Mainboard IPO |
| Issue Type | Book Built Issue |
| Total Issue Size | ₹135.73 Crore |
| Fresh Issue | ₹60 Crore |
| Offer for Sale | ₹75.73 Crore |
| Total Shares Offered | 2.56 Crore Shares |
| Price Band | ₹50 – ₹53 |
| Face Value | ₹5 |
| Lot Size | 283 Shares |
| Minimum Investment | ₹14,999 at ₹53 |
| IPO Open Date | August 24, 2026 |
| IPO Close Date | August 27, 2026 |
| Allotment Date | August 28, 2026 |
| Demat Credit | August 31, 2026 |
| Listing Date | September 1, 2026 |
| Listing | BSE & NSE |
| Lead Manager | New Berry Capitals |
| Registrar | Bigshare Services |
The official IPO structure consists of a ₹60 crore fresh issue and an OFS of approximately 1.43 crore shares, worth about ₹75.73 crore at the upper price band.
Hy-Tech Engineers IPO GMP Today
Hy-Tech Engineers entered its opening day with strong activity in the unofficial grey market.
Current reports indicate a GMP suggesting roughly 47% potential premium over the issue price.
| GMP Particular | Current Position |
|---|---|
| Upper Issue Price | ₹53 |
| GMP Trend | Strong |
| Indicative Premium | ~47% |
| IPO Status | Open |
| Subscription Day | Day 1 |
The grey-market premium is unofficial and can move sharply before listing. It should not be considered a guaranteed listing price or return.
What Does Hy-Tech Engineers Do?
Hy-Tech Engineers manufactures hydraulic fittings used to connect different components within hydraulic systems.
Its product portfolio includes:
DIN-metric fittings + JIC flared fittings + flareless fittings + O-Ring Face Seal fittings + conversion fittings + customised hydraulic fittings.
As of March 31, 2026, the company had developed more than 11,000 SKUs.
That large product portfolio allows Hy-Tech to address different equipment designs, pressure requirements and customer specifications.
Where Are Hy-Tech Products Used?
Hydraulic systems are widely used wherever machinery needs to generate or control significant mechanical force.
Hy-Tech's products cater to industries including:
| End-Use Industry | Application Opportunity |
|---|---|
| Construction Machinery | Excavators & heavy equipment |
| Automotive | Vehicle hydraulic systems |
| Agricultural Machinery | Tractors & farm equipment |
| Injection Moulding | Industrial machinery |
| Hydraulic Equipment | Pumps, cylinders & systems |
| Industrial Machinery | Various engineering applications |
This provides Hy-Tech with exposure to several industrial sectors rather than a single end market.
More Than 11,000 SKUs Create a Broad Product Portfolio
One interesting feature of Hy-Tech's business is the sheer number of products it manufactures.
More than 11,000 SKUs means customers can source fittings across different:
sizes + standards + configurations + applications + specifications.
For an engineering component supplier, this breadth can be valuable.
Industrial customers often prefer suppliers capable of delivering multiple components instead of maintaining relationships with many smaller vendors.
Customised Fittings Add Another Capability
Hy-Tech also manufactures products according to customer specifications.
This matters because hydraulic systems can vary substantially between machines.
A construction-equipment manufacturer may require different fitting specifications from an agricultural-equipment or injection-moulding-machine company.
Custom engineering can therefore create stronger customer relationships than simply selling standard catalogue products.
FY2026 Revenue Shows Continued Growth
Hy-Tech reported improving financial performance in FY2026.
| Financial Metric | FY2025 | FY2026 |
|---|---|---|
| Revenue | ₹166.71 Cr | ₹193.44 Cr |
| Profit After Tax | ₹19.62 Cr | ₹22.59 Cr |
| Revenue Growth | — | ~16% |
| PAT Growth | — | ~15% |
Revenue increased by approximately 16%, while PAT rose by around 15% during FY2026.
This shows that the company continued expanding both its top line and bottom line before entering the public market.
₹29.97 Crore Will Fund Manufacturing Expansion
A major portion of the fresh IPO proceeds will be used for capital expenditure.
Hy-Tech plans to deploy approximately ₹29.97 crore toward machinery and equipment for expansion at its:
Kavathe Unit + Shirwal Unit + Pithampur Unit-I.
Use of Fresh IPO Proceeds
| Purpose | Amount |
|---|---|
| Machinery & Equipment Capex | ₹29.97 Cr |
| Debt Repayment / Prepayment | ₹16.00 Cr |
| General Corporate Purposes | Balance |
| Total Fresh Issue | ₹60.00 Cr |
This means roughly half of the fresh issue is directly connected with expanding manufacturing capabilities.
Capacity Expansion Is Central to the IPO Story
The capital-expenditure plan gives the IPO a clear growth component.
The intended progression is:
new machinery → higher manufacturing capability → greater order execution → increased sales potential.
However, adding capacity creates value only when utilisation improves.
After listing, investors should therefore watch whether the additional machinery translates into proportionately higher revenue and profits.
₹16 Crore Will Be Used for Debt Reduction
Another ₹16 crore of fresh proceeds is earmarked for repayment or prepayment of certain outstanding borrowings.
Debt reduction can potentially benefit Hy-Tech through:
lower interest costs + stronger balance sheet + improved cash flow + additional financial flexibility.
Because the company is simultaneously expanding manufacturing capacity, maintaining a healthy balance sheet could become increasingly important.
IPO Is Slightly More OFS Than Fresh Issue
The ₹135.73 crore issue has the following structure:
| IPO Component | Amount | Approx. Share |
|---|---|---|
| Fresh Issue | ₹60.00 Cr | 44.2% |
| Offer for Sale | ₹75.73 Cr | 55.8% |
| Total IPO | ₹135.73 Cr | 100% |
Promoter Hemant Tukaram Mondkar and Surekha Mondkar are selling shares through the OFS.
The OFS proceeds go to the selling shareholders rather than the company.
The ₹60 crore fresh component is the portion that will strengthen Hy-Tech's own balance sheet and fund expansion.
IPO Values Hy-Tech at Around ₹503 Crore
At the upper price band of ₹53 per share, Hy-Tech Engineers is seeking a market capitalisation of approximately ₹502.7 crore.
That makes the valuation especially interesting when compared with FY2026 PAT of ₹22.59 crore.
The simple market-cap-to-FY2026-PAT calculation works out at roughly:
₹502.7 crore ÷ ₹22.59 crore = about 22.3× earnings.
Investors should still use the RHP's diluted EPS and post-issue share count when making the formal P/E comparison.
Hydraulic Equipment Demand Is Linked to Industrial Growth
Hy-Tech's growth is indirectly connected with India's broader industrial and manufacturing cycle.
Hydraulic fittings are required across equipment used in:
construction + agriculture + automobiles + manufacturing + material handling + industrial machinery.
When these industries expand production or purchase additional machinery, demand for hydraulic components can increase.
This gives Hy-Tech exposure to India's long-term manufacturing and infrastructure growth.
Replacement Demand Can Also Support the Business
Industrial components do not generate demand only when new machines are manufactured.
Hydraulic systems operate under pressure and components can eventually require replacement.
This creates an aftermarket opportunity.
A supplier with a broad product portfolio can potentially benefit from both:
OEM demand + replacement demand.
That can make the business less dependent solely on new equipment production.
Customer Concentration Is an Important Risk
Hy-Tech's IPO disclosures identify customer concentration as an important risk.
For specialised component manufacturers, large OEM relationships can generate consistent volumes.
However, they also create dependency.
If a major customer:
reduces orders + changes supplier + negotiates lower prices + experiences weaker demand,
Hy-Tech's revenue and margins could be affected.
Expanding the customer base therefore remains important for reducing business concentration.
Receivables Need Close Attention
Another important issue is working-capital management.
Current IPO analysis highlights that a meaningful amount of Hy-Tech's capital remains tied up in customer payments.
This matters because reported profit does not automatically mean cash has been collected.
The business cycle can look like:
purchase raw materials → manufacture fittings → supply customer → invoice customer → wait for payment.
Longer collection periods increase the amount of capital required to support growth.
Operating Cash Flow Matters Alongside PAT
Because of the receivable issue, investors should avoid looking only at revenue and PAT.
A healthier growth pattern would be:
revenue growth + PAT growth + timely collections + positive operating cash flow.
If profits grow while receivables increase much faster, additional cash can remain locked in working capital.
For Hy-Tech, cash conversion will therefore be an important post-listing metric.
Foreign Exchange Exposure Is Another Risk
Current IPO information also identifies foreign-exchange exposure among the company's risks.
Currency movements can affect both revenue and costs depending on the company's export, import and sourcing mix.
The actual impact depends on:
currency exposure + customer contracts + imported materials + hedging arrangements.
Large movements in the rupee can therefore affect profitability.
Manufacturing Expansion Creates Opportunity and Execution Risk
Hy-Tech plans to install additional machinery across multiple manufacturing units.
This can increase capacity, but expansion also needs to be executed properly.
The company must manage:
equipment installation + commissioning + employee training + quality control + utilisation + customer orders.
If additional capacity remains underutilised, returns on the IPO-funded capital could be weaker than expected.
Key Strengths of Hy-Tech Engineers
The company enters the IPO with several notable positives.
Its product portfolio exceeds 11,000 SKUs, providing significant breadth across hydraulic-fitting categories.
FY2026 revenue increased to approximately ₹193.44 crore, while PAT reached ₹22.59 crore.
The IPO also provides fresh capital for tangible business purposes, including ₹29.97 crore of manufacturing capex and ₹16 crore of debt reduction.
Other positives include customised engineering capabilities, exposure to several industrial end markets and potential demand from India's growing manufacturing and infrastructure sectors.
Major Risks
Important areas investors should monitor include customer concentration, working-capital pressure, delayed receivable collections, raw-material costs, foreign-exchange movements and dependence on industrial demand.
The company must also successfully utilise its planned new machinery.
Another consideration is that approximately 56% of the IPO is OFS, meaning that portion of the proceeds will go to selling shareholders rather than funding Hy-Tech's operations.
What Investors Should Track After Listing
| Metric | Why It Matters |
|---|---|
| Revenue Growth | Business expansion |
| PAT Growth | Earnings momentum |
| EBITDA Margin | Operating profitability |
| Capacity Utilisation | Capex effectiveness |
| Customer Concentration | Revenue risk |
| Receivable Days | Collection efficiency |
| Operating Cash Flow | Earnings quality |
| Export Revenue | International growth |
| Debt | IPO deleveraging |
| Finance Cost | Debt repayment benefit |
| New Customer Additions | Diversification |
| ROCE | Capital efficiency |
For Hy-Tech, one of the most important post-listing indicators will be whether its ₹29.97 crore expansion programme generates higher revenue without creating disproportionate working-capital requirements.
Final View on Hy-Tech Engineers IPO 2026
The Hy-Tech Engineers IPO opened today, August 24, and closes on August 27, 2026. The ₹135.73 crore mainboard issue has a price band of ₹50–₹53, a lot size of 283 shares and tentative listing scheduled for September 1 on BSE and NSE.
The issue consists of a ₹60 crore fresh issue and approximately ₹75.73 crore OFS. Of the fresh proceeds, ₹29.97 crore is earmarked for machinery and equipment at three manufacturing units, while ₹16 crore will be used for debt repayment or prepayment.
Financially, the company reported FY2026 revenue of approximately ₹193.44 crore compared with ₹166.71 crore in FY2025, while PAT increased from ₹19.62 crore to ₹22.59 crore.
The business itself has an established industrial proposition: more than 11,000 hydraulic-fitting SKUs serving applications across construction equipment, automobiles, agricultural machinery, injection moulding and other hydraulic systems.
Loading comments...