
Symbiotec Pharmalab IPO 2026 – Niche API Manufacturer Enters the Public Market
Symbiotec Pharmalab Limited has opened its mainboard IPO today, August 24, 2026, with bidding continuing until August 27.
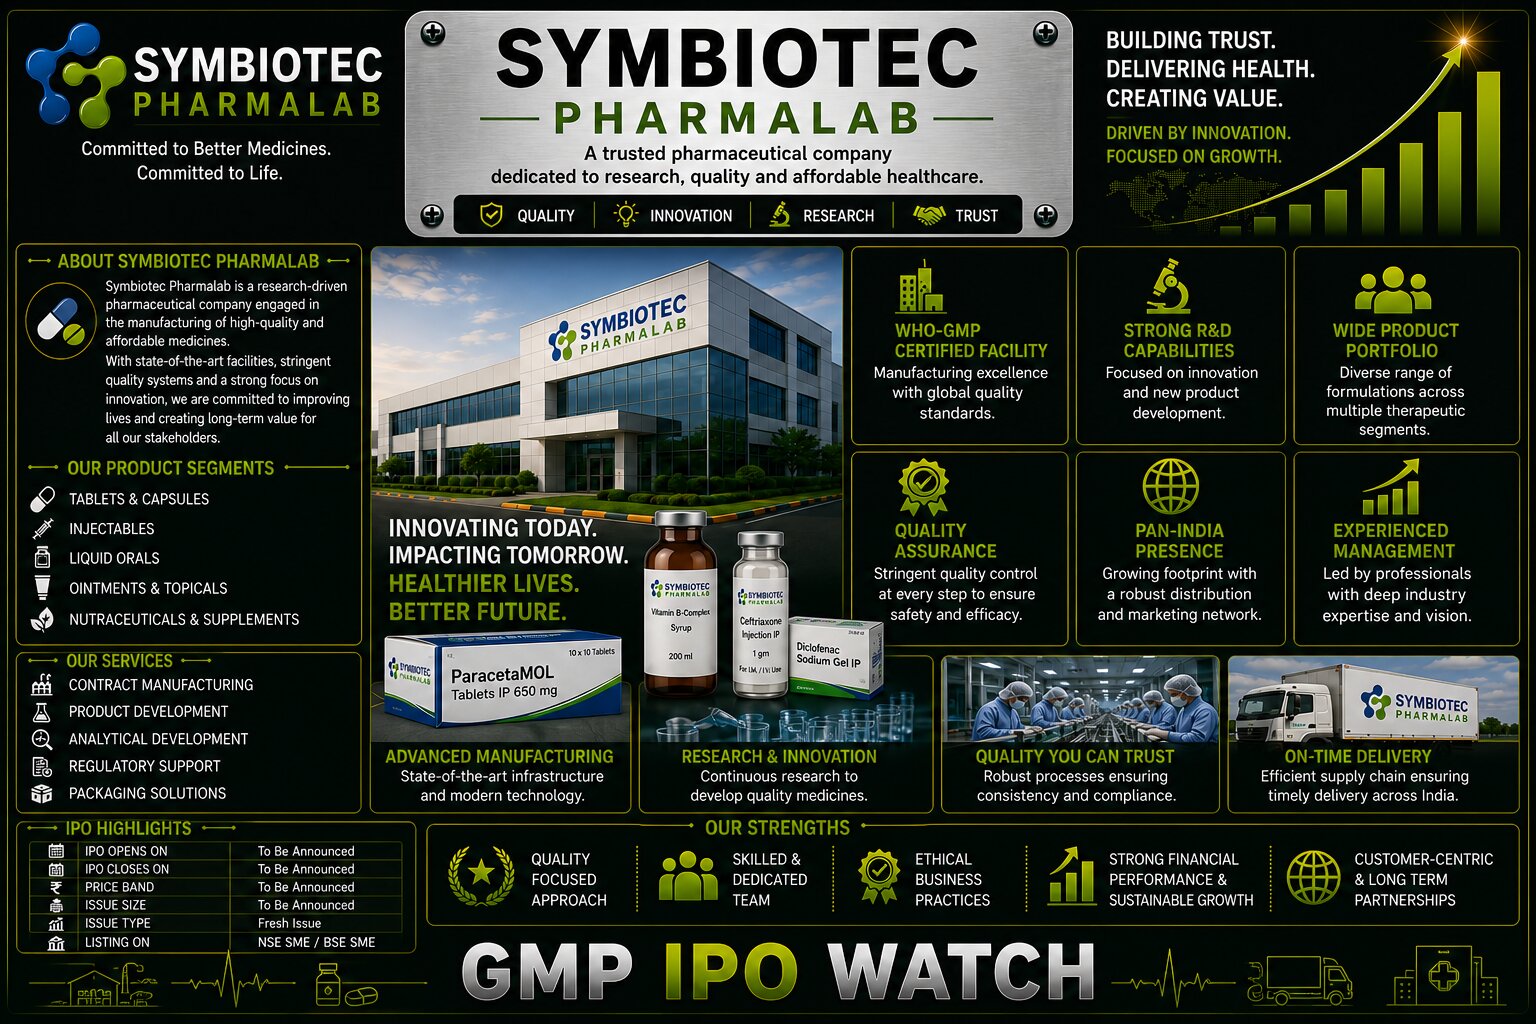
The company is a research-driven pharmaceutical manufacturer specialising in Active Pharmaceutical Ingredients (APIs), nutritional ingredients and specialty products. Its particularly strong position in steroid APIs makes this IPO different from a conventional formulation-focused pharmaceutical offering.
The ₹1,757 crore issue comes at a price band of ₹938–₹988 per share, while current grey-market activity indicates strong pre-listing sentiment.
Symbiotec Pharmalab IPO Details
| Particular | Details |
|---|---|
| Company | Symbiotec Pharmalab Limited |
| IPO Type | Mainboard IPO |
| Issue Type | Book Built |
| Total Issue Size | ₹1,757 Crore |
| Fresh Issue | ₹150 Crore |
| Offer for Sale | ₹1,607 Crore |
| Price Band | ₹938 – ₹988 |
| Face Value | ₹10 |
| Lot Size | 15 Shares |
| Minimum Retail Investment | ₹14,820 |
| IPO Open Date | August 24, 2026 |
| IPO Close Date | August 27, 2026 |
| Allotment Date | August 28, 2026 |
| Refund / Demat | August 31, 2026 |
| Listing Date | September 1, 2026 |
| Listing | BSE & NSE |
| Registrar | MUFG Intime India |
The IPO comprises approximately 1.78 crore shares in total. Official offer information confirms that ₹112.50 crore of the fresh proceeds is proposed for repayment or prepayment of certain borrowings.
Symbiotec Pharmalab IPO GMP Today
Symbiotec is attracting considerable grey-market attention on its opening day.
Recent reports today put GMP in a range of roughly ₹345 to ₹409+ per share, depending on the tracker and time of observation. One report at 11:20 AM showed GMP at ₹409, implying an estimated price of approximately ₹1,397 against the ₹988 upper issue price.
| GMP Particular | Current Position |
|---|---|
| Upper IPO Price | ₹988 |
| Reported GMP Range | ~₹345 – ₹409 |
| Indicative Price at ₹409 GMP | ₹1,397 |
| Indicative Premium | ~41.4% |
| IPO Status | Open – Day 1 |
GMP is unofficial and changes throughout the day. It should therefore be viewed as a sentiment indicator rather than a guaranteed listing return.
Day 1 Subscription Has Started
Early subscription numbers show bidding gradually building.
By around 11:54 AM today, the IPO was reported subscribed approximately 0.25 times overall. Retail participation was around 0.37 times, while the NII portion was around 0.31 times.
These are only intraday Day 1 figures and will change as bidding progresses through August 27.
What Does Symbiotec Pharmalab Do?
Symbiotec operates in the pharmaceutical manufacturing industry but focuses primarily on specialised ingredients rather than selling finished medicines directly to consumers.
Its portfolio covers:
steroid APIs + other niche APIs + nutritional ingredients + specialty pharmaceutical products.
APIs are the biologically active components used in pharmaceutical formulations.
In simple terms:
Symbiotec manufactures the critical ingredients → pharmaceutical companies use them to manufacture finished medicines.
This makes Symbiotec primarily a B2B pharmaceutical supplier.
Steroid APIs Are a Key Competitive Strength
Symbiotec has built a significant position in steroid APIs.
Steroid APIs are used across several therapeutic applications and require specialised manufacturing capabilities, regulatory compliance and technical expertise.
This creates higher barriers to entry than many commoditised pharmaceutical products.
Customers typically evaluate suppliers based on:
quality + regulatory compliance + manufacturing reliability + technical capability + supply consistency.
Once a pharmaceutical company qualifies an API supplier, changing that supplier can involve additional regulatory and operational work.
That can help established manufacturers build relatively sticky customer relationships.
International Markets Generate More Than Two-Thirds of Revenue
One of the most important characteristics of Symbiotec is its international exposure.
More than two-thirds of company revenue comes from overseas markets, while Europe alone contributes approximately 30% of revenue.
| Geographic Indicator | Revenue Exposure |
|---|---|
| International Markets | 66%+ |
| Europe | ~30% |
| India | Less than one-third |
This demonstrates that Symbiotec is already an export-oriented pharmaceutical manufacturer rather than a business relying predominantly on the Indian market.
Export Exposure Can Be a Major Growth Driver
Pharmaceutical APIs have a global addressable market.
If Symbiotec successfully expands relationships with overseas pharmaceutical companies, it can grow without depending entirely on India's domestic pharmaceutical demand.
International operations can also provide:
customer diversification + larger addressable market + hard-currency revenue + access to regulated pharmaceutical markets.
However, export growth brings additional requirements around regulatory compliance and manufacturing quality.
Europe Is Particularly Important
Europe accounting for approximately 30% of revenue gives Symbiotec meaningful exposure to developed pharmaceutical markets.
Supplying regulated markets can create an advantage because regulatory approvals and customer qualification can make it harder for new competitors to enter quickly.
At the same time, dependence on Europe creates risks involving:
regulatory changes + customer demand + foreign exchange + geopolitical conditions.
Geographic diversification outside its largest markets will therefore remain important.
Top Five Products Generate 63% of Revenue
One of the most important risks disclosed around the business is product concentration.
Symbiotec's top five products account for approximately 63% of revenue.
That means a relatively small number of products generate the majority of sales.
| Business Concentration | Approx. Exposure |
|---|---|
| Top 5 Products | ~63% of Revenue |
| International Markets | 66%+ of Revenue |
| Europe | ~30% of Revenue |
Product concentration can be profitable when the company holds strong market positions.
But it also creates risk.
If demand or pricing for one major product weakens materially, the impact on overall revenue could be significant.
New Products Could Reduce Concentration
A key long-term opportunity is therefore expanding the product portfolio.
The ideal progression is:
strong steroid API base → additional niche APIs → nutritional ingredients → specialty products → broader revenue mix.
If newer products become meaningful contributors, dependence on the current top five products can gradually decline.
That would make earnings more diversified.
₹150 Crore Fresh Issue vs ₹1,607 Crore OFS
The structure of the Symbiotec IPO deserves particular attention.
| IPO Component | Amount | Approx. Share |
|---|---|---|
| Fresh Issue | ₹150 Cr | ~8.5% |
| Offer for Sale | ₹1,607 Cr | ~91.5% |
| Total Issue | ₹1,757 Cr | 100% |
The vast majority of the IPO is an Offer for Sale.
This means only around 8.5% of the total IPO amount represents new capital going directly into Symbiotec.
Approximately 91.5% relates to shares being sold by existing shareholders.
₹112.50 Crore Will Be Used for Debt Repayment
Of the ₹150 crore fresh issue, Symbiotec plans to use approximately ₹112.50 crore for prepayment or repayment of certain outstanding borrowings.
Use of Fresh Issue Proceeds
| Purpose | Amount |
|---|---|
| Debt Repayment / Prepayment | ₹112.50 Cr |
| General Corporate Purposes | Balance |
| Total Fresh Issue | ₹150 Cr |
That means approximately 75% of fresh IPO proceeds are earmarked for debt reduction.
Why Debt Reduction Matters
API manufacturing requires substantial capital.
A pharmaceutical manufacturer needs money for:
raw materials + manufacturing equipment + quality systems + laboratories + inventory + regulatory compliance + receivables.
Reducing debt could lower interest costs and strengthen the company's balance sheet.
The potential benefit is:
lower borrowings → lower finance costs → stronger cash flow → greater financial flexibility.
The actual impact will become clearer in post-listing financial results.
Anchor Investors Put in ₹526.20 Crore
Symbiotec received substantial institutional participation before the public issue opened.
The company raised approximately ₹526.20 crore from anchor investors ahead of the IPO.
Reported anchor participants included institutional investors such as Citi Group and Singularity.
This indicates meaningful institutional interest before the public subscription began.
However, anchor participation by itself does not guarantee post-listing performance.
Promoter Holding Will Decline After the IPO
Before the issue, promoters held approximately 36.41% of Symbiotec.
Current IPO analysis indicates promoter-group ownership is expected to decline to roughly 33.3% after the IPO.
The decline is partly related to the substantial OFS component.
Even after listing, promoters will remain significant shareholders.
Pharmaceutical API Manufacturing Has High Entry Barriers
API manufacturing is not simply a matter of building a factory.
Manufacturers need:
technical know-how + regulatory approvals + quality-control systems + validated manufacturing processes + customer qualification + environmental compliance.
For specialised products, these requirements can create meaningful entry barriers.
This is one reason Symbiotec's established positions in niche API categories are important.
Customer Qualification Can Create Sticky Relationships
When a pharmaceutical company selects an API supplier, it typically performs extensive quality and regulatory checks.
Changing the API supplier may require additional validation and regulatory procedures.
This can make approved supplier relationships valuable.
The ideal business cycle for Symbiotec is:
customer qualification → commercial supply → consistent quality → repeat orders → long-term relationship.
Maintaining high manufacturing standards is therefore critical.
Regulatory Compliance Is Also a Major Risk
The same regulation that creates entry barriers can become a significant risk.
Pharmaceutical manufacturing facilities can face inspections by regulatory authorities.
Any serious quality or compliance issue could potentially result in:
- Warning letters
- Product restrictions
- Import alerts
- Production interruptions
- Customer losses
- Remediation expenses
For an export-heavy API manufacturer, regulatory compliance must therefore remain one of the highest priorities.
Currency Movements Can Affect Earnings
Because more than two-thirds of Symbiotec's revenue comes internationally, foreign-exchange movements can influence reported earnings.
A weaker rupee can sometimes benefit export revenue when converted into rupees.
A stronger rupee can create the opposite effect.
However, the actual impact also depends on:
imported raw materials + hedging policies + customer contracts + currency mix.
Investors should therefore watch forex gains and losses alongside export growth.
Research and Development Is Important for Future Growth
Specialised pharmaceutical manufacturers need to continuously expand their product portfolios.
For Symbiotec, R&D can help develop:
new APIs + improved manufacturing processes + specialty products + higher-value molecules.
This matters particularly because the company's current revenue remains concentrated among a relatively small number of major products.
Successful new-product development can create the next phase of growth while reducing concentration risk.
Strong GMP Creates High Listing Expectations
A reported GMP around ₹345–₹409 represents substantial optimism around the IPO.
But strong GMP creates its own risk.
When expectations become very high:
high GMP → high listing expectations → greater sensitivity to market sentiment.
Even fundamentally strong companies can experience volatility when unofficial expectations become excessive.
Investors should therefore separate the underlying business from short-term grey-market activity.
Key Strengths of Symbiotec Pharmalab
Symbiotec enters the IPO with several notable strengths.
Niche API positioning: The company specialises in technically demanding pharmaceutical ingredients.
International business: More than two-thirds of revenue comes from overseas markets.
European presence: Europe contributes around 30% of revenue.
Established market positions: The company has leading positions across several product lines.
High entry barriers: Specialised API manufacturing requires technical expertise, regulatory compliance and customer qualification.
Debt reduction: ₹112.50 crore of fresh proceeds is earmarked for repayment or prepayment of borrowings.
Institutional participation: The company raised approximately ₹526.20 crore through the anchor book.
Major Risks
Investors should also monitor:
- Top five products contribute around 63% of revenue
- More than two-thirds of revenue comes from international markets
- Europe contributes around 30% of revenue
- Regulatory and compliance risk
- Raw-material price volatility
- Foreign-exchange fluctuations
- Customer concentration
- Pharmaceutical pricing pressure
- Environmental compliance
- R&D execution risk
- Approximately 91.5% of the IPO is OFS
- Strong GMP may create elevated listing expectations
The 63% revenue concentration in the top five products is particularly important because changes in demand for a small number of APIs could materially affect financial performance.
What Investors Should Track After Listing
| Metric | Why It Matters |
|---|---|
| Revenue Growth | Business expansion |
| Export Revenue | Global demand |
| EBITDA Margin | Operating profitability |
| PAT Growth | Earnings momentum |
| Top 5 Product Share | Concentration risk |
| New Product Revenue | Diversification |
| European Revenue | Geographic exposure |
| Operating Cash Flow | Earnings quality |
| R&D Pipeline | Future growth |
| Borrowings | IPO deleveraging |
| Finance Cost | Debt repayment benefit |
| ROCE | Capital efficiency |
For Symbiotec, one particularly useful long-term indicator will be whether newer APIs can grow faster than the existing top five products, gradually creating a more diversified revenue base.
Final View on Symbiotec Pharmalab IPO 2026
The Symbiotec Pharmalab IPO opened today, August 24, and closes on August 27, 2026. The ₹1,757 crore mainboard offer has a price band of ₹938–₹988 per share, with a minimum lot of 15 shares and listing scheduled for September 1.
Current market sentiment is strong. Opening-day reports place GMP around ₹345–₹409, with the higher estimate suggesting an unofficial premium of roughly 41% over the ₹988 upper price.
Fundamentally, Symbiotec offers investors exposure to a specialised pharmaceutical manufacturer with a significant international footprint. More than two-thirds of revenue comes from overseas markets, including approximately 30% from Europe.
The main concern is concentration. Its top five products contribute approximately 63% of revenue, while the IPO itself is heavily OFS-driven, with only ₹150 crore of the ₹1,757 crore offer representing fresh capital.
Of that fresh capital, ₹112.50 crore is intended for debt repayment or prepayment, which could strengthen the balance sheet and reduce finance costs.
Loading comments...