
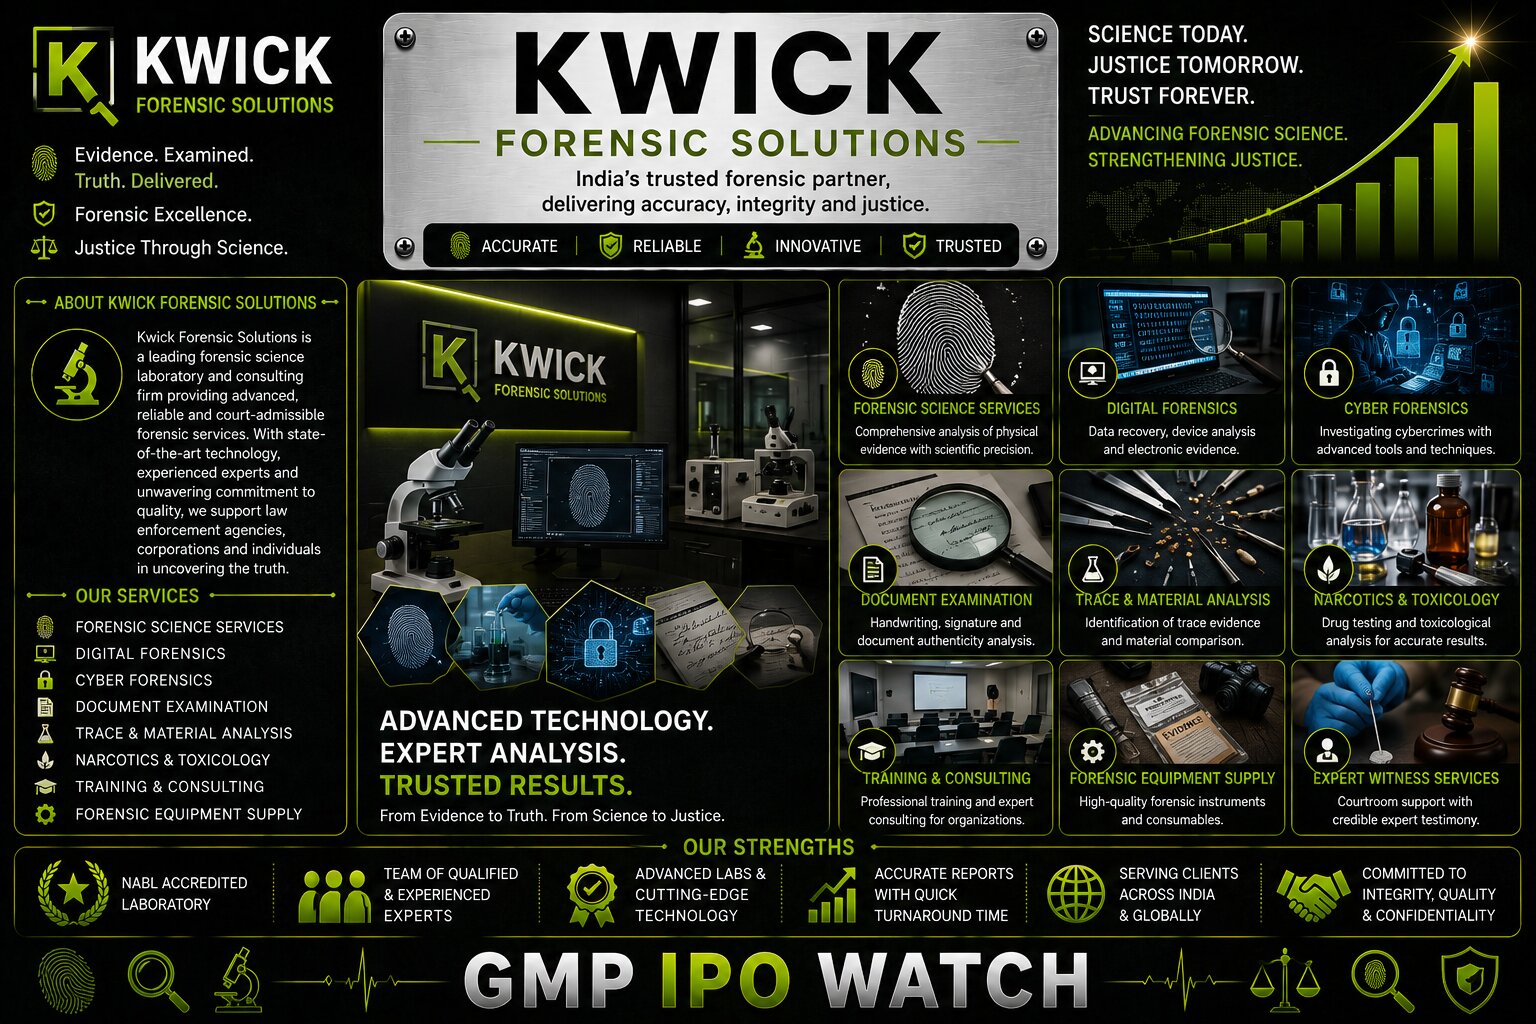
Kwick Forensic Solutions IPO 2026 – Latest Update
Kwick Forensic Solutions Limited's IPO opened on August 27, 2026, and will close today, August 31, 2026.
The company is raising approximately ₹50.77 crore through a combination of fresh issue and Offer for Sale. The IPO has attracted substantial demand, particularly from retail and non-institutional investors.
Kwick Forensic Solutions IPO Details
| Particular | Details |
|---|---|
| IPO Type | BSE SME IPO |
| Issue Size | ₹50.77 Crore |
| Fresh Issue | ₹41.05 Crore |
| Offer for Sale | ₹9.72 Crore |
| Price Band | ₹85 – ₹90 |
| Face Value | ₹10 |
| Lot Size | 1,600 Shares |
| Retail Minimum | 3,200 Shares |
| Minimum Investment | ₹2,88,000 |
| IPO Open Date | August 27, 2026 |
| IPO Close Date | August 31, 2026 |
| Allotment Date | September 1, 2026 |
| Listing Date | September 3, 2026 |
| Listing Platform | BSE SME |
| Registrar | Bigshare Services |
The minimum retail application at the ₹90 upper price requires ₹2.88 lakh.
Kwick Forensic Solutions IPO Subscription
Demand has accelerated sharply.
The latest available data shows the IPO subscribed 19.29 times overall, with retail investors leading the subscription at more than 36 times.
| Category | Subscription |
|---|---|
| QIB | 0.00x |
| NII | 9.05x |
| Retail | 36.23x |
| Overall | 19.29x |
On the first day itself, the IPO received approximately 7.51x subscription, with retail demand at 13.17x and NII at 3.17x.
The strong retail response has subsequently pushed the overall subscription significantly higher.
Kwick Forensic Solutions IPO GMP Today
Grey-market sentiment has strengthened considerably.
The latest GMP tracker reports a premium of approximately ₹70 per share on August 31, compared with a low of ₹15 earlier in the month.
At the ₹90 upper issue price:
| GMP Indicator | Latest Position |
|---|---|
| Upper Issue Price | ₹90 |
| GMP | ~₹70 |
| Indicative Price | ~₹160 |
| Indicative Premium | ~77.8% |
| Sentiment | Very Strong |
A ₹70 GMP implies an unofficial price of around ₹160.
However, GMP is an unofficial market indicator and can change quickly. It should not be considered a guaranteed listing price.
What Does Kwick Forensic Solutions Do?
Kwick Forensic Solutions operates in the specialised forensic science and law-enforcement technology industry.
The company provides products, solutions and technologies covering:
forensic sciences + fingerprint science + cyber/digital forensics + DNA forensics + social-media analytics + big-data analytics.
Its customer base primarily includes law-enforcement agencies and forensic-investigation organisations.
The company has been operating in this area since 2015, when it began providing end-to-end forensic products and technologies.
Product Portfolio
Kwick's offerings cover both physical and digital evidence.
| Segment | Products / Solutions |
|---|---|
| Fingerprint Forensics | Fingerprint kits and devices |
| Physical Evidence | Evidence collection kits |
| Crime Scene | Handheld forensic devices |
| Laboratory | Forensic laboratory equipment |
| Digital Forensics | Cyber and digital forensic tools |
| DNA Forensics | DNA investigation solutions |
| Mobile CSI | Mobile crime-scene investigation vehicles |
| Analytics | Social-media and big-data analytics |
This broad product range allows the company to serve multiple stages of modern forensic investigation.
Government and Law-Enforcement Demand
Kwick's business is closely connected with India's police and forensic ecosystem.
Its solutions are used for areas such as:
crime-scene investigation → evidence collection → fingerprint analysis → digital evidence → laboratory analysis → investigation support.
The company also has a Government Purchase Enlistment Certificate from NSIC, supporting its participation in government procurement.
Government demand can provide significant opportunities, although tender cycles and payment timelines can also affect revenue and cash flow.
Strong Financial Growth
Kwick Forensic Solutions has reported rapid growth over the last three financial years.
| Financial Metric | FY2024 | FY2025 | FY2026 |
|---|---|---|---|
| Revenue | ~₹30.18 Cr | ~₹65.08 Cr | ~₹105.71 Cr |
| EBITDA | ~₹5.45 Cr | ~₹12.25 Cr | ~₹19.06 Cr |
| PAT | ~₹2.83 Cr | ~₹8.56 Cr | ~₹13.51 Cr |
Revenue increased from approximately ₹30 crore to more than ₹105 crore in two years.
PAT also increased from approximately ₹2.83 crore to ₹13.51 crore.
This represents one of the strongest aspects of the company's IPO story.
Profitability Has Expanded Rapidly
The company's earnings progression is particularly notable:
FY2024 PAT → ₹2.83 Cr
FY2025 PAT → ₹8.56 Cr
FY2026 PAT → ₹13.51 Cr
This indicates that Kwick has not simply increased revenue; it has also substantially improved its absolute profitability.
The challenge now is to determine whether this growth can continue as the company becomes larger.
IPO Structure
The ₹50.77 crore IPO consists of both fresh capital and OFS.
| Component | Amount | Approx. Share |
|---|---|---|
| Fresh Issue | ₹41.05 Cr | ~81% |
| Offer for Sale | ₹9.72 Cr | ~19% |
| Total Issue | ₹50.77 Cr | 100% |
Around 81% of the IPO represents fresh capital entering the company.
This is important because most of the funds raised can be used for business requirements rather than providing an exit to existing shareholders.
Working Capital Is the Main IPO Objective
The primary stated objective of the fresh issue is to fund the company's working-capital requirements.
This is particularly relevant because Kwick serves government and institutional customers.
The business cycle can involve:
order → procurement → product delivery/project execution → invoicing → government/customer approval → payment collection.
A longer receivable cycle can tie up significant capital.
Additional working capital can therefore allow the company to accept and execute larger orders without excessive reliance on external borrowing.
Government Receivables Are a Key Factor
The company has identified extended receivable cycles from government customers as a working-capital requirement driver.
This creates a two-sided effect.
Positive: Government orders can provide large business opportunities.
Risk: Delayed payments can lock up cash and increase working-capital requirements.
Therefore, after the IPO, investors should pay close attention to receivables and operating cash flow.
Customer Concentration Remains a Risk
Kwick has a meaningful level of customer concentration.
The latest IPO information indicates that its top 10 customers accounted for around 77.64% of revenue.
This means losing or reducing business from a major customer could materially affect revenue.
As the company grows, increasing its customer base and reducing concentration would strengthen the business profile.
Geographic Concentration
Another risk highlighted in the IPO information is geographic dependence.
The company has significant business exposure to Gujarat and Bihar.
Expansion into additional states and central government agencies could reduce this concentration over time.
A broader customer base would also make revenue less dependent on the procurement cycles of a small number of regions.
Digital Forensics Creates a Long-Term Opportunity
One of Kwick's more interesting growth areas is digital and cyber forensics.
Modern investigations increasingly involve:
mobile phones + computers + CCTV + digital communications + social media + electronic records.
This creates demand for technologies capable of collecting, preserving and analysing digital evidence.
Kwick's presence across cyber forensics, digital forensics, social-media analytics and big-data analytics gives it exposure to this evolving market.
Specialised Market Can Provide Differentiation
Forensic technology is a specialised industry.
Unlike a generic trading or commodity business, customers often require:
technical expertise + specialised equipment + evidence-handling knowledge + regulatory compliance + investigation support.
This can create barriers to entry for companies without the necessary technical capabilities and institutional relationships.
However, maintaining technology relevance is essential because forensic tools and digital investigation techniques continue to evolve.
Key Strengths of Kwick Forensic Solutions
The company enters the IPO market with several notable positives:
- Specialised forensic technology business
- Exposure to law-enforcement modernisation
- Physical and digital forensic capabilities
- Strong recent revenue growth
- Strong PAT growth
- Government procurement exposure
- Fresh capital for working capital
- Broad forensic product portfolio
- Mobile CSI and laboratory solutions
Its recent financial trajectory is particularly impressive, with revenue growing from around ₹30 crore in FY2024 to over ₹105 crore in FY2026.
Major Risks
Investors should also consider:
- High customer concentration
- Government-order dependence
- Extended receivable cycles
- Geographic concentration
- Technology obsolescence
- Competition in forensic solutions
- Dependence on specialised products
- Working-capital requirements
- Sustainability of recent rapid growth
- SME-platform liquidity and volatility
The strong GMP and subscription numbers do not remove these underlying business risks.
What Investors Should Track After Listing
| Metric | Why It Matters |
|---|---|
| Revenue Growth | Growth sustainability |
| Order Book | Future visibility |
| Government Orders | Core demand |
| Customer Concentration | Revenue risk |
| Receivable Days | Collection efficiency |
| Working Capital | Capital utilisation |
| Operating Cash Flow | Earnings quality |
| EBITDA Margin | Operating efficiency |
| PAT Growth | Profit sustainability |
| Digital Forensic Revenue | Technology growth |
| New States / Customers | Diversification |
| ROCE | Capital efficiency |
For Kwick, receivable management and customer diversification could be just as important as revenue growth.
Final View on Kwick Forensic Solutions IPO
The Kwick Forensic Solutions IPO closes today, August 31, 2026, after attracting exceptionally strong investor interest. The ₹50.77 crore BSE SME IPO is priced at ₹85–₹90 per share, with a minimum investment of ₹2.88 lakh.
The latest available subscription data shows the IPO subscribed 19.29x overall, with retail investors at 36.23x and NIIs at 9.05x.
Grey-market sentiment has also strengthened sharply, with the latest GMP reported at around ₹70, implying an unofficial premium of nearly 78% over the ₹90 upper price band.
Fundamentally, the company has demonstrated rapid growth, with revenue increasing from approximately ₹30.18 crore in FY2024 to ₹105.71 crore in FY2026, while PAT increased to ₹13.51 crore.
Loading comments...