Sunshine Pictures IPO 2026 – Can Content Ownership Become More Valuable Than Individual Box-Office Hits?
A film-production business is unusual.
A manufacturing company can forecast how many units its factory might produce.
A retailer can study store footfall.
But one movie can become a major success while another project with a similar budget can disappoint.
That makes Sunshine Pictures Limited fundamentally a business of creative execution, capital allocation and intellectual-property monetisation.
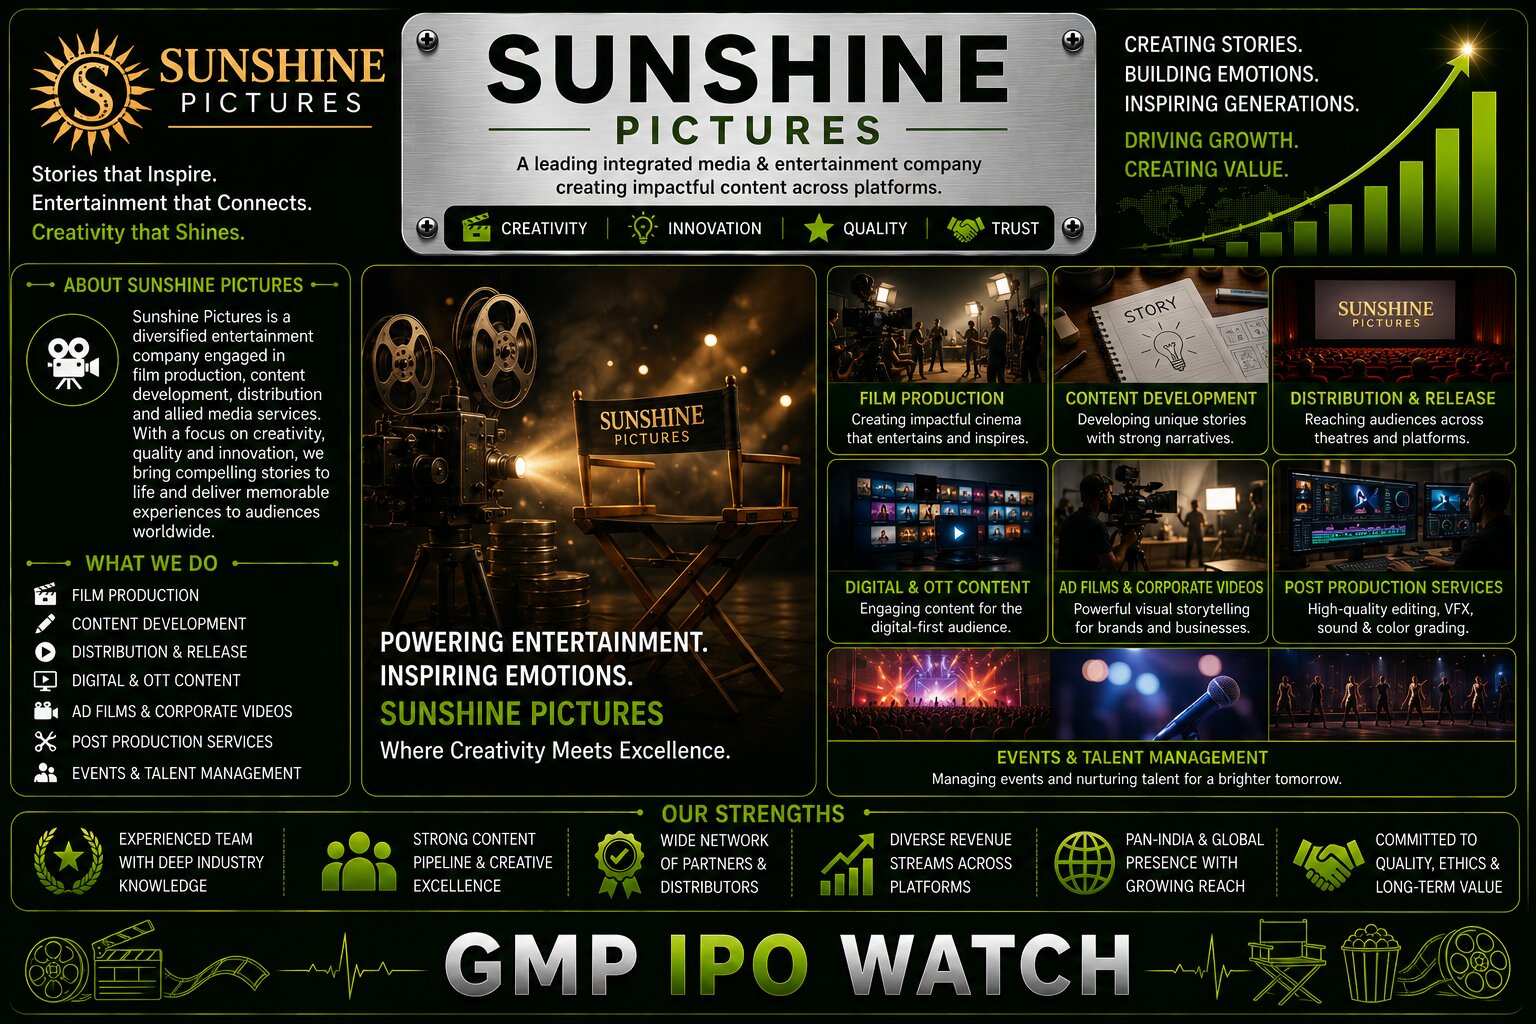
Sunshine Pictures was incorporated in 2007 and operates across the creation, development, production, marketing and distribution of commercial films, television content and web series. Its business model also includes ownership and monetisation of intellectual property and content rights.
The company has been associated with projects including Force, Commando, Holiday, Force 2, Commando 2 and The Kerala Story, and has worked across films, web series, television serials and shorter-form content.
That creates the central investment question:
Can Sunshine Pictures build a repeatable portfolio of monetisable content rather than depending too heavily on the commercial success of individual films?
That is the more important long-term question than tomorrow's IPO subscription.
Sunshine Pictures Is Really an Intellectual-Property Business
A movie may generate revenue from several channels.
Theatrical release is only one.
A successful piece of content can potentially earn through:
theatrical distribution → streaming rights → satellite television → music rights → international rights → digital monetisation.
Sunshine's business model spans the content lifecycle from script development and production through rights monetisation and distribution.
This means the real asset is not simply the physical film.
It is the bundle of intellectual-property rights attached to that content.
One Film Can Generate Revenue Multiple Times
Imagine Sunshine spends ₹30 crore developing and producing a film.
If revenue came only from cinema tickets, the economics would be highly concentrated around one release window.
But if Sunshine retains or monetises rights across multiple formats, the same content can potentially create several revenue streams.
For example:
Theatrical rights may generate the first revenue.
An OTT platform may then acquire streaming rights.
A television network may buy satellite rights.
Music or digital platforms may generate additional income.
This ability to monetise one creative asset several times is one of the most attractive aspects of the content business.
Rights Ownership Matters More Than Gross Box Office Alone
A film may report a large box-office collection.
That does not mean the producer receives all of it.
Money can be divided among:
- Exhibitors
- Distributors
- Producers
- Other rights holders
Therefore, investors should avoid judging Sunshine solely by the headline box-office number of a particular film.
The better question is:
How much economic interest does Sunshine actually retain in each project?
That determines the company's real return.
Co-Productions Can Reduce Financial Risk
Sunshine uses both sole-production and co-production structures, including strategic partnerships for some projects.
This can be useful because film production is capital intensive and unpredictable.
Suppose a ₹100 crore project is produced entirely by Sunshine.
The company may bear most of the financial risk.
If the same project is co-produced, the funding requirement and downside can be shared.
The trade-off is that successful-project economics may also be shared.
Co-production therefore becomes a form of portfolio risk management.
Running Several Projects at Once Can Improve the Business Model
A content company dependent on one major release each year faces extreme volatility.
Suppose that one film is delayed.
Revenue can shift substantially.
A stronger model involves several projects at different stages:
writing → pre-production → filming → post-production → release → rights monetisation.
Sunshine's growth strategy includes expanding its writer pool, sourcing more stories and developing creative talent so that multiple projects can be executed simultaneously.
That is strategically important because a broader pipeline can reduce dependence on any single title.
The ₹94 Crore Working-Capital Plan Is Central to the IPO
One prospectus-based IPO analysis states that approximately ₹94 crore of fresh proceeds is intended for the company's working-capital requirements.
For a content producer, working capital effectively means the ability to fund productions before all revenues arrive.
A film may require spending on:
- Actors
- Writers
- Directors
- Sets
- Locations
- Production crews
- Post-production
- Marketing
months before the final rights are monetised.
That makes working capital a direct growth resource.
Why Content Production Consumes Cash Before Revenue Arrives
Imagine Sunshine begins three projects simultaneously.
Project A is filming.
Project B is in post-production.
Project C is being marketed.
The company may already have spent substantial cash across all three while none has generated full revenue.
That creates a funding gap.
Fresh IPO capital can allow Sunshine to run a larger content slate without depending as heavily on external borrowing.
The ideal cycle is:
working capital → more simultaneous projects → broader content pipeline → more monetisation opportunities.
But More Content Does Not Automatically Mean Better Returns
This is one of the biggest risks.
A manufacturing company can sometimes increase output and reasonably predict revenue.
Creative content is far less predictable.
Producing twice as many films does not guarantee twice as much profit.
A larger slate creates value only when:
- Production budgets are disciplined
- Stories connect with audiences
- Distribution is effective
- Rights are monetised well
Sunshine therefore needs to scale creative quality and financial discipline together.
Project Selection Is Really Capital Allocation
For Sunshine, choosing a film is similar to an industrial company choosing a factory investment.
Management allocates capital based on expected future returns.
A ₹20 crore project with strong audience potential can outperform a ₹100 crore project with weak demand.
This makes script selection and project budgeting financial decisions, not merely creative decisions.
FY2026 Revenue Was Lower, but Profit Increased
One current prospectus-based analysis shows annualised FY2026 revenue of approximately ₹74.43 crore, compared with around ₹103.33 crore in the preceding period, while PAT increased from roughly ₹34.46 crore to ₹40.02 crore.
That is an unusual but interesting combination:
lower revenue + higher profit.
It suggests that revenue volume alone does not explain Sunshine's financial performance.
Content mix and rights economics may have a very large influence on margins.
Sunshine Pictures Financial Performance
| Particular | FY2025 | FY2026* |
|---|---|---|
| Revenue | ₹103.33 Cr | ₹74.43 Cr |
| EBITDA | ₹50.75 Cr | ₹58.54 Cr |
| PAT | ₹34.46 Cr | ₹40.02 Cr |
| EBITDA Margin | 49.11% | 78.65% |
| PAT Margin | 33.35% | 53.77% |
| Debt / Equity | 0.11× | 0.06× |
*FY2026 figures are presented on an annualised basis in the cited IPO analysis.
These numbers illustrate why Sunshine should not be analysed like a conventional volume-driven business.
PAT Margin Above 50% Is Very High
The cited annualised FY2026 PAT margin is approximately 53.77%.
That is exceptionally high.
But investors should be cautious about assuming this margin can be maintained every year.
Media revenue can depend heavily on:
- Timing of rights sales
- Project mix
- Profit sharing
- Delivery schedules
A year containing particularly attractive rights monetisation can look very different from a year with several productions still under development.
EBITDA Margin Was Nearly 79% on the Annualised Basis
The same analysis reports FY2026 annualised EBITDA margin of approximately 78.65%, versus about 49.11% in the previous period.
That is a dramatic increase.
It suggests Sunshine's latest reported period benefited from an unusually profitable content mix.
The key post-listing question is therefore:
What is the company's normalised margin across a full content cycle?
Investors should avoid using one unusually strong period as a permanent assumption.
Revenue Can Be Extremely Uneven in Entertainment
Suppose Sunshine completes a film in March but sells certain rights in April.
The associated revenue may fall into the next financial year.
That can create sharp annual fluctuations even when the underlying project pipeline remains healthy.
Therefore, a fall in one year's revenue does not necessarily mean customer demand collapsed.
Likewise, a sudden increase does not automatically imply sustainable recurring growth.
Content Pipeline Is More Useful Than One-Year Revenue
For Sunshine, a more useful operating framework includes:
projects under development + productions underway + projects ready for release + rights available for monetisation.
This provides a better view of future revenue than simply extrapolating the previous year's sales.
After listing, investors should pay attention to management disclosures around its project slate.
Film, OTT and Television Diversification Can Reduce Format Risk
Sunshine operates across commercial films, television and web series rather than relying entirely on theatrical cinema.
This matters because audience behaviour changes.
A project may be better suited for:
- Cinemas
- Streaming
- Television
Different formats allow Sunshine to target different consumer segments.
That can reduce dependence on a single distribution channel.
OTT Platforms Have Changed Producer Economics
Streaming platforms created another monetisation route for film and television producers.
A production company can potentially sell or license content directly to an OTT service rather than relying entirely on theatrical success.
This may improve revenue visibility for some projects.
But OTT buyers have also become more disciplined about acquisition costs.
Sunshine therefore still needs strong content economics rather than assuming every project will receive an attractive streaming deal.
Digital Originals Can Create Additional Opportunities
Sunshine's growth strategy includes films, OTT releases, web series, television, music and digital originals.
Digital-first content can sometimes involve:
- Lower budgets
- Faster production cycles
- More targeted audiences
This could allow Sunshine to experiment with more ideas without committing the capital required for a large theatrical film.
That can improve portfolio diversification.
A Small Core Team Can Create High Revenue Per Employee
Sunshine reportedly had a specialised core team of approximately 28 full-time employees as of June 30, 2026.
This reflects the project-based nature of film production.
Production houses do not necessarily keep every actor, technician or crew member permanently employed.
Instead, external professionals can be engaged project by project.
This can create a relatively asset-light fixed employee structure.
But Creative Talent Is a Major Dependency
The flip side is dependence on:
- Writers
- Directors
- Actors
- Technical talent
- Promoters
Creative industries can be highly dependent on a small number of individuals.
Sunshine's promoters include Vipul Amrutlal Shah, Shefali Vipul Shah, Aryaman Vipul Shah and Maurya Vipul Shah.
The company's ability to institutionalise creative development beyond individual promoters will matter as it scales.
Expanding the Writer Pool Could Reduce Creative Bottlenecks
Sunshine intends to source more story ideas and broaden its writer and creative talent network.
That strategy makes sense.
A production company cannot scale simply by increasing financial capital.
It also needs more:
ideas + scripts + directors + execution talent.
In entertainment, intellectual capital can become the real production bottleneck.
Existing Content Can Continue Generating Value
One important advantage of an established production house is its content library.
Older films and shows may continue to generate value through:
- Streaming
- Television
- Digital platforms
- Re-releases
This creates potential catalogue revenue.
A larger rights library can make Sunshine less dependent on only new releases.
However, the economic value depends on what rights the company actually owns and for how long.
Intellectual-Property Ownership Is the Metric Investors Should Watch
Two production houses may both produce ten films.
But their economic value can differ dramatically.
Company A may sell most rights permanently.
Company B may retain long-term rights and earn future licensing revenue.
Therefore, the number of films produced is less important than:
rights retained per project.
Sunshine investors should pay close attention to how future content ownership is structured.
Borrowings Are Relatively Low
IPO analysis reports debt-to-equity around 0.06× on the annualised FY2026 basis.
Earlier financial data also showed total borrowings declining from approximately ₹16.67 crore to ₹11.16 crore between the reported FY2024 and FY2025 consolidated periods.
Low leverage is a positive feature for a volatile content business.
A heavily indebted film producer can face substantial pressure if major releases are delayed.
Low Debt Gives Sunshine More Creative Flexibility
Suppose a film release needs to be postponed.
A company carrying heavy borrowing costs may feel forced to monetise quickly.
A lower-debt company has more flexibility to wait for:
- Better release timing
- Better distribution terms
- Better rights pricing
Financial flexibility can therefore improve content monetisation decisions.
The IPO Includes a Meaningful OFS
The ₹282.14 crore issue comprises:
₹172.80 crore fresh issue
and:
₹109.34 crore Offer for Sale.
That means approximately 61% of the issue is fresh company capital, while around 39% relates to existing-shareholder sales.
Investors should therefore distinguish between the total IPO size and the money actually entering Sunshine Pictures.
The Fresh Capital Is Still Significant
₹172.80 crore of fresh equity is substantial relative to Sunshine's historical balance sheet and revenue scale.
That gives management significantly more financial flexibility to:
- Fund productions
- Run projects simultaneously
- Invest in content development
The important challenge will be maintaining disciplined returns on this much larger capital base.
Post-IPO ROE Could Decline
IPOPlatform reports ROE around 27.58% on its annualised FY2026 presentation, compared with 32.80% in the previous period.
Once fresh IPO equity enters the company, the equity base increases further.
If PAT remains around ₹40 crore, ROE could fall.
This is not necessarily negative initially.
But over time, the ₹172.80 crore fresh issue should produce enough additional profitable content to justify the larger equity base.
The Valuation Is Not Cheap Enough to Ignore Execution Risk
One current prospectus-based analysis places Sunshine Pictures at roughly 32.55× earnings, with an estimated market capitalisation near ₹1,121 crore and EV/EBITDA around 19.30×.
Those multiples mean investors are already paying for future content success.
At such a valuation, several weak projects or delays could affect investor returns.
The company therefore needs to demonstrate that its historical successes can translate into a repeatable pipeline.
Listed Peer Comparisons Are Difficult
Media companies differ enormously.
One company may own television channels.
Another may focus on film production.
Another may operate a digital platform.
Another may own a catalogue of content rights.
Therefore, comparing Sunshine only through P/E with a broad media peer can be misleading.
Investors should also compare:
- Content ownership
- Project pipeline
- Balance-sheet risk
- Revenue volatility
- Cash generation
Cinema Success Remains Unpredictable
This is the unavoidable risk in Sunshine's business.
Even experienced producers cannot guarantee that audiences will respond positively to every release.
A strong cast and large budget do not guarantee success.
That means individual projects can have asymmetric outcomes.
Sunshine's best protection is not trying to predict every hit perfectly.
It is building a diversified slate where one weak project does not materially threaten the company.
Marketing Costs Can Change Project Economics
A film's production budget is only part of the total investment.
Marketing and distribution can require significant spending.
A project costing ₹30 crore to produce may need substantial additional promotional expenditure.
Therefore, investors should evaluate total project economics rather than only production budgets.
Release Delays Can Affect Working Capital
Film releases can be delayed because of:
- Production issues
- Post-production
- Scheduling
- Market conditions
- Regulatory matters
Every delay can keep capital tied up longer.
For Sunshine, a larger working-capital pool can reduce this pressure.
But it does not eliminate project risk.
Sunshine Pictures IPO Opens Tomorrow
As of August 17, 2026, there is no valid public subscription figure yet, because Sunshine Pictures IPO opens for public bidding tomorrow, August 18.
The public subscription window is:
August 18 to August 20, 2026.
The basis of allotment is expected on August 21, with tentative listing on August 25.
Any current “subscription” number shown before the public issue opens should therefore be treated cautiously unless it specifically refers to an anchor allocation rather than public bidding.
Anchor Bidding Is Scheduled for Today
The anchor investor portion is scheduled to open on August 17, one day before public bidding.
Once anchor allocation details are officially released, they can provide an early signal of institutional interest.
However, anchor participation should not replace analysis of valuation and content risk.
Sunshine Pictures IPO GMP Today
Grey-market sources are currently showing different figures.
InvestorGain's latest August 17 page shows GMP around:
₹58 per share, or approximately 16.11% above the ₹360 upper band, implying an unofficial price of around ₹418.
IPOJi, however, reports approximately:
₹45 GMP, implying an unofficial price near ₹405, or around 13% premium.
Because the figures differ, the safer description is:
Sunshine Pictures currently has positive grey-market sentiment in roughly the low-to-mid teens percentage range.
GMP Has Strengthened Ahead of Opening
InvestorGain's tracker shows GMP progressing from approximately:
₹0 on August 11, ₹17 on August 12, ₹30 on August 13, ₹50 on August 14–15, ₹54 on August 16 and ₹58 on August 17.
This indicates improving short-term sentiment ahead of public bidding.
But GMP does not change:
- Film economics
- Content pipeline
- Rights ownership
- Cash flow
It remains an unofficial indicator.
Key Strengths
Sunshine Pictures enters the IPO with a recognisable content-production track record, experience across theatrical films, television and OTT/web-series formats, relatively low leverage, strong recent profitability and a business model capable of monetising intellectual property across multiple distribution channels.
The ₹172.80 crore fresh issue also provides significant capital for future productions, while current grey-market sentiment is positive ahead of the August 18 opening.
Major Risks
The largest risk is project concentration and unpredictable audience demand. Content success cannot be guaranteed.
A second risk is revenue volatility, because film and rights monetisation can vary substantially between periods.
A third risk is margin sustainability. The cited annualised FY2026 PAT margin above 50% and EBITDA margin near 79% are exceptionally high and may not represent normalised economics.
Other important risks include working-capital requirements, dependence on creative talent, release delays, changing OTT economics and the possibility that additional IPO capital encourages excessive project spending.
What Could Drive Sunshine Pictures' Next Growth Phase?
Sunshine's strongest growth opportunities include a larger multi-project production slate, more OTT and web-series content, a larger writer and creative-development pool, stronger ownership of intellectual property, greater catalogue monetisation and disciplined co-production arrangements that allow the company to participate in larger projects while sharing financial risk.
What Investors Should Track After Listing
The most useful metrics will be:
- Number and value of projects under development and production
- Rights retained in each major project
- Working capital deployed per project
- Revenue and PAT across a full content cycle
- Operating cash flow versus accounting PAT
- Share of revenue from OTT, theatrical, television and catalogue rights
- ROCE on the ₹172.80 crore fresh capital
- Dependence on individual films or producers
These will provide a much better picture of the business than box-office headlines alone.
The Most Important Post-IPO Equation
Sunshine's strongest possible growth cycle is:
IPO capital → larger diversified project slate → more owned IP → multiple monetisation channels → repeat licensing revenue → stronger cash generation.
The weaker outcome would be:
IPO capital → larger production budgets → a few unsuccessful projects → capital locked in content → weaker returns.
That is the fundamental risk-reward balance of this IPO.
Should Investors Consider Sunshine Pictures IPO?
The positive case includes a proven production track record, multi-format content capabilities, relatively low leverage, strong recent profitability, significant fresh working capital and positive pre-opening GMP sentiment.
The caution case is equally important.
Entertainment remains a hit-driven industry, the latest margins are unusually high, revenue can fluctuate substantially between years, and a ₹172.80 crore fresh capital infusion will materially increase the amount of money management needs to deploy productively.
Sunshine Pictures should therefore be analysed as a content-IP and capital-allocation company, not merely as a film-production house associated with past hit titles.
Final View on Sunshine Pictures IPO 2026
The Sunshine Pictures IPO opens tomorrow, August 18, 2026, and closes August 20. The ₹282.14 crore mainboard issue has a price band of ₹342–₹360 per share, comprising ₹172.80 crore of fresh equity and ₹109.34 crore of OFS. The minimum retail application is 41 shares, requiring ₹14,760 at the upper band.
Financially, the company enters the market with an unusual profile.
One current prospectus-based analysis shows annualised FY2026 revenue of approximately ₹74.43 crore, EBITDA of ₹58.54 crore and PAT of around ₹40.02 crore, producing exceptionally high reported margins and low debt-to-equity of roughly 0.06×.
That profitability is attractive, but it also means investors need to be careful about extrapolating one period.
Film-production economics can change significantly based on the timing and success of individual projects and rights monetisation.
The IPO's most important strategic feature is the fresh capital.
Sunshine is receiving ₹172.80 crore of new equity, with a substantial portion intended to strengthen working capital and support a larger production pipeline.
That creates the long-term investment thesis:
larger working-capital base + diversified film/OTT/TV slate + stronger IP ownership + multiple monetisation channels = potential scalable content earnings.
The risk is equally straightforward:
more capital can produce more content, but it cannot guarantee more hits.
As of August 17, public subscription has not started. Current GMP is positive, with different trackers indicating roughly ₹45–₹58 per share, or around 13%–16% unofficial premium over the ₹360 upper band.
For long-term investors, the most important evidence after listing will be project pipeline quality, content-rights ownership, cash conversion, working-capital discipline and ROCE on the fresh IPO funds.
Loading comments...