Hy-Tech Engineers IPO 2026 – Manufacturing Expansion Takes Centre Stage
Hy-Tech Engineers Limited is preparing to enter the primary market with its mainboard IPO opening on August 24, 2026.
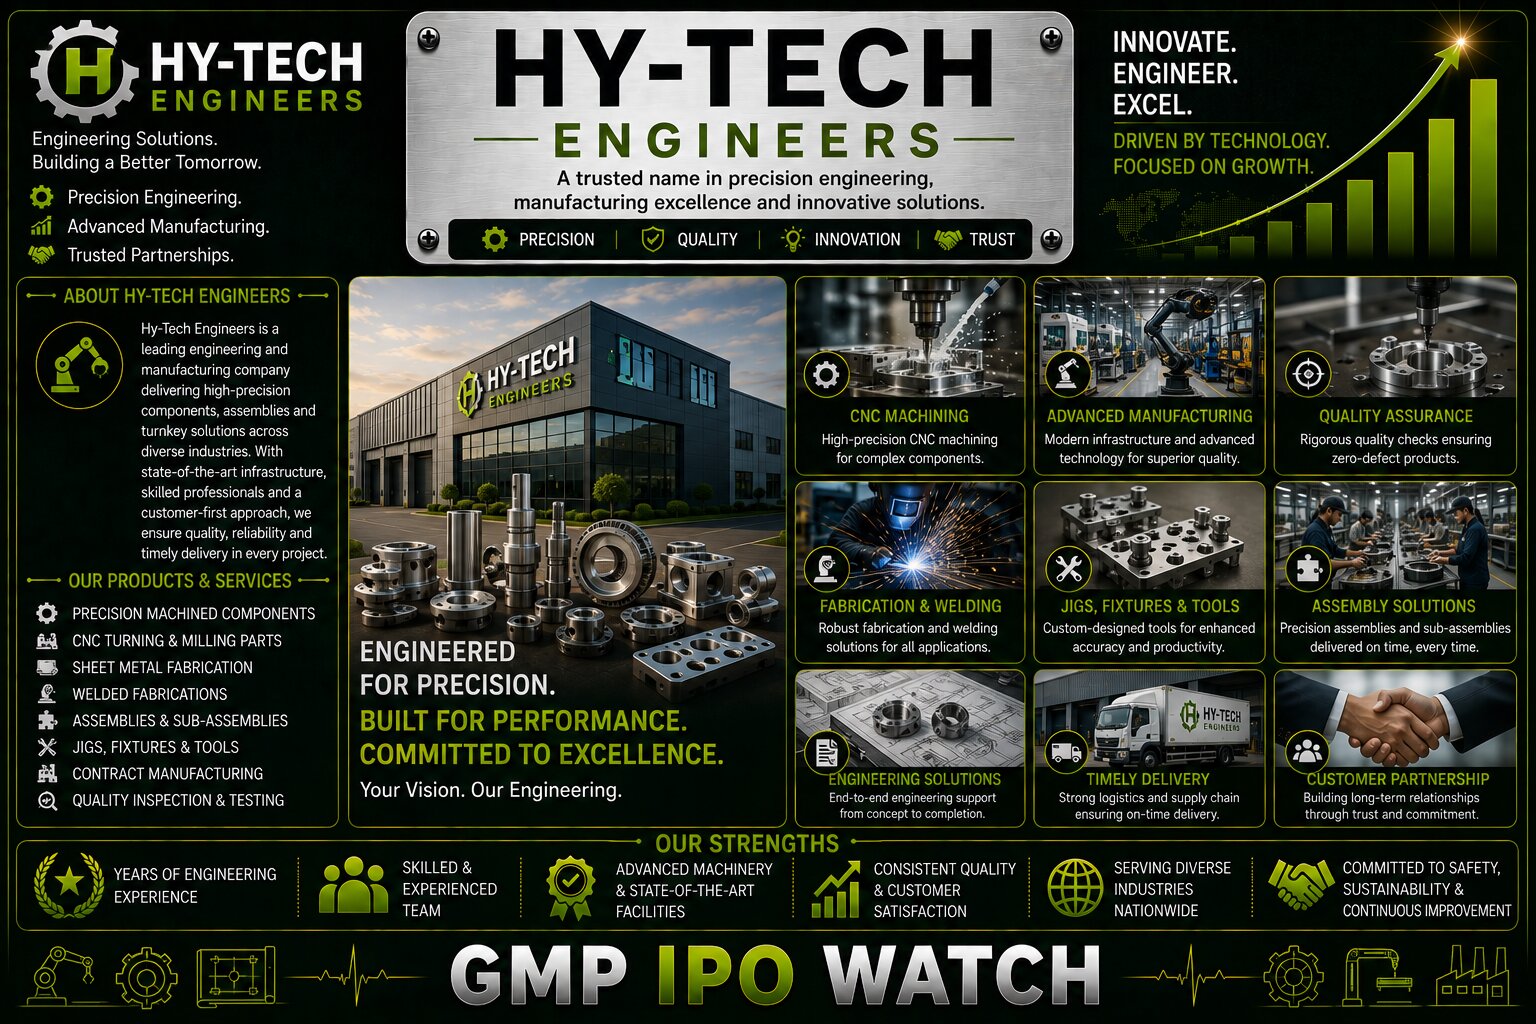
The company manufactures specialised hydraulic fittings and related engineering products used across industrial applications. Its manufacturing presence spans locations including Thane, Shirwal, Kavathe, Nashik and Pithampur, while it also serves international markets such as the US, Germany and Italy.
The IPO arrives at an interesting stage for the company.
Hy-Tech is already profitable and growing, but management now wants to expand manufacturing capacity while reducing part of its debt burden.
The central IPO story can therefore be summarised as:
new machinery + higher manufacturing capacity + lower debt + growing industrial demand.
Hy-Tech Engineers IPO Details
| Particular | Details |
|---|---|
| Company | Hy-Tech Engineers Ltd. |
| IPO Type | Mainboard IPO |
| Listing | BSE & NSE |
| Issue Size | ₹135.73 Crore |
| Fresh Issue | Approx. ₹60 Crore |
| OFS | Approx. 1.43 Crore Shares |
| Price Band | ₹50 – ₹53 |
| Face Value | ₹5 |
| Lot Size | 283 Shares |
| Minimum Investment | ₹14,999 |
| IPO Open Date | August 24, 2026 |
| IPO Close Date | August 27, 2026 |
| Allotment Date | August 28, 2026 |
| Demat Credit | August 31, 2026 |
| Listing Date | September 1, 2026 |
| Industry | Engineering / Hydraulic Components |
The final ₹135.73 crore offer is priced between ₹50 and ₹53 per share. Retail investors can apply for a minimum lot of 283 shares, requiring ₹14,999 at the upper price band.
Hy-Tech Engineers IPO GMP Today
As of August 20, 2026, the latest reported grey-market premium for Hy-Tech Engineers is approximately:
₹5 per share.
At the upper issue price of ₹53:
₹53 + ₹5 = ₹58
This represents an unofficial potential premium of approximately:
9.43%.
| GMP Particular | Current Status |
|---|---|
| Upper Price Band | ₹53 |
| Latest GMP | ₹5 |
| Indicative Price | ₹58 |
| Indicative Premium | ~9.43% |
| GMP Sentiment | Positive |
Since the IPO does not open until August 24, there is currently no public subscription data.
GMP is an unofficial market indicator and can change substantially before listing, so it should not be treated as a guaranteed return.
What Does Hy-Tech Engineers Do?
Hy-Tech Engineers is a specialised engineering company focused primarily on hydraulic fittings and related components.
These components may appear small compared with the machinery in which they operate, but they perform an important function.
Hydraulic systems use pressurised fluid to transfer power.
Such systems can be found across:
- Construction equipment
- Agricultural machinery
- Industrial machines
- Material-handling equipment
- Mining equipment
- Heavy engineering applications
Hydraulic fittings help connect different components while maintaining the pressure and reliability required by the system.
Precision Is Critical in Hydraulic Components
A hydraulic fitting is not simply a standard metal connector.
It must perform under:
pressure + vibration + temperature variation + continuous industrial use.
Failure of even a relatively inexpensive fitting can stop a much more expensive machine.
That means customers care about:
precision + consistency + durability + quality control.
For Hy-Tech, manufacturing quality is therefore central to maintaining long-term customer relationships.
FY2026 Revenue Increased to ₹193.44 Crore
Hy-Tech continued to grow ahead of its IPO.
Current IPO financial data shows revenue increasing from approximately:
₹166.71 crore in FY2025
to:
₹193.44 crore in FY2026.
PAT increased from:
₹19.62 crore → ₹22.59 crore.
| Financial Metric | FY2025 | FY2026 |
|---|---|---|
| Revenue | ₹166.71 Cr | ₹193.44 Cr |
| PAT | ₹19.62 Cr | ₹22.59 Cr |
| Revenue Growth | — | ~16% |
| PAT Growth | — | ~15% |
The numbers show a business expanding both its top line and bottom line rather than pursuing revenue growth at the expense of profitability.
Profitability Is an Important Strength
FY2026 PAT of approximately ₹22.59 crore against revenue of ₹193.44 crore indicates a healthy profitability profile for an engineering manufacturer.
For investors, maintaining margins will be particularly important as the company adds new machinery.
Expansion is valuable only when the additional assets produce adequate returns.
The desired equation is:
new machinery → higher production → higher sales → operating leverage → higher profit.
Manufacturing Expansion Is a Major IPO Objective
Hy-Tech plans to use a meaningful portion of its fresh IPO proceeds to procure new machinery and equipment.
The expansion relates to its:
Kavathe Unit + Shirwal Unit + Pithampur Unit-I.
The original offer documents earmarked approximately ₹31.99 crore toward these capital-expenditure requirements.
This is important because the IPO is not purely a balance-sheet transaction.
Part of the capital is intended to increase the company's manufacturing capabilities.
Planned Use of Fresh Capital
| Purpose | Approx. Amount |
|---|---|
| Manufacturing Capex | ₹31.99 Cr* |
| Debt Repayment | ₹18.00 Cr* |
| General Corporate Purposes | Balance |
| Main Focus | Expansion + Deleveraging |
*Amounts reflect the offer-document allocation disclosed for these objectives.
New Machinery Can Improve More Than Capacity
Manufacturing capex can create several benefits.
The obvious benefit is increased production.
But modern machinery can also improve:
- Manufacturing precision
- Production speed
- Product consistency
- Automation
- Quality
- Labour productivity
For precision-engineering businesses, these improvements can matter as much as headline capacity expansion.
Debt Repayment Provides a Second Benefit
The company also plans to use IPO proceeds toward repayment or prepayment of certain borrowings.
This gives the IPO a two-sided growth strategy.
One part of the capital goes toward:
building future capacity.
Another goes toward:
reducing existing financial obligations.
Lower borrowings can reduce interest costs and strengthen future cash flows.
Export Exposure Provides Diversification
Hy-Tech serves customers not only in India but also in overseas markets including the United States, Germany and Italy.
Exports can provide several advantages:
larger addressable market + geographic diversification + access to global industrial customers.
For an Indian engineering manufacturer, successfully supplying developed markets can also demonstrate manufacturing and quality capabilities.
However, exports introduce additional risks such as currency movements, trade conditions and international economic cycles.
Customer Relationships Can Create Entry Barriers
Industrial customers generally do not select critical engineering components only on price.
Before accepting a component, customers may evaluate:
- Technical specifications
- Manufacturing processes
- Product quality
- Reliability
- Delivery capability
Once a supplier becomes qualified and consistently performs well, replacing that supplier may create operational risk for the customer.
This can make established industrial relationships valuable.
Customer Concentration Needs Attention
At the same time, current IPO analysis identifies customer concentration as one of Hy-Tech's important risks.
A large customer can be extremely valuable.
But excessive dependence creates vulnerability.
If an important customer:
reduces production → changes supplier → renegotiates pricing → delays orders
Hy-Tech's revenue and capacity utilisation could be affected.
Investors should therefore monitor whether the company gradually broadens its customer base.
Manufacturing Utilisation Will Matter After Expansion
Buying machinery does not automatically create profit.
Suppose Hy-Tech installs ₹30 crore of additional equipment.
If customer demand allows those machines to operate at high utilisation, returns can be attractive.
But if orders are insufficient:
machinery remains underutilised → depreciation continues → fixed costs remain → ROCE weakens.
This is why order visibility and capacity utilisation will become important post-IPO indicators.
Industrial Growth Provides a Long-Term Opportunity
Hy-Tech is exposed to India's broader manufacturing and engineering economy.
Demand for hydraulic components can benefit from expansion across:
construction equipment + agriculture equipment + manufacturing + infrastructure + material handling + industrial automation.
India's push toward greater domestic manufacturing can also create opportunities for component suppliers capable of meeting demanding quality standards.
Import Substitution Can Create Opportunities
Indian machinery manufacturers have historically relied on imported components in several specialised categories.
Domestic engineering companies that can deliver comparable quality may benefit from customers seeking:
shorter supply chains + local sourcing + lower logistics risk + faster deliveries.
For Hy-Tech, this could provide another avenue for growth if it continues strengthening product quality and technical capabilities.
But Engineering Demand Is Cyclical
Industrial manufacturing is not immune to economic cycles.
When customers are expanding production, they purchase more equipment and components.
During weak industrial cycles, companies can delay:
- Machinery purchases
- Expansion
- Maintenance capex
- Inventory replenishment
Hy-Tech's revenue can therefore fluctuate with industrial activity.
This makes customer and end-industry diversification important.
Raw Material Prices Can Affect Margins
Engineering manufacturers rely on metals and other industrial inputs.
If raw-material prices increase rapidly but customer contracts prevent immediate price increases, margins can come under pressure.
The company therefore needs effective:
procurement + inventory management + pricing discipline.
Margin stability will be worth monitoring after listing.
Key Strengths of Hy-Tech Engineers
The company enters its IPO with several positives.
Established manufacturing business: Hy-Tech has decades of experience in hydraulic engineering products.
Profitable operations: FY2026 PAT reached approximately ₹22.59 crore.
Revenue growth: FY2026 revenue increased to approximately ₹193.44 crore.
International exposure: The company serves customers in India and overseas markets including the US, Germany and Italy.
Capacity expansion: IPO proceeds support new machinery across multiple manufacturing units.
Debt reduction: Part of the proceeds is earmarked for repayment of borrowings.
Positive GMP: The latest reported grey-market premium is approximately ₹5.
Major Risks
Hy-Tech's key risks include customer concentration and dependence on sufficient orders to utilise manufacturing capacity. Current IPO analysis also highlights risks related to machinery expansion without corresponding confirmed demand.
Other areas investors should watch include:
- Raw-material price fluctuations
- Industrial cyclicality
- Export-market demand
- Foreign-exchange movements
- Manufacturing disruptions
- Quality-control issues
- Customer pricing pressure
- Capacity-utilisation risk
- Competition from domestic and international manufacturers
What Could Drive the Next Phase of Growth?
The first driver is successful commissioning of the new machinery funded through IPO proceeds.
The second is higher utilisation of expanded capacity.
The third is acquiring new domestic customers.
The fourth is increasing exports.
The fifth is developing higher-value precision-engineering components.
Finally, debt reduction could improve profitability by lowering finance costs.
If these factors work together, the company could potentially achieve:
higher capacity + better utilisation + greater revenue + stronger cash flow.
What Investors Should Track After Listing
| Metric | Why It Matters |
|---|---|
| Revenue Growth | Demand for products |
| PAT Growth | Earnings expansion |
| EBITDA Margin | Manufacturing profitability |
| Capacity Utilisation | Capex productivity |
| Export Revenue | Global growth |
| Customer Concentration | Revenue risk |
| New Customer Wins | Diversification |
| Borrowings | Deleveraging |
| Finance Cost | Benefit from debt repayment |
| Operating Cash Flow | Earnings quality |
| ROCE | Return on new machinery |
| Order Pipeline | Future demand visibility |
For Hy-Tech, capacity utilisation and ROCE after the new machinery becomes operational could be more important than simply tracking revenue growth.
Final View on Hy-Tech Engineers IPO 2026
The Hy-Tech Engineers IPO opens on August 24 and closes on August 27, 2026, with a price band of ₹50–₹53 per share. The issue size is approximately ₹135.73 crore, while the minimum retail application is 283 shares or ₹14,999 at the upper band. The shares are expected to list on BSE and NSE on September 1.
As of August 20, 2026, the latest reported GMP is approximately ₹5, implying an unofficial estimated price of around ₹58 compared with the ₹53 upper issue price—a premium of roughly 9.43%.
Fundamentally, the company enters the IPO with improving numbers. FY2026 revenue reached approximately ₹193.44 crore, compared with ₹166.71 crore in FY2025, while PAT increased from ₹19.62 crore to ₹22.59 crore.
The IPO also gives Hy-Tech an opportunity to strengthen its manufacturing base. Capital is being directed toward new machinery at the Kavathe, Shirwal and Pithampur facilities while another portion supports debt repayment.
Loading comments...