
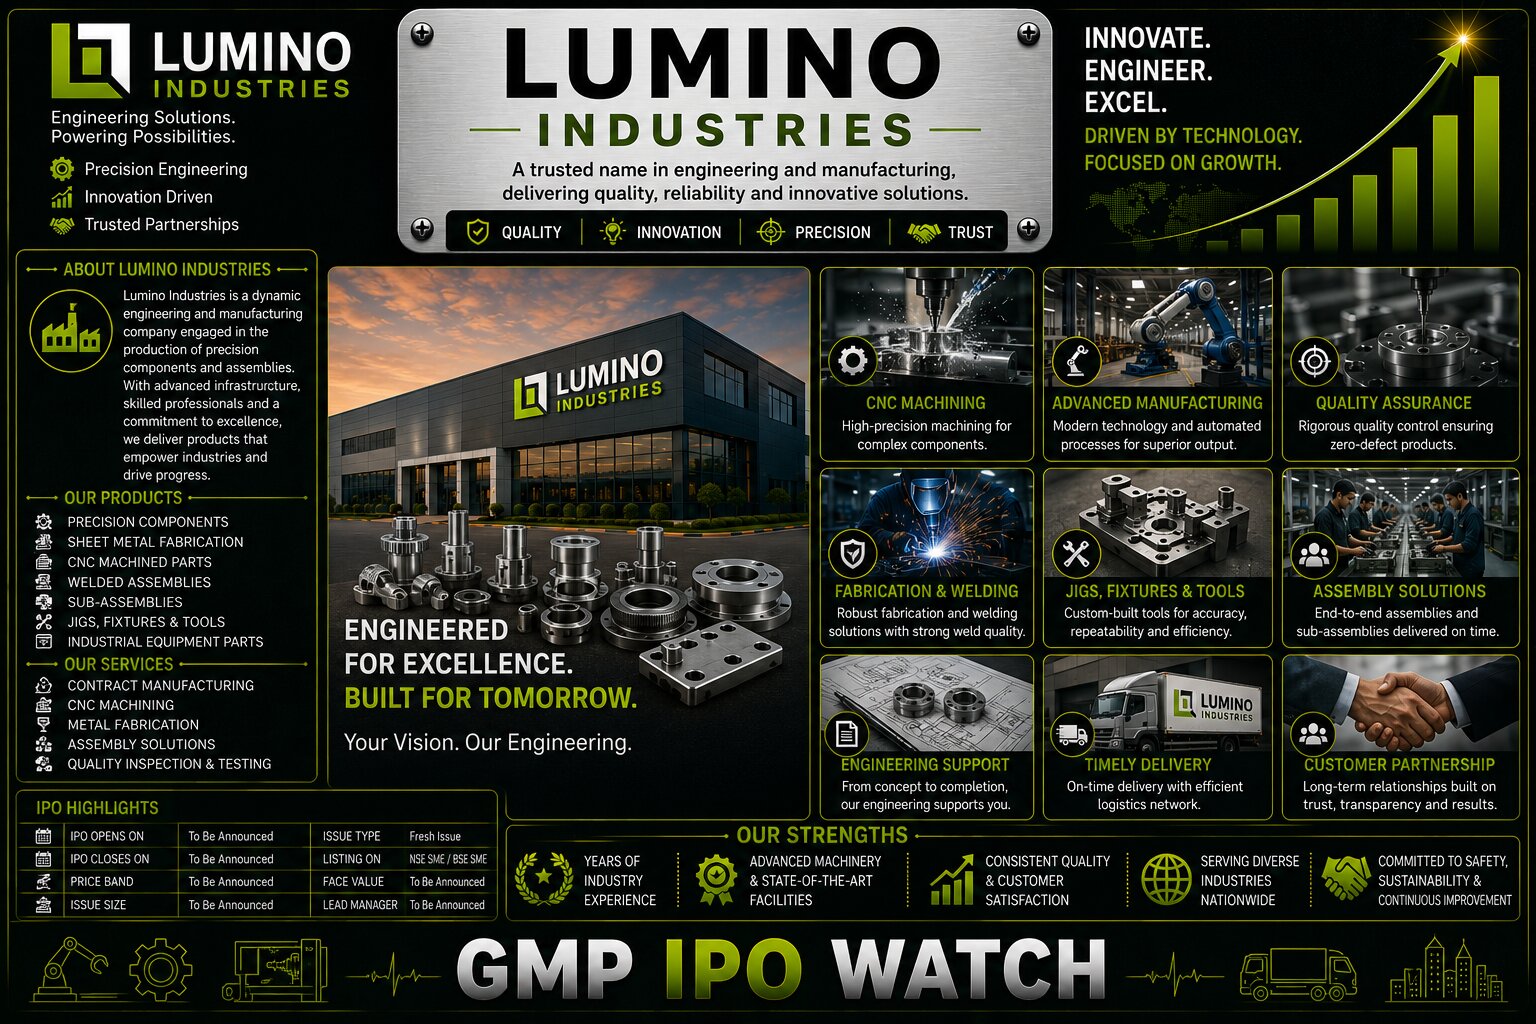
Lumino Industries IPO 2026 – Opening Day Update
Lumino Industries Limited's mainboard IPO opened for subscription today, August 27, 2026.
The company is raising ₹700 crore through a combination of fresh shares and an Offer for Sale. The IPO will remain open until August 31, 2026, with the price band fixed at ₹78 to ₹82 per equity share.
The issue has attracted attention before opening because of its strong grey-market premium and the company's exposure to India's power transmission and distribution sector.
Lumino Industries IPO Details
| Particular | Details |
|---|---|
| IPO Type | Mainboard IPO |
| Issue Size | ₹700 Crore |
| Fresh Issue | ₹500 Crore |
| Offer for Sale | ₹200 Crore |
| Shares Offered* | ~8.54 Crore |
| Price Band | ₹78 – ₹82 |
| Face Value | ₹5 |
| Lot Size | 182 Shares |
| Minimum Investment | ₹14,924 |
| IPO Open Date | August 27, 2026 |
| IPO Close Date | August 31, 2026 |
| Allotment Date | September 1, 2026 |
| Demat Credit | September 2, 2026 |
| Listing Date | September 3, 2026 |
| Listing | BSE & NSE |
| Registrar | Bigshare Services |
*At the upper price band, the issue comprises approximately 8.54 crore shares.
Lumino Industries IPO GMP Today
Grey-market sentiment is currently one of the biggest talking points around the IPO.
On the opening day, the latest report indicates that Lumino Industries shares are commanding a premium equivalent to approximately 61% over the issue price.
| GMP Indicator | Latest Position |
|---|---|
| Upper Issue Price | ₹82 |
| Reported Premium | ~61% |
| Approx. Indicative Price | ~₹132 |
| GMP Sentiment | Strong |
| IPO Status | Open |
Another tracker recently reported a GMP of around ₹47 per share, showing that grey-market quotes can differ between sources and times.
GMP is unofficial and can change sharply before listing. It should not be considered a guaranteed listing price.
What Does Lumino Industries Do?
Lumino Industries is an integrated engineering, procurement and construction (EPC) and electrical-products company focused heavily on India's power transmission and distribution industry.
Its manufacturing portfolio includes:
conductors + power cables + electrical wires + HTLS conductors + railway signalling cables + aerial bunch cables + specialised electrical products.
The company therefore participates in two connected areas:
manufacturing electrical products → supplying power infrastructure
and
EPC execution → developing transmission and distribution projects.
This gives Lumino exposure to India's ongoing electricity-network investment.
Power Transmission Is the Core Opportunity
India's electricity infrastructure requires continuous investment to connect new generation capacity with consumers.
This includes:
transmission lines + substations + distribution networks + renewable-energy connections + conductors + cables.
Lumino manufactures several of the products required in this infrastructure while also executing EPC projects.
This integrated position can allow the company to participate in multiple parts of power-sector capital expenditure.
Lumino Also Manufactures HTLS Conductors
One specialised area of Lumino's portfolio is High Temperature Low Sag (HTLS) conductors.
These conductors are designed to carry higher electrical loads while limiting sag at elevated temperatures, making them useful for upgrading transmission capacity.
Lumino has also entered into a strategic collaboration with CTC Global Corporation for manufacturing, selling and distributing ACCC conductors.
Such specialised products can potentially provide better differentiation than standard commodity electrical products.
FY2026 Revenue Crossed ₹2,000 Crore
Lumino Industries operates at a considerably larger scale than many companies currently entering the IPO market.
| Financial Metric | FY2024 | FY2025 | FY2026 |
|---|---|---|---|
| Revenue from Operations | ₹1,407.32 Cr | ₹1,917.97 Cr | ₹2,041.07 Cr |
| PAT | ₹86.61 Cr | ₹124.59 Cr | ₹159.99 Cr |
| Net Worth | ₹445.97 Cr | ₹570.45 Cr | ₹729.71 Cr |
| Total Assets | ₹1,175.44 Cr | ₹1,718.66 Cr | ₹2,174.88 Cr |
| Borrowings | ₹40.91 Cr | ₹418.83 Cr | ₹384.16 Cr |
Revenue increased approximately 6.4% in FY2026, from ₹1,917.97 crore to ₹2,041.07 crore.
PAT increased much faster, rising approximately 28.4% to ₹160 crore.
Profit Has Grown Faster Than Revenue
Lumino's three-year financial trend is notable.
Revenue increased from:
₹1,407.32 Cr → ₹1,917.97 Cr → ₹2,041.07 Cr
while PAT increased from:
₹86.61 Cr → ₹124.59 Cr → ₹159.99 Cr.
FY2026 therefore shows relatively moderate topline growth but a considerably stronger improvement in profitability.
Maintaining this margin improvement will be important after listing.
Lumino Industries IPO Valuation & KPIs
The company's FY2026 operating and return ratios provide a useful picture of profitability.
| KPI | FY2026 |
|---|---|
| ROE | 24.62% |
| ROCE | 25.75% |
| EBITDA Margin | 11.71% |
| PAT Margin | 7.66% |
| Debt to Equity | 0.53 |
| EPS | ₹6.57 |
| NAV | ₹29.95 |
At the upper issue price of ₹82 and FY2026 EPS of ₹6.57, the issue implies a P/E of approximately 12.5 times based on pre-issue earnings.
The company's expected market capitalisation at the upper band is approximately ₹2,497 crore.
Order Book Stands at ₹3,149.8 Crore
One of the more important indicators for an EPC and power-equipment company is its order book.
Lumino Industries reported an order book of approximately ₹3,149.8 crore as of March 2026, compared with ₹2,436.2 crore a year earlier.
| Period | Order Book |
|---|---|
| March 2025 | ₹2,436.2 Cr |
| March 2026 | ₹3,149.8 Cr |
| YoY Increase | ~29.3% |
A growing order book provides future revenue visibility, although actual revenue depends on successful and timely execution.
The order book is particularly important because FY2026 revenue growth slowed to around 6.4%.
IPO Is Primarily a Fresh Issue
Lumino's ₹700 crore IPO has a relatively significant fresh-capital component.
| IPO Component | Amount | Approx. Share |
|---|---|---|
| Fresh Issue | ₹500 Cr | ~71% |
| Offer for Sale | ₹200 Cr | ~29% |
| Total Issue | ₹700 Cr | 100% |
Approximately 71% of the IPO represents fresh capital entering the company.
The ₹200 crore OFS is being offered by promoter selling shareholders.
This means most of the IPO proceeds are intended to strengthen Lumino's financial position and operations rather than simply providing an exit to existing shareholders.
₹337 Crore Will Be Used for Debt Repayment
The largest identified use of fresh IPO proceeds is debt reduction.
Lumino plans to allocate approximately ₹337 crore toward prepayment or repayment of certain outstanding borrowings.
Use of IPO Proceeds
| Purpose | Amount |
|---|---|
| Debt Repayment / Prepayment | ₹337.00 Cr |
| Manufacturing Capex | ₹15.01 Cr |
| General Corporate Purposes | Balance |
| Total Fresh Issue | ₹500.00 Cr |
This makes deleveraging one of the most important parts of the IPO story.
Debt Reduction Could Have a Meaningful Impact
Lumino's finance cost stood at approximately ₹66 crore in FY2026.
Reducing borrowings using IPO proceeds could therefore potentially improve future earnings through lower interest expenses.
The financial equation is:
₹337 Cr debt repayment → lower borrowings → potentially lower finance costs → stronger cash flows and profitability.
The actual benefit will depend on which loans are repaid and whether the company takes on additional debt for future expansion or working-capital requirements.
₹15 Crore Will Support Manufacturing Capex
Lumino also plans to deploy approximately ₹15.01 crore toward equipment, machinery, civil works and interior development at an existing manufacturing facility.
This amount is relatively small compared with the ₹337 crore earmarked for debt repayment.
Therefore, this IPO is more heavily focused on strengthening the balance sheet than funding a very large new manufacturing expansion.
Working Capital Is an Important Risk
Lumino's business requires substantial working capital.
As of FY2026, the company reported approximately ₹894.86 crore of trade receivables and ₹364.07 crore of inventory.
This reflects the cash requirements involved in:
buying materials → manufacturing → EPC execution → billing customers → collecting payments.
If customer payments are delayed, more capital can become locked in receivables.
This is particularly important because Lumino serves a significant number of government and public-sector customers.
Government Customers Generate More Than Half of Revenue
Lumino derives a substantial portion of its business from government entities.
Government customers contributed approximately 53.12% of FY2026 revenue, compared with 79.89% in FY2025 and 85.58% in FY2024.
| Period | Revenue from Government Entities |
|---|---|
| FY2024 | 85.58% |
| FY2025 | 79.89% |
| FY2026 | 53.12% |
The declining percentage suggests that customer diversification has improved.
However, government entities still account for more than half of revenue.
Tender timing, project approvals and payment delays can therefore materially affect the business.
Customer Concentration Has Improved
The company's top 10 customers generated approximately:
90.78% of FY2024 revenue → 80.33% in FY2025 → 46.52% in FY2026.
This is a significant improvement.
Lower customer concentration can reduce the impact of losing or receiving fewer orders from one major customer.
Maintaining this diversification while increasing the overall order book would strengthen Lumino's business profile.
Raw Material Costs Are the Biggest Operating Risk
Materials represented approximately 83.73% of Lumino's FY2026 total expenses.
Key electrical products require metals and other raw materials whose prices can fluctuate significantly.
The risk looks like:
higher aluminium/copper/input prices → higher production costs → margin pressure if costs cannot be passed to customers.
Some customer contracts include price-escalation clauses, but these may not always completely offset increases in raw-material prices.
Supplier Concentration Is Also High
Lumino is dependent on a relatively concentrated group of raw-material suppliers.
Its top 10 suppliers accounted for approximately 87.5% of total raw-material costs in FY2026.
A disruption involving an important supplier could therefore:
increase procurement costs + delay manufacturing + affect project execution.
Supplier diversification will remain an important operational factor as the business expands.
Anchor Investors Put in ₹207 Crore
Before the public IPO opened, Lumino Industries raised approximately ₹206.99 crore from anchor investors.
Anchor participation provides institutional backing ahead of public bidding, although it should not be considered a guarantee of listing performance.
Key Strengths of Lumino Industries
Lumino has several notable strengths going into the IPO.
The company operates across both manufacturing and EPC activities in the power transmission and distribution sector, reported FY2026 revenue exceeding ₹2,000 crore, and had an order book of approximately ₹3,149.8 crore as of March 2026.
PAT increased from ₹86.61 crore in FY2024 to approximately ₹160 crore in FY2026, while ROCE reached 25.75%.
The IPO also has a large fresh-issue component, with ₹337 crore earmarked for debt repayment.
Major Risks
Despite the growth opportunity, investors should consider several risks:
- High working-capital requirements
- Dependence on government customers
- Raw-material price volatility
- High supplier concentration
- EPC project execution delays
- Customer payment delays
- Competitive power-equipment market
- Dependence on infrastructure spending
- Large outstanding borrowings
- Ability to maintain recent margin improvement
The company's outstanding borrowings were approximately ₹1,856.78 crore as of July 31, 2026, making successful deleveraging particularly important.
What Investors Should Track After Listing
| Metric | Why It Matters |
|---|---|
| Order Book | Future revenue visibility |
| Revenue Growth | Business expansion |
| Manufacturing Revenue | Product demand |
| EPC Revenue | Project execution |
| EBITDA Margin | Cost efficiency |
| PAT Growth | Earnings momentum |
| Borrowings | IPO debt reduction |
| Finance Costs | Deleveraging benefit |
| Receivable Days | Collection efficiency |
| Operating Cash Flow | Earnings quality |
| Government Revenue Share | Customer diversification |
| ROCE | Capital efficiency |
For Lumino Industries, debt reduction, order-book execution and working-capital management could become the most important indicators after listing.
Final View on Lumino Industries IPO
The Lumino Industries IPO opened today, August 27, 2026, and closes on August 31. The ₹700 crore mainboard offering has a price band of ₹78–₹82 and comprises a ₹500 crore fresh issue plus ₹200 crore OFS. Listing is scheduled for September 3 on BSE and NSE.
Market sentiment is currently strong, with today's report indicating a grey-market premium of approximately 61% over the issue price.
Fundamentally, Lumino reported ₹2,041.07 crore FY2026 revenue and approximately ₹160 crore PAT, while its March 2026 order book stood at ₹3,149.8 crore.
Loading comments...