
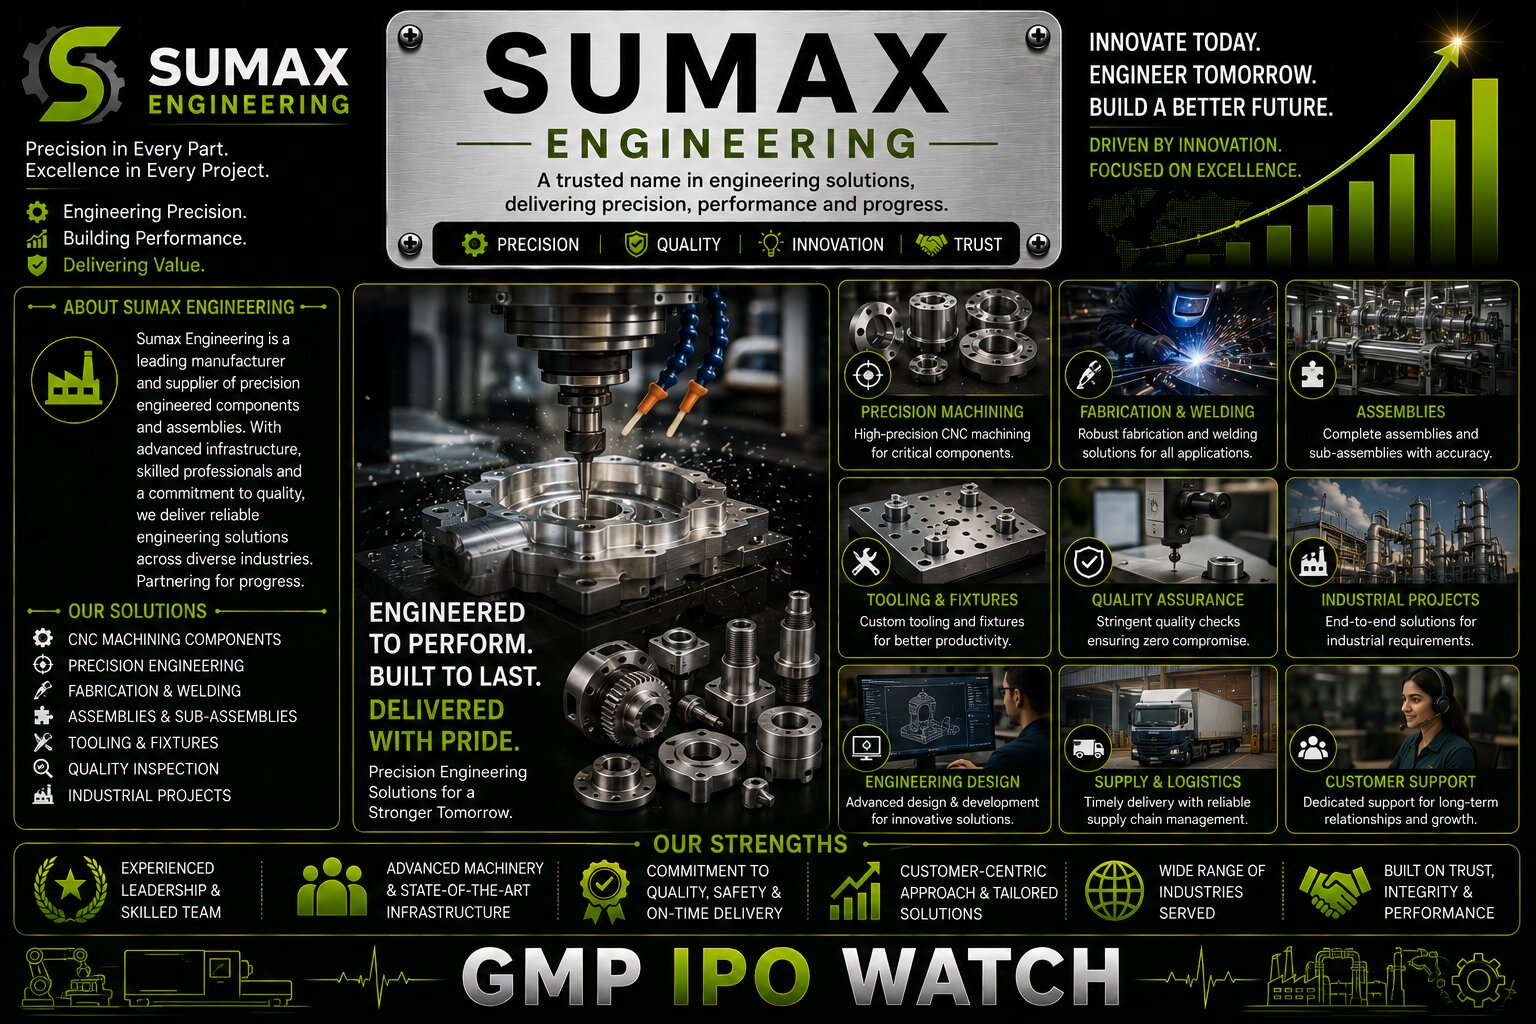
Sumax Engineering IPO 2026 – Day 2 Update
Sumax Engineering Limited's SME IPO is currently open for subscription after bidding started on August 25, 2026.
The IPO will close on August 28, with allotment expected on August 31 and shares scheduled to list on NSE SME on September 2. The price band has been fixed at ₹95 to ₹101 per share.
Unlike a pure fresh issue, Sumax Engineering's IPO combines fresh capital for the company with an Offer for Sale by existing shareholders.
Sumax Engineering IPO Details
| Particular | Details |
|---|---|
| IPO Type | NSE SME IPO |
| Issue Size | ₹53.40 Crore |
| Fresh Issue | ₹43.34 Crore |
| Offer for Sale | ₹10.06 Crore |
| Total Shares | ~52.87 Lakh |
| Price Band | ₹95 – ₹101 |
| Face Value | ₹10 |
| Market Lot | 1,200 Shares |
| Retail Minimum | 2,400 Shares |
| Minimum Investment | ₹2,42,400 |
| IPO Open Date | August 25, 2026 |
| IPO Close Date | August 28, 2026 |
| Allotment Date | August 31, 2026 |
| Refund / Demat | September 1, 2026 |
| Listing Date | September 2, 2026 |
| Listing Platform | NSE SME |
At the upper price band, retail investors need ₹2,42,400 for the minimum application of 2,400 shares.
What Does Sumax Engineering Do?
Sumax Engineering has been operating since 1994 and works in the automotive-products and related manufacturing segment.
Its business covers products used across automotive manufacturing, refinishing and aftermarket applications, including adhesive tapes, die-cut products, polishing compounds, buffing pads, reflective materials, graphics and car-care-related products.
The business therefore has exposure to two important demand channels:
automobile manufacturing → OEM demand
and
vehicles already on the road → aftermarket and car-care demand.
This provides broader market exposure than relying entirely on new-vehicle production.
FY2026 Profit Growth Outpaced Revenue
Sumax Engineering's recent financial numbers show an interesting trend: revenue growth slowed considerably in FY2026, but profitability continued to improve.
| Financial Metric | FY2024 | FY2025 | FY2026 |
|---|---|---|---|
| Total Income | ₹131.54 Cr | ₹147.18 Cr | ₹148.34 Cr |
| EBITDA | ₹11.63 Cr | ₹15.03 Cr | ₹19.08 Cr |
| PAT | ₹7.43 Cr | ₹9.98 Cr | ₹12.76 Cr |
| Net Worth | ₹38.86 Cr | ₹48.84 Cr | ₹61.60 Cr |
| Total Assets | ₹54.00 Cr | ₹66.14 Cr | ₹84.81 Cr |
| Borrowings | ₹6.43 Cr | ₹7.75 Cr | ₹13.06 Cr |
FY2026 total income increased only around 0.8%, from ₹147.18 crore to ₹148.34 crore. PAT, however, increased approximately 27.9%, reaching ₹12.76 crore.
That makes margin sustainability an important part of the IPO story.
Profitability Has Improved
Sumax Engineering's PAT has increased consistently over the last three reported financial years:
₹7.43 crore → ₹9.98 crore → ₹12.76 crore.
Its FY2026 IPO metrics also indicate healthy return ratios.
| KPI | FY2026 |
|---|---|
| EPS | ₹8.66 |
| RoNW | 20.71% |
| ROE | 23.10% |
| ROCE | 23.86% |
| Debt / Equity | 0.21 |
| EBITDA Margin | 12.86% |
| PAT Margin | 8.64% |
| NAV | ₹41.83 |
| Pre-Issue P/E | 11.66x |
| Post-Issue P/E | 15.05x |
The improvement in EBITDA and PAT despite almost flat FY2026 revenue suggests better operating profitability.
Investors should now watch whether these margins can be maintained while the company undertakes its next manufacturing expansion.
Two New Manufacturing Units Are the Main IPO Story
A major portion of the fresh proceeds is earmarked for establishing two proposed manufacturing units.
Use of IPO Proceeds
| Purpose | Amount |
|---|---|
| Rajasthan Manufacturing Unit | ₹4.89 Cr |
| Haryana Manufacturing Unit | ₹16.62 Cr |
| Working Capital | ₹12.00 Cr |
| General Corporate Purposes | Balance |
The first proposed manufacturing unit is planned at the RIICO Industrial Area in Karoli, Rajasthan, while the larger second unit is planned in the Model Economic Township in Jhajjar, Haryana.
Together, approximately ₹21.51 crore is earmarked for construction of these two facilities.
Why the New Plants Matter
The two proposed units could become important to Sumax Engineering's next phase of growth.
The company has recently improved profitability, but FY2026 revenue was almost unchanged from FY2025.
The expansion strategy can therefore be viewed as:
new manufacturing facilities → additional capabilities/capacity → larger customer orders → higher revenue potential.
For investors, the important question is not simply whether the plants are constructed.
The bigger issue is how quickly they achieve meaningful utilisation.
If new capacity remains underutilised, depreciation and operating expenses can increase without a corresponding rise in sales.
₹12 Crore Will Strengthen Working Capital
Sumax Engineering also plans to allocate ₹12 crore toward working-capital requirements.
Manufacturing companies need working capital for:
raw materials → production → inventory → customer sales → receivable collection.
As manufacturing capacity increases, these requirements can also rise.
Fresh IPO capital can therefore help Sumax support larger production volumes without depending entirely on additional short-term borrowing.
Fresh Issue Forms Most of the IPO
The structure of the issue is another important point.
| IPO Component | Amount | Approx. Share |
|---|---|---|
| Fresh Issue | ₹43.34 Cr | 81% |
| Offer for Sale | ₹10.06 Cr | 19% |
| Total Issue | ₹53.40 Cr | 100% |
Around 81% of the IPO represents fresh capital, while approximately 19% is an OFS.
This means most of the money raised through the issue is intended to support Sumax Engineering's business rather than simply provide an exit to existing shareholders.
Borrowings Have Increased
Although Sumax's debt-to-equity ratio remains relatively moderate, borrowings have increased.
| Financial Year | Borrowings |
|---|---|
| FY2024 | ₹6.43 Cr |
| FY2025 | ₹7.75 Cr |
| FY2026 | ₹13.06 Cr |
Borrowings rose by around 68% between FY2025 and FY2026.
The company is not primarily using IPO proceeds for debt repayment, so investors should continue tracking leverage as the new manufacturing facilities are developed.
Automotive Aftermarket Adds Diversification
One useful aspect of Sumax Engineering's business is its exposure to the automotive aftermarket.
OEM demand depends heavily on the number of new vehicles manufactured.
Aftermarket demand, however, can continue throughout the life of a vehicle.
Products associated with:
repair + refinishing + polishing + detailing + maintenance
can generate demand from the existing vehicle population.
As India's vehicle base expands, this can provide a broader long-term market for automotive consumables and related products.
Revenue Growth Is the Key Metric Now
Sumax Engineering has already demonstrated improvement in profitability.
The next question is whether revenue growth can accelerate.
Total income increased from ₹131.54 crore in FY2024 to ₹147.18 crore in FY2025, but then moved only slightly higher to ₹148.34 crore in FY2026.
This makes the upcoming manufacturing expansion especially relevant.
If new facilities help the company secure larger orders, the business could move from a margin-improvement phase toward a combination of revenue and profit growth.
Sumax Engineering IPO GMP
The IPO entered the market with positive unofficial grey-market sentiment.
On its opening day, the reported GMP indicated roughly a 32% potential premium over the upper issue price.
| GMP Indicator | Recent Trend |
|---|---|
| Upper Price Band | ₹101 |
| Opening-Day GMP Indication | ~32% |
| GMP Sentiment | Positive |
| IPO Status | Open |
Since GMP changes frequently and is not an official exchange price, investors should treat it only as a sentiment indicator rather than a guaranteed listing return.
Key Strengths of Sumax Engineering
Sumax Engineering has an operating history of more than three decades and serves the automotive ecosystem through a diversified range of products.
Its financial performance has also improved, with PAT rising from ₹7.43 crore in FY2024 to ₹12.76 crore in FY2026. ROE stood at 23.10% and ROCE at 23.86% for FY2026.
Another notable feature is that roughly 81% of the IPO is fresh capital.
Much of this capital has clearly identified uses involving two new manufacturing facilities and working capital.
Major Risks
The main financial question is whether Sumax can restart stronger revenue growth while maintaining its improved margins.
Other risks include raw-material price volatility, competition in automotive products, dependence on automobile-sector demand, customer concentration, working-capital requirements and execution risk associated with constructing two new manufacturing units.
Borrowings have also increased from ₹7.75 crore in FY2025 to ₹13.06 crore in FY2026.
Because Sumax will list on NSE SME, investors should additionally consider the potential for lower liquidity and higher post-listing volatility compared with mainboard stocks.
What Investors Should Track After Listing
| Metric | Why It Matters |
|---|---|
| Revenue Growth | Expansion momentum |
| New Plant Progress | IPO execution |
| Capacity Utilisation | Return on new facilities |
| EBITDA Margin | Operating efficiency |
| PAT Margin | Profit sustainability |
| OEM Revenue | Auto-industry demand |
| Aftermarket Revenue | Business diversification |
| Working Capital | Funding efficiency |
| Borrowings | Balance-sheet risk |
| Operating Cash Flow | Earnings quality |
| Customer Concentration | Revenue risk |
| ROCE | Return on expansion |
For Sumax Engineering, revenue acceleration and utilisation of the two proposed manufacturing units could become the most important post-IPO indicators.
Final View on Sumax Engineering IPO
The Sumax Engineering IPO is open from August 25 to August 28, 2026, with a price band of ₹95–₹101. The ₹53.40 crore NSE SME offering consists of a ₹43.34 crore fresh issue and ₹10.06 crore OFS.
Financially, Sumax reported FY2026 total income of ₹148.34 crore and PAT of ₹12.76 crore, compared with ₹147.18 crore and ₹9.98 crore respectively in FY2025.
The next growth phase will depend heavily on how the IPO capital is deployed. Around ₹21.51 crore is earmarked for two proposed manufacturing units, while another ₹12 crore will support working capital.
Loading comments...