Tempsens Instruments IPO 2026 – Can a Temperature Sensor Manufacturer Become a Larger Thermal Engineering Platform?
A temperature sensor may look like a relatively small industrial component.
But in many factories, it performs a critical job.
A steel furnace operating at the wrong temperature can damage material.
A petrochemical plant may need continuous temperature monitoring for process safety.
A glass or cement plant may require equipment capable of measuring extreme heat without physical contact.
This is the industrial environment in which Tempsens Instruments (India) Limited operates.
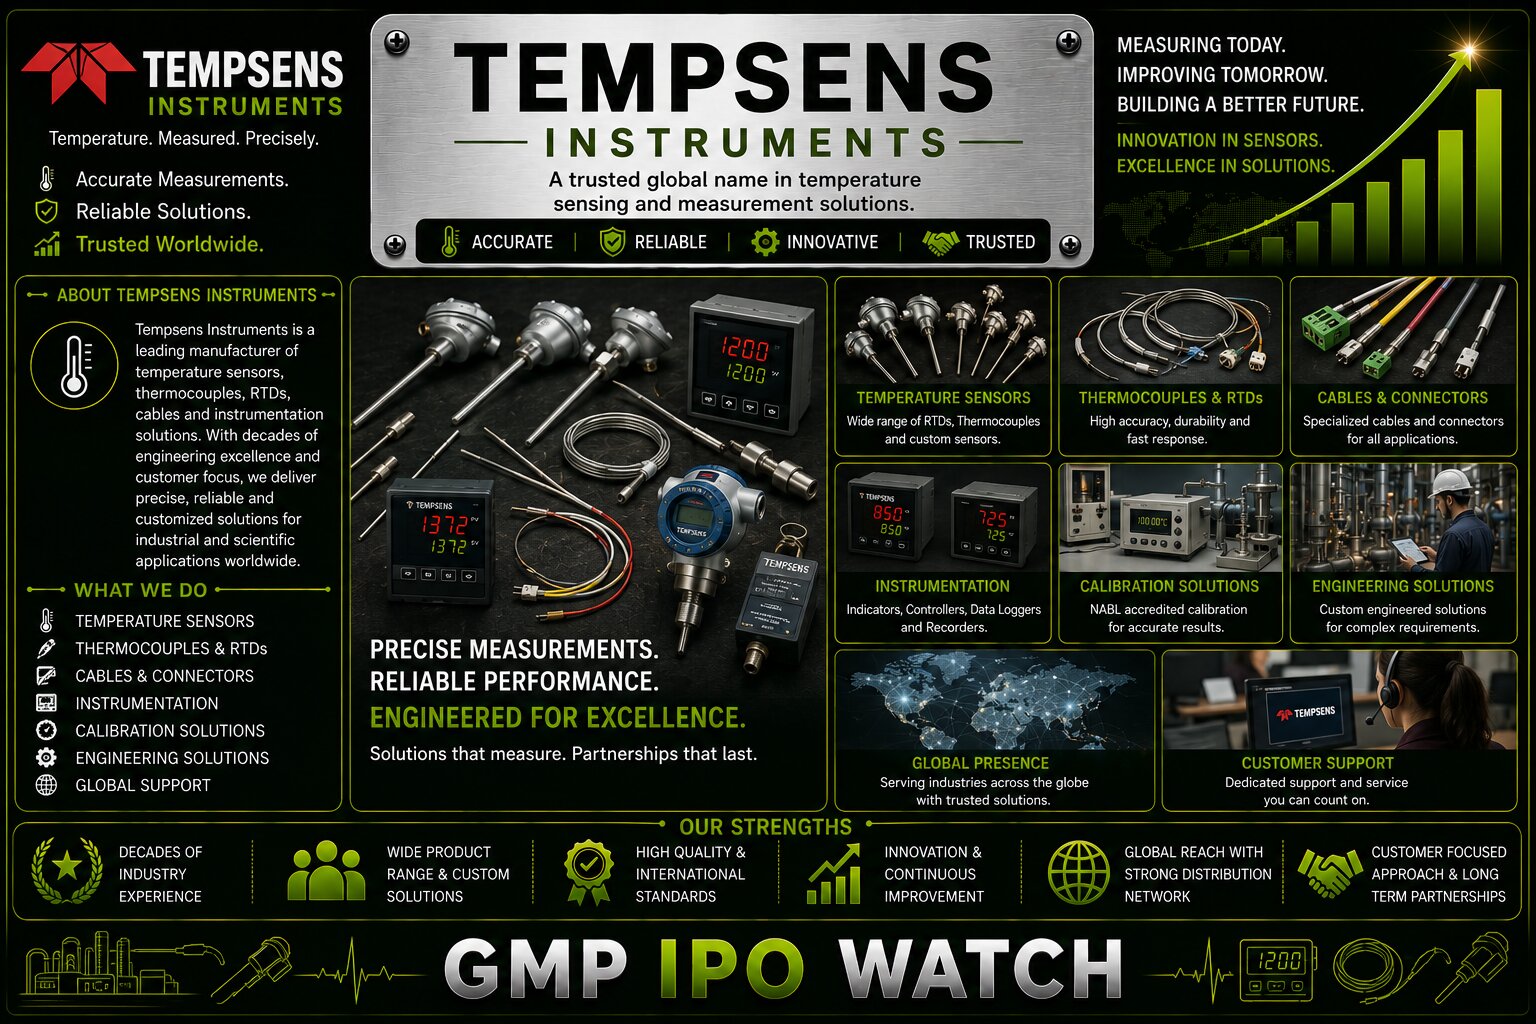
Tempsens manufactures temperature-sensing and broader thermal-engineering products including thermocouples, resistance temperature detectors, thermowells, pyrometers, thermal imagers, industrial heaters, calibration equipment, furnaces and specialised cables.
The company claims to be India's largest manufacturer of contact and non-contact temperature sensors by revenue, with about 10.5% share of the overall temperature-sensor market. It also states that it is the only Indian manufacturer of non-contact temperature sensors, with approximately 21.3% market share in that category in FY2026, based on the Frost & Sullivan report cited in its IPO material.
That makes the investment question broader than simply:
Can Tempsens sell more thermocouples?
The more interesting question is:
Can Tempsens use its sensor leadership, export network, heating products and specialised cables to become a larger integrated thermal-engineering company while protecting its 24%–25% EBITDA margin?
Tempsens Instruments IPO Details
| Particular | Details |
|---|---|
| Company | Tempsens Instruments (India) Ltd. |
| IPO Type | Book Built Mainboard IPO |
| Listing Platform | BSE & NSE |
| Issue Size | ₹650 Crore |
| Fresh Issue | ₹95 Crore |
| OFS | Approx. ₹555 Crore |
| Price Band | ₹285 – ₹300 |
| Face Value | ₹4 Per Share |
| Lot Size | 50 Shares |
| Retail Minimum | 50 Shares |
| Retail Investment | ₹15,000 |
| Anchor Date | August 19, 2026 |
| IPO Open Date | August 20, 2026 |
| IPO Close Date | August 24, 2026 |
| Allotment Date | August 25, 2026 |
| Refund Date | August 27, 2026 |
| Listing Date | August 28, 2026 |
| Lead Managers | ICICI Securities, JM Financial |
| Listing | Mainboard |
The final RHP-stage issue differs from the company's earlier draft structure. The current IPO aims to raise ₹650 crore, comprising a ₹95 crore fresh issue and an OFS of approximately 1.85 crore shares by existing shareholders.
What Does Tempsens Instruments Actually Do?
Tempsens describes itself as a thermal-engineering solutions company.
Its major product categories include:
- Thermocouples
- RTDs
- Thermowells
- Pyrometers
- Thermal imagers
- Industrial heaters
- Temperature calibrators
- Industrial furnaces
- Specialised cables and wires.
This gives Tempsens exposure to several stages of industrial temperature management.
It can help a customer:
measure temperature + heat a process + connect equipment + calibrate instruments.
That broader offering can potentially increase revenue per customer compared with a company selling only one sensor category.
Temperature Measurement Is Mission Critical
In many industries, temperature control directly affects product quality.
Consider steel manufacturing.
If temperature is too low, the process may not perform correctly.
If it is too high, material properties can change or equipment can suffer damage.
Similarly, petrochemical processes often operate within carefully controlled temperature ranges.
A small temperature sensor can therefore influence equipment worth crores of rupees.
This gives product reliability unusually high importance.
Contact and Non-Contact Sensors Serve Different Needs
Tempsens operates across both contact and non-contact temperature measurement.
Contact sensors such as thermocouples and RTDs physically interact with the process or equipment.
Non-contact devices such as pyrometers measure temperature remotely.
Non-contact measurement can be particularly useful when:
- Temperatures are extremely high
- Material is moving
- Physical access is difficult
- Contact could damage the sensor
Tempsens' reported leadership in both categories broadens the industrial applications it can address.
Non-Contact Sensors Could Be a Higher-Technology Opportunity
The company's claimed 21.3% FY2026 share of India's non-contact sensor market is particularly interesting.
Non-contact measurement often involves more sophisticated electronics, optics and signal processing than conventional temperature probes.
That can potentially provide:
- Higher value addition
- Stronger technical differentiation
- Lower commodity-style competition
If this category grows faster than traditional sensors, it could improve Tempsens' product mix.
Tempsens Is Also an Industrial Heating Company
Temperature measurement is only one side of thermal engineering.
Factories also need to generate and control heat.
Tempsens manufactures electrical heating solutions for industrial customers, giving the company exposure to applications where processes need controlled heating rather than measurement alone.
This can create useful cross-selling.
A customer already buying temperature sensors may also need:
- Heaters
- Cables
- Calibration systems
That increases potential wallet share.
Specialised Cables Add Another Business Vertical
Tempsens also operates in specialised cable solutions.
These are not necessarily ordinary household electrical wires.
Industrial applications can require cables capable of handling:
- High temperatures
- Harsh environments
- Special insulation requirements
- Measurement and control signals
The final IPO proceeds specifically include capital expenditure for the company's electrical heating solutions and specialised cable solutions businesses, confirming these are important growth areas.
₹18.1 Crore Is Planned for Expansion Capex
Tempsens intends to use around ₹18.1 crore from the fresh issue toward capital expenditure for its electrical-heating and specialised-cable businesses.
This is relatively small compared with the ₹650 crore headline issue size.
That is because most of the IPO is an OFS.
Only ₹95 crore is fresh capital entering the company.
Investors should therefore distinguish carefully between:
₹650 crore total IPO
and
₹95 crore fresh company capital.
₹55 Crore Will Be Used to Repay Debt
Another major fresh-issue objective is approximately ₹55 crore toward repayment or prepayment of borrowings.
As of July 2026, consolidated outstanding debt was around ₹108.3 crore, according to the current issue reporting.
Repaying ₹55 crore can therefore reduce a substantial portion of that debt.
This could:
- Lower finance costs
- Improve cash flow
- Strengthen the balance sheet
- Provide greater flexibility for future expansion
Debt Reduction Could Improve Earnings Without Revenue Growth
Suppose Tempsens keeps revenue unchanged.
If annual interest costs fall because debt has been repaid, pre-tax profit can still improve.
That makes deleveraging one of the more predictable benefits of the IPO.
This contrasts with expansion capex, where returns depend on future customer demand.
FY2026 Total Income Reached ₹455.86 Crore
Tempsens reported the following recent financial performance:
| Financial Year | Total Income | EBITDA | PAT |
|---|---|---|---|
| FY2024 | ₹278.04 Cr | ₹61.13 Cr | ₹40.92 Cr |
| FY2025 | ₹382.47 Cr | ₹97.32 Cr | ₹62.56 Cr |
| FY2026 | ₹455.86 Cr | ₹113.17 Cr | ₹71.07 Cr |
Revenue from operations separately increased from approximately ₹274.81 crore in FY2024 to ₹378.53 crore in FY2025 and ₹444.88 crore in FY2026.
This shows a clear multi-year growth trajectory rather than a single pre-IPO revenue spike.
FY2026 Revenue Grew Around 17.5%
Revenue from operations increased from approximately:
₹378.53 crore in FY2025
to:
₹444.88 crore in FY2026.
That represents growth of about 17.5%.
PAT increased from ₹62.56 crore to ₹71.07 crore, or approximately 13.6%.
This is slower than several high-growth IPOs currently entering the market.
But slower, steady growth can sometimes be more sustainable.
EBITDA Reached ₹113.17 Crore
FY2026 EBITDA stood at approximately:
₹113.17 crore
compared with:
₹97.32 crore in FY2025
and:
₹61.13 crore in FY2024.
This indicates strong operating profitability.
Tempsens is not merely increasing sales.
It is maintaining significant value addition within its engineering business.
FY2026 EBITDA Margin Was Around 25%
Current prospectus-based KPI reporting places FY2026 EBITDA margin at roughly 24.8%–25.4%, depending on whether total income or revenue from operations is used as the denominator.
Either way, the key message is the same:
Tempsens operates with a mid-20% EBITDA margin.
That is attractive for an industrial manufacturing and engineering company.
The challenge is protecting that margin as the company expands internationally and grows lower-margin product categories.
PAT Margin Was Around 15.6%–16%
FY2026 PAT was approximately ₹71.07 crore.
Against total income of ₹455.86 crore, this gives a PAT margin of around 15.6%.
Current prospectus analyses report the ratio around 15.59%–15.98% depending on the financial basis used.
This remains healthy.
But FY2026 PAT grew more slowly than total income, so margin expansion is not the main investment thesis.
The story is more about:
scale + product breadth + market position.
Projects and OEM Revenue Dominate the Business
One of the most important risks in the offer documents is the company's dependence on Projects/OEM business.
This category contributed approximately:
- ₹174.61 crore in FY2024
- ₹259.58 crore in FY2025
- ₹297.97 crore in FY2026
representing roughly 64%–69% of revenue from operations over these years.
This means a large part of Tempsens' business is connected to customer projects and original-equipment manufacturers.
Why Project/OEM Revenue Can Be Attractive
Large industrial projects can generate significant order values.
If a steel or petrochemical plant is being built or expanded, it may require hundreds or thousands of sensors, cables and heating components.
Tempsens can therefore win meaningful contracts from one project.
This provides strong growth when industrial capex is healthy.
Project Revenue Can Also Be Cyclical
The downside is clear.
Customers can:
- Delay projects
- Reduce capex
- Cancel expansion
- Renegotiate timelines
That can affect order flow.
Tempsens itself identifies reductions or delays in customer capital expenditure as a risk to its Projects/OEM business.
That makes another part of its business particularly important:
MRO demand.
MRO Revenue Could Improve Business Stability
MRO means:
Maintenance, Repair and Operations.
Once a factory is operating, temperature sensors and related components eventually need:
- Replacement
- Calibration
- Repair
- Maintenance
This creates recurring demand from the installed industrial base.
A stronger MRO mix could make Tempsens less dependent on new industrial construction.
For long-term investors, the balance between:
Projects/OEM + MRO
is worth monitoring.
Replacement Demand Can Be a Valuable Moat
Suppose Tempsens sensors are already approved and installed inside a major steel plant.
When replacement is required, the customer may prefer the same supplier because:
- Specifications are already known
- Reliability has been tested
- Engineering teams understand the product
This can create customer stickiness.
Industrial components are often not changed casually when process reliability is critical.
Tempsens Served More Than 1,000 Customers
Between April 2023 and March 2026, Tempsens served more than 1,000 unique customers.
This provides diversification across a reasonably large customer base.
A broad installed customer network is particularly valuable for future:
- Replacement orders
- MRO sales
- Cross-selling
- New plant expansions
This makes the existing customer base an economic asset beyond the current year's revenue.
Exports Reach More Than 80 Countries
Tempsens has exported products to more than 80 countries, including markets such as Germany, Poland and the UAE.
Its corporate profile also describes manufacturing operations across India and international locations and a broad global sales network.
This gives Tempsens a more international profile than many Indian industrial IPOs.
Exports can provide:
- Geographic diversification
- Access to larger industrial markets
- Foreign-currency revenue
But they also create:
- Currency risk
- International competition
- Regulatory complexity
Global Manufacturing Presence Can Help Customers
Tempsens' corporate profile identifies manufacturing presence in countries including India, Indonesia, the UAE and South Korea.
For industrial customers, local or regional manufacturing can improve:
- Delivery times
- Customer service
- Product customisation
It can also reduce dependence on exporting every product from one Indian facility.
That may become increasingly important as Tempsens grows internationally.
Metal and Petrochemical Industries Contribute Over 40% of Revenue
Another important concentration risk appears in the customer end-market mix.
Metal and petrochemical industries together contributed approximately:
₹181.45 crore, or 41.13% of FY2026 revenue from operations.
The same sectors contributed around:
- 42.90% in FY2025
- 41.52% in FY2024.
This concentration has remained remarkably stable.
Why Metals Are a Natural Market for Tempsens
Steel and metal processing involve extreme temperatures.
Applications can include:
- Furnaces
- Melting
- Casting
- Rolling
Reliable temperature measurement is therefore fundamental.
This creates strong natural demand for thermocouples, pyrometers and related thermal equipment.
But it also means Tempsens is exposed to the steel industry's capex cycle.
Petrochemicals Provide Another Important Industrial Market
Petrochemical processes can require continuous measurement and thermal control.
Safety and process efficiency make reliable instrumentation important.
This creates attractive demand.
However, petrochemical investment can also be cyclical and affected by:
- Commodity markets
- Energy prices
- New capacity decisions
Diversifying beyond metals and petrochemicals could therefore improve revenue stability.
Copper and Nickel Are Important Raw Materials
Tempsens' raw-material purchases have significant exposure to copper and nickel.
Together, these represented around 26.05% of total purchases in FY2026, amounting to roughly ₹67.94 crore.
The share was:
- 24.49% in FY2025
- 22.33% in FY2024.
This exposes margins to commodity-price movements.
Commodity Inflation Can Pressure Margins
Suppose copper prices rise sharply.
Tempsens has three options:
- Absorb the increase
- Raise customer prices
- Improve efficiency elsewhere
If contracts have fixed pricing, passing through cost increases may take time.
Therefore, procurement and contract pricing can materially influence margins.
The company's ability to maintain an EBITDA margin around 25% despite commodity exposure is a positive historical feature, but future raw-material volatility remains a risk.
Backward Integration Can Protect Margins
One recent analysis attributes part of Tempsens' margin strength to deeper backward integration in conductor manufacturing.
Vertical integration can help by providing:
- Better cost control
- Supply reliability
- Quality consistency
This can become especially valuable when copper, nickel or specialised components experience supply disruption.
Assets Have Expanded Rapidly
Total assets increased from:
₹271.14 crore in FY2024
to:
₹551.28 crore in FY2025
and:
₹661.05 crore in FY2026.
This indicates a substantial expansion of the business base.
The increase reflects growth, investments and corporate transactions rather than purely organic equipment additions.
Borrowings Have Also Increased
Total borrowings rose from:
₹30.13 crore in FY2024
to:
₹71.83 crore in FY2025
and:
₹77.95 crore in FY2026.
This is one reason the ₹55 crore IPO debt-repayment allocation matters.
Even though borrowings have increased, the company's equity base has also expanded considerably.
Debt-to-Equity Remains Low
Current prospectus-based reporting places Tempsens' FY2026 debt-to-equity ratio around 0.15–0.16×.
That is relatively conservative.
The company is therefore not entering the IPO with a distressed balance sheet.
Debt repayment is more about:
strengthening an already manageable capital structure
than solving a severe leverage problem.
ROCE Is Around 21.6%
Tempsens reports FY2026 ROCE of approximately:
21.61%.
ROE is reported around 13.5%–14.3% depending on the calculation basis.
ROCE is arguably the more useful measure for an industrial company because it evaluates returns generated from the capital deployed across the business.
A 20%+ ROCE is healthy.
ROE Has Declined as the Equity Base Expanded
IPOPlatform reports ROE moving from approximately:
- 19.98% in FY2024
- 14.54% in FY2025
- 14.30% in FY2026.
The business remains profitable, but equity has grown faster than PAT.
This means future earnings growth must continue for returns on equity to improve.
Acquisition Strategy Adds Another Growth Route
In April 2026, Tempsens announced the acquisition of a majority stake in Techin Gauges India, subsequently renamed Tempsens Measurement and Control.
This demonstrates that management is willing to expand through acquisitions as well as organic growth.
Acquisitions can:
- Add products
- Add customers
- Add technology
But they also introduce integration and capital-allocation risk.
Investors should track whether acquired businesses generate attractive returns.
Valuation Is Around 35× Earnings
At the ₹300 upper price band, one current prospectus-based valuation source estimates:
- Market capitalisation: ₹2,514.98 crore
- P/E: 35.38×
- EV/EBITDA: 22.66×
- P/B: 2.19×.
Another calculation puts P/E near 35.9× depending on the EPS basis used.
This is not a low headline valuation.
Investors are paying a premium for:
- Market leadership
- Strong margins
- Export presence
- Broad product capabilities
That increases the importance of sustained earnings growth.
The IPO Is OFS Heavy
This is one of the most important structural features.
The ₹650 crore offer contains only ₹95 crore of fresh issue, while approximately ₹555 crore is OFS.
That means roughly 85% of the IPO does not go directly into the company.
OFS proceeds go to selling shareholders.
This is not automatically negative, but investors should understand that the IPO is not primarily a ₹650 crore growth-capital raise.
Selling Shareholders Are Monetising Part of Their Holdings
The OFS includes shares sold by promoters and other existing shareholders.
For investors, this makes the use of the ₹95 crore fresh portion particularly important.
It is concentrated on relatively clear objectives:
₹55 crore debt repayment + ₹18.1 crore growth capex + general corporate purposes.
Tempsens Instruments IPO GMP Today
As of August 18, 2026, the current Mint live IPO tracker does not show an active GMP quote for Tempsens Instruments.
The IPO has not opened yet, so grey-market activity may develop further as the August 20 subscription date approaches.
Investors should avoid treating any isolated unofficial quote as established market sentiment until more consistent data appears.
Tempsens Instruments IPO Subscription Today
There is no public subscription data today.
The public offer opens on:
August 20, 2026
and closes:
August 24, 2026.
Anchor allocation is scheduled for August 19.
Therefore, any public QIB, NII or retail subscription number shown before August 20 would not represent the actual public bidding process.
Anchor Allocation Will Be the First Demand Indicator
Anchor bidding takes place tomorrow, August 19.
The anchor book can provide the first institutional-demand signal ahead of public bidding.
However, anchor demand should not replace fundamental analysis.
Tempsens is being offered at a valuation around the mid-30s P/E, so investors still need to evaluate whether future growth justifies that multiple.
Competitive Strengths
Tempsens enters the IPO with several notable strengths.
It claims leadership in India's contact and non-contact temperature-sensor industry, with around 10.5% overall sensor market share and approximately 21.3% non-contact market share in FY2026.
It has a diversified thermal-engineering portfolio spanning:
temperature sensing + heating systems + specialised cables + calibration equipment.
The company has served more than 1,000 customers and exports to more than 80 countries.
Financially, FY2026 total income reached ₹455.86 crore, EBITDA ₹113.17 crore and PAT ₹71.07 crore.
Margins remain strong, with EBITDA around 25% and PAT margin around 15%–16%.
Major Risks
Projects/OEM Concentration
Around 67.55% of FY2026 operating revenue came from Projects/OEM business.
Delays in customer capex can materially affect revenue.
Metal and Petrochemical Exposure
These industries together generated more than 41% of FY2026 operating revenue.
Copper and Nickel Prices
The two materials represented around 26% of FY2026 purchases.
OFS-Heavy Issue
Only ₹95 crore of the ₹650 crore IPO is fresh capital.
Valuation
The post-issue valuation is around 35× earnings on current prospectus-based calculations.
International Operations
Exports and overseas operations create currency, regulatory and execution risks.
Acquisition Integration
Recent acquisitions need to generate adequate returns on invested capital.
What Could Drive Tempsens' Next Growth Phase?
Several opportunities can support future growth.
Non-Contact Temperature Sensors
A technically differentiated segment in which Tempsens claims a strong market position.
Specialised Cables
IPO-funded capex can expand manufacturing capabilities.
Electrical Heating Solutions
Broadens the business beyond measurement.
MRO Revenue
Replacement and maintenance orders can reduce dependence on new projects.
International Markets
80+ export countries provide a broad addressable market.
Cross-Selling
Existing sensor customers can potentially purchase heating, cable and calibration products.
Acquisitions
Targeted transactions can broaden product and technology capabilities.
What Investors Should Track After Listing
| Metric | Why It Matters |
|---|---|
| Revenue Growth | Demand sustainability |
| Projects/OEM Share | Capex dependence |
| MRO Revenue | Recurring-demand quality |
| EBITDA Margin | Pricing and efficiency |
| Export Revenue | Global expansion |
| Copper/Nickel Costs | Margin pressure |
| Operating Cash Flow | Profit quality |
| ROCE | Capital efficiency |
| Debt | ₹55 Cr repayment impact |
| New Capex Utilisation | Expansion returns |
The most interesting long-term improvement would be an increasing contribution from MRO, replacement and cross-selling revenue, because those categories could make the business less dependent on large industrial projects.
The Most Important Post-IPO Equation
Tempsens' strongest growth path looks like:
sensor leadership → larger installed base → replacement/MRO demand → cross-selling heating and cables → higher recurring revenue → stronger cash generation.
The weaker outcome would be:
higher project exposure → customer capex slowdown → delayed orders → slower revenue growth while valuation remains high.
That is the central risk-reward equation.
Should Investors Consider Tempsens Instruments IPO?
The positive case includes:
- Leadership position in temperature sensors
- Strong non-contact sensor presence
- FY2026 revenue from operations around ₹444.88 crore
- FY2026 PAT of ₹71.07 crore
- EBITDA margin near 25%
- ROCE above 21%
- More than 1,000 customers
- Exports to 80+ countries
- Low debt-to-equity
- IPO-funded debt reduction and manufacturing capex.
The caution case includes:
- Roughly two-thirds of revenue from Projects/OEM business
- High metal and petrochemical exposure
- Copper and nickel commodity risk
- OFS-heavy IPO structure
- Valuation around 35× earnings
- Need to maintain margins as international operations expand.
Tempsens should therefore be analysed as a specialised thermal-engineering platform with strong industrial positioning, rather than simply as another electrical-equipment manufacturer.
Final View on Tempsens Instruments IPO 2026
The Tempsens Instruments IPO opens on August 20, 2026 and closes August 24. Anchor allocation takes place on August 19, while listing is tentatively scheduled for August 28 on BSE and NSE. The ₹650 crore issue has a price band of ₹285–₹300 per share and lot size of 50 shares.
The final offer contains approximately ₹95 crore fresh issue and ₹555 crore OFS. Of the fresh proceeds, around ₹55 crore will repay borrowings and ₹18.1 crore will fund capex for electrical-heating and specialised-cable operations.
Financially, Tempsens enters the IPO from a strong position.
Total income increased from approximately ₹278.04 crore in FY2024 to ₹382.47 crore in FY2025 and ₹455.86 crore in FY2026, while PAT climbed from ₹40.92 crore to ₹62.56 crore and then ₹71.07 crore. FY2026 EBITDA reached approximately ₹113.17 crore.
The company's biggest operating advantage is its specialised market position.
Tempsens claims to be India's largest contact and non-contact temperature-sensor manufacturer by revenue, serves more than 1,000 customers and exports across more than 80 countries.
But investors should pay close attention to the composition of revenue.
Projects/OEM orders contributed around 67.55% of FY2026 operating revenue, while metal and petrochemical industries accounted for roughly 41.13%.
This creates exposure to industrial-capex cycles.
The long-term opportunity is therefore to increase the contribution of:
MRO + replacement sensors + heating solutions + specialised cables + international sales.
Current valuation is also not inexpensive, with one prospectus-based calculation placing the issue around 35.4× FY2026 earnings at the upper band.
As of August 18, there is no public subscription data because bidding has not started, and current mainstream live IPO tracking does not show an active GMP quote.
Loading comments...