LCC Projects IPO Overview
LCC Projects IPO is entering its final day of subscription today, September 11, 2026. The mainboard issue opened on September 9 with a price band of ₹139 to ₹146 per share and is scheduled to list on both the NSE and BSE.
The company is looking to raise ₹427.14 crore through a combination of a fresh issue and an offer for sale. The fresh issue is worth ₹258 crore, while existing shareholders are selling shares worth ₹169.14 crore.
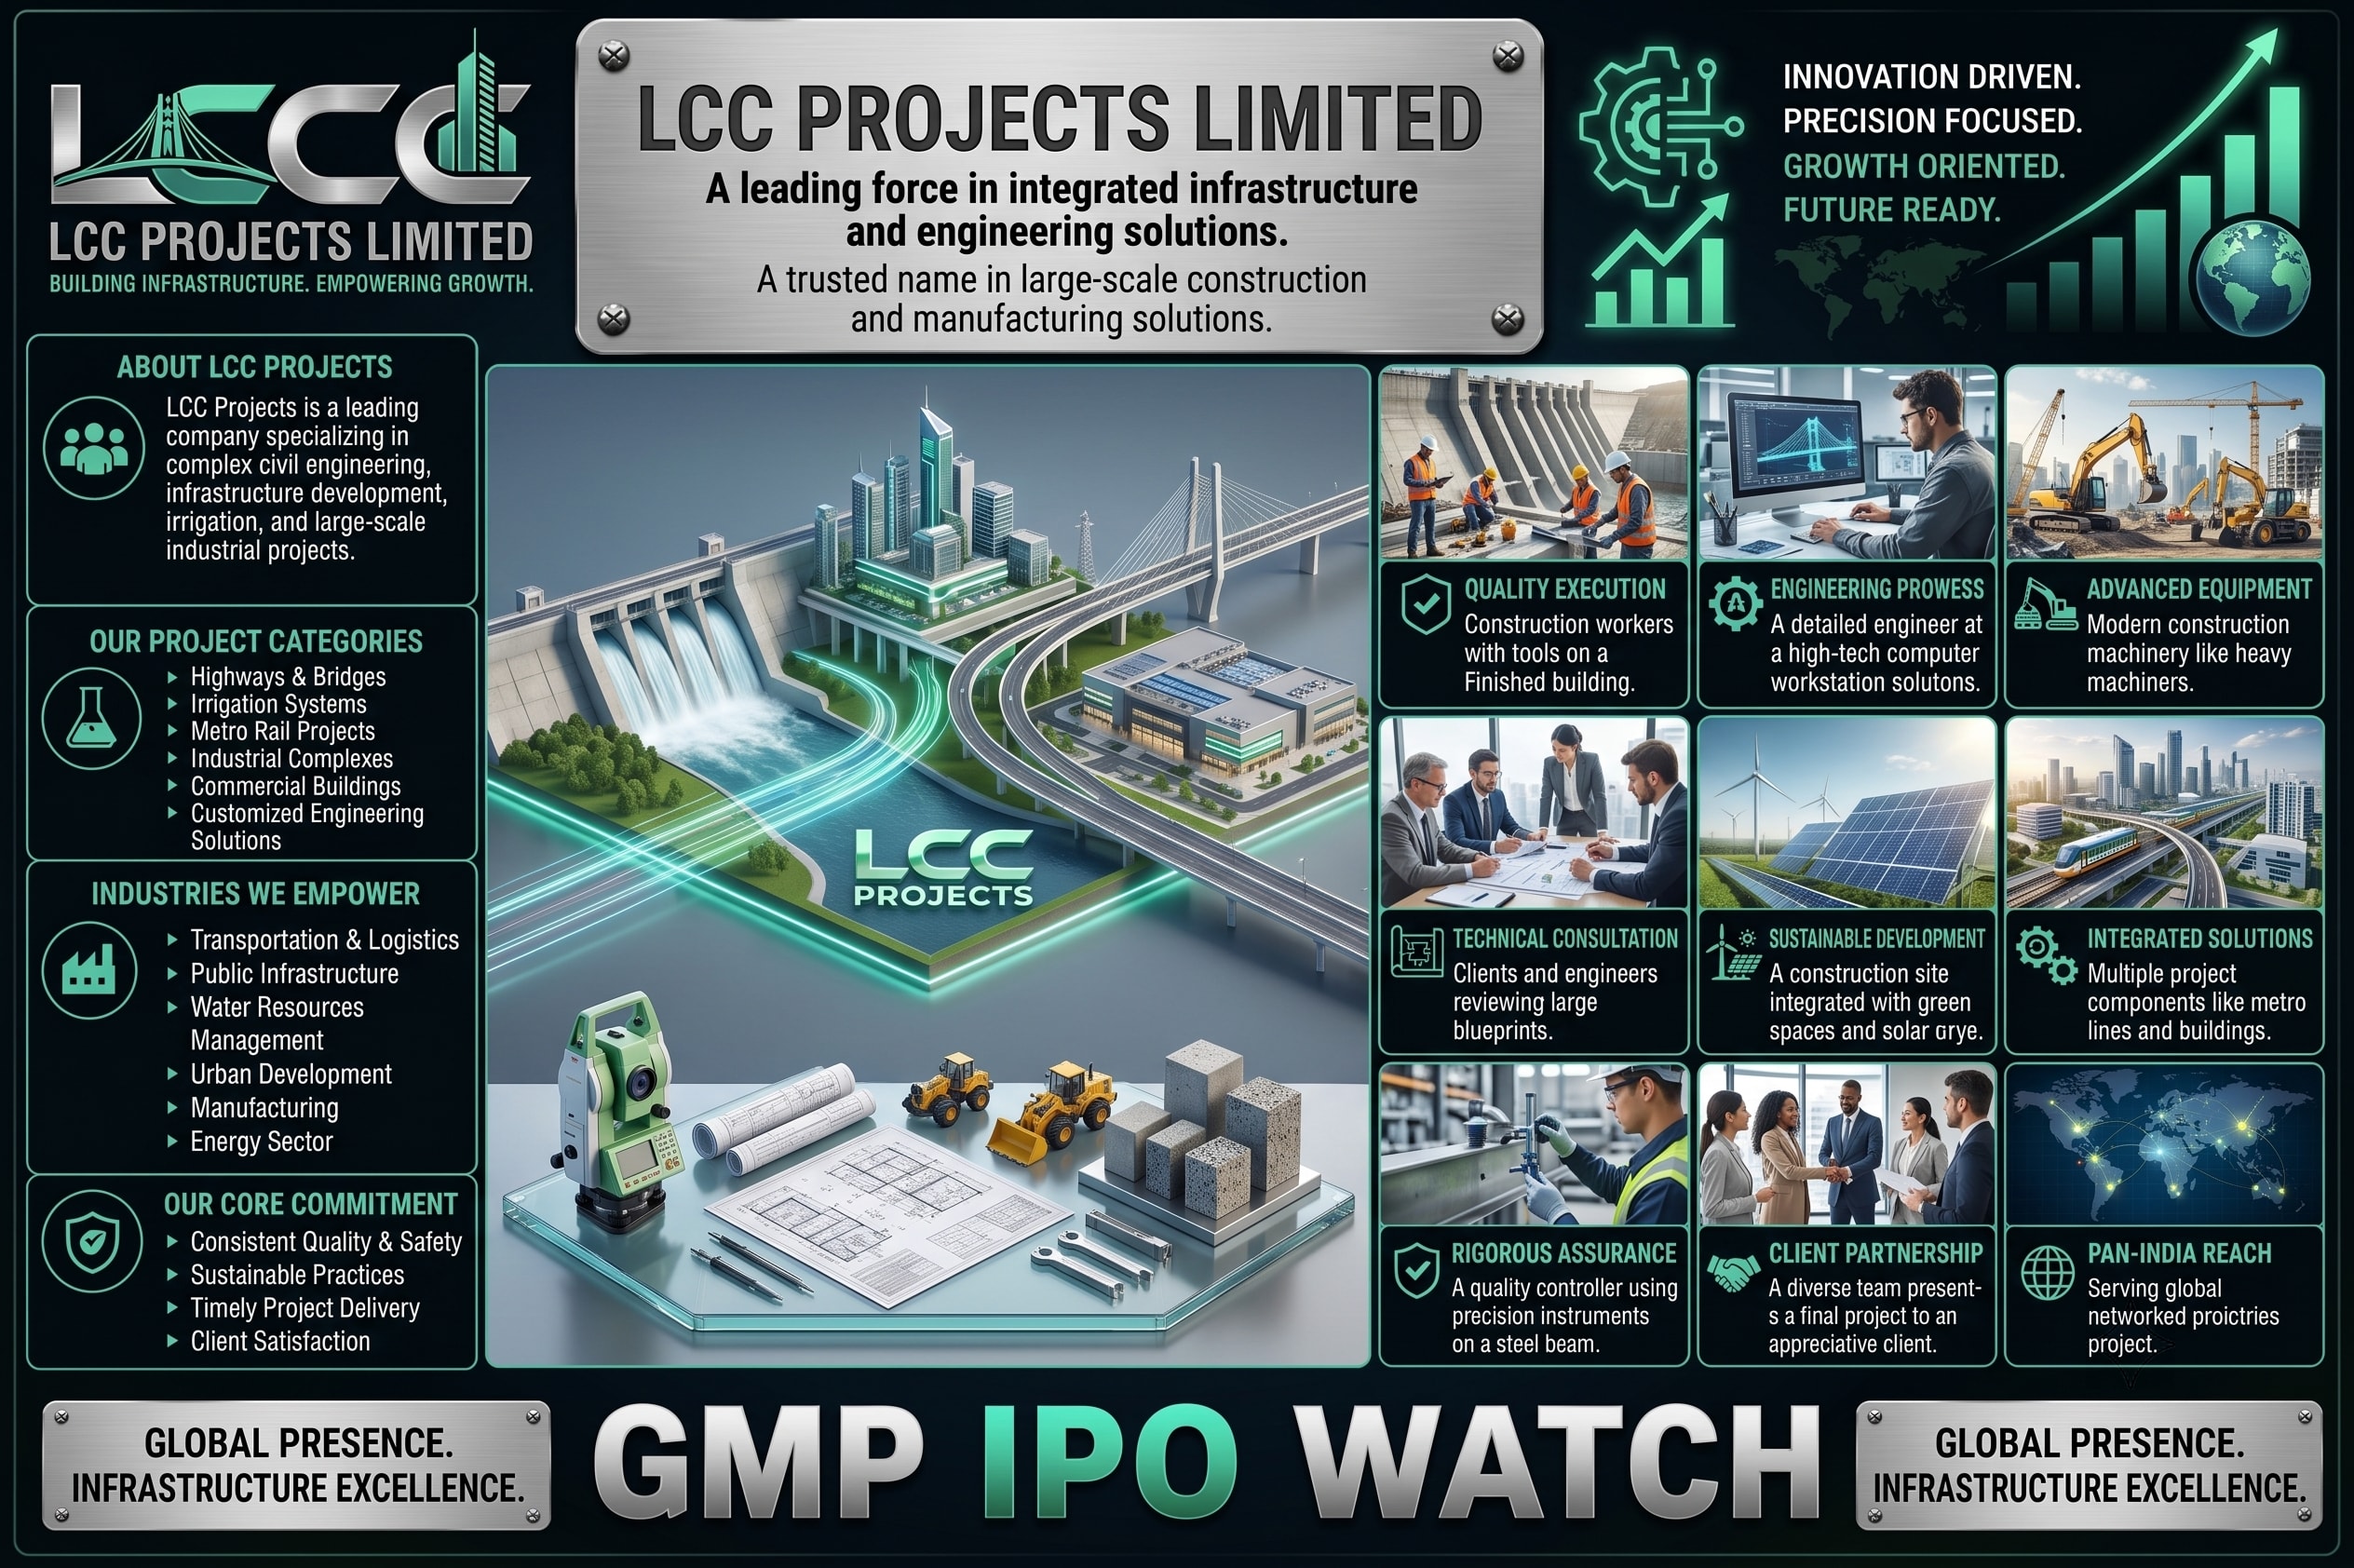
LCC Projects is an engineering, procurement and construction (EPC) company with a major focus on irrigation and water-supply infrastructure projects. Its work includes dams, barrages, canals, hydraulic structures, lift irrigation projects and pipe distribution networks.
The company has expanded its operations across 12 Indian states and had an order book of around ₹7,953 crore across 103 projects as of March 31, 2026.
LCC Projects IPO Details
| Particular | Details |
|---|---|
| IPO Open Date | 9 September 2026 |
| IPO Close Date | 11 September 2026 |
| Price Band | ₹139 – ₹146 |
| Issue Size | ₹427.14 Cr |
| Fresh Issue | ₹258 Cr |
| Offer for Sale | ₹169.14 Cr |
| Face Value | ₹5 |
| Lot Size | 102 Shares |
| Minimum Investment | ₹14,892 |
| Issue Type | Book Built |
| Listing | NSE & BSE |
| Allotment | 15 September 2026 |
| Refund | 16 September 2026 |
| Demat Credit | 16 September 2026 |
| Listing Date | 17 September 2026 |
| Registrar | KFin Technologies |
| Lead Manager | Motilal Oswal Investment Advisors |
At the upper price of ₹146, one lot of 102 shares requires an investment of ₹14,892. Retail investors can apply for up to 13 lots within the retail category.
LCC Projects IPO GMP Today
The grey-market premium for LCC Projects has remained positive during the IPO period, although different market trackers are reporting different figures.
As of September 11, some trackers have reported a GMP of around ₹40–₹51 per share, while one tracker recorded a high of ₹50 during the day.
Using a GMP of ₹45 against the upper IPO price of ₹146 gives an indicative grey-market price of around ₹191.
| Particular | Value |
|---|---|
| Upper IPO Price | ₹146 |
| Indicative GMP | ~₹45 |
| Estimated GMP Price | ~₹191 |
| Indicative Premium | ~30.82% |
| Gain Per Lot at ₹45 GMP | ~₹4,590 |
GMP is unofficial and unregulated. It can change quickly and should not be treated as a guaranteed listing price.
LCC Projects IPO Subscription Status
The IPO has received strong demand as the subscription period has progressed.
The latest available Day 2 figures showed the issue subscribed 3.84 times overall by the end of September 10. QIB subscription stood at 1.16x, NII at 5.33x and retail at 4.69x.
| Category | Subscription |
|---|---|
| QIB | 1.16x |
| NII | 5.33x |
| Retail | 4.69x |
| Overall | 3.84x |
The final Day 3 subscription figure can rise further before bidding closes today. The NII category has been particularly strong, while institutional participation has crossed the 1x mark.
LCC Projects IPO Lot Size and Investment
The lot size is 102 shares at the upper price of ₹146.
| Lots | Shares | Investment |
|---|---|---|
| 1 Lot | 102 | ₹14,892 |
| 2 Lots | 204 | ₹29,784 |
| 5 Lots | 510 | ₹74,460 |
| 10 Lots | 1,020 | ₹1,48,920 |
| 13 Lots | 1,326 | ₹1,93,596 |
The relatively low minimum application amount makes LCC Projects accessible to retail investors compared with several SME IPOs.
LCC Projects IPO Important Dates
The issue closes on September 11. The tentative basis of allotment is scheduled for September 15, followed by refund initiation and demat credit on September 16. Listing is expected on September 17.
| Particular | Date |
|---|---|
| IPO Opens | 9 September 2026 |
| IPO Closes | 11 September 2026 |
| Allotment | 15 September 2026 |
| Refund | 16 September 2026 |
| Demat Credit | 16 September 2026 |
| Listing | 17 September 2026 |
About LCC Projects
LCC Projects is a Gujarat-based multidisciplinary EPC company primarily engaged in irrigation and water-supply infrastructure.
The company was originally established as a partnership firm under the name Laxmi Construction Co. and was subsequently converted into LCC Projects Private Limited in 2017. Over the years, it expanded into multiple states and developed experience in large infrastructure projects.
Its capabilities cover:
- Dams
- Barrages
- Weirs
- Canals
- Hydraulic structures
- Lift irrigation systems
- Water-supply schemes
- Pipe distribution networks
- Metro-related work
- Road projects
- Mining-related infrastructure
- Renewable-energy projects
The company has also established a manufacturing unit at Jaspur, Gujarat, for precast concrete solutions.
LCC Projects Business Model
LCC Projects primarily earns revenue by executing EPC contracts for government departments, public-sector organisations and other infrastructure customers.
Irrigation and water-supply projects remain the company's core business. These projects generally involve design, procurement, construction and execution of large infrastructure assets.
Government-related business is particularly important to the company. Irrigation and water-supply projects contributed around 87.44% of FY2026 revenue, while government departments accounted for approximately 89.34% of revenue.
This provides access to large infrastructure opportunities but also creates dependence on government spending, project approvals and payment cycles.
LCC Projects Order Book
One of the biggest attractions of the LCC Projects story is its order book.
As of March 31, 2026, the company had 103 projects with an order book of approximately ₹7,953.18 crore. This is more than twice its FY2026 revenue and provides visibility for future execution.
Three of the company's largest projects included:
| Project | Approx. Value |
|---|---|
| Sondwa Lift Micro Irrigation Project | ₹1,534.95 Cr |
| Sidhi Bansagar Multi-Village Scheme | ₹1,525.14 Cr |
| Gandhi Sagar 1 Multi-Village Scheme | ₹1,153.90 Cr |
The company expanded its geographical presence from eight states to 12 states during FY2026, which can help diversify its project pipeline.
LCC Projects Revenue Mix
Irrigation and water infrastructure remain the dominant source of revenue.
The concentration gives LCC Projects strong expertise in a specialised infrastructure segment, but it also means the company remains exposed to government infrastructure spending and changes in project execution.
The company's order book is similarly concentrated toward government-related projects, with government departments accounting for roughly 79.07% of the order book as of March 31, 2026.
LCC Projects Financial Performance
LCC Projects has delivered significant growth in revenue and profitability over the last three financial years.
Total income increased from ₹2,449.79 crore in FY2024 to ₹2,941.01 crore in FY2025 and ₹3,639.45 crore in FY2026.
Profit after tax increased from ₹122 crore in FY2024 to ₹223.63 crore in FY2025 and ₹286.44 crore in FY2026.
| Financial Year | Total Income | PAT |
|---|---|---|
| FY2024 | ₹2,449.79 Cr | ₹122.00 Cr |
| FY2025 | ₹2,941.01 Cr | ₹223.63 Cr |
| FY2026 | ₹3,639.45 Cr | ₹286.44 Cr |
The company's FY2026 revenue increased by roughly 24% year-on-year, while PAT increased by approximately 28%, showing continued growth in both scale and earnings.
LCC Projects EBITDA and Margins
EBITDA has also increased substantially.
| Particular | FY2024 | FY2025 | FY2026 |
|---|---|---|---|
| EBITDA | ₹241.37 Cr | ₹401.04 Cr | ₹519.90 Cr |
| EBITDA Margin | — | — | ~14.44% |
| PAT | ₹122.00 Cr | ₹223.63 Cr | ₹286.44 Cr |
| EPS | ₹4.48 | ₹8.18 | ₹10.42 |
The FY2026 EBITDA of ₹519.90 crore represents a significant increase over FY2025. The company reported an FY2026 ROE of about 32.24% and ROCE of around 27.13%.
LCC Projects Balance Sheet
The company's expansion has also been accompanied by higher borrowings.
Total borrowings increased from around ₹422 crore in FY2024 to ₹649.55 crore in FY2025 and ₹860.65 crore in FY2026.
| Particular | FY2024 | FY2025 | FY2026 |
|---|---|---|---|
| Net Worth | ₹382.83 Cr | ₹604.99 Cr | ₹888.41 Cr |
| Total Borrowings | ₹422.30 Cr | ₹649.55 Cr | ₹860.65 Cr |
| Total Assets | ₹1,129.99 Cr | ₹1,727.46 Cr | ₹2,447.54 Cr |
The increase in debt is one reason the company plans to use a substantial portion of the fresh IPO proceeds for debt repayment.
LCC Projects IPO Objectives
The fresh issue will provide ₹258 crore to the company. A major portion is planned for reducing outstanding borrowings.
| Particular | Amount |
|---|---|
| Debt Repayment / Prepayment | ₹180 Cr |
| Purchase of Equipment | ₹14.69 Cr |
| General Corporate Purposes | Balance |
| Fresh Issue | ₹258 Cr |
| OFS | ₹169.14 Cr |
Approximately ₹180 crore, or the majority of the fresh issue, is earmarked for repayment or prepayment of borrowings. Another ₹14.69 crore will be used to purchase equipment.
The ₹169.14 crore OFS component will go to the selling shareholders rather than the company.
LCC Projects IPO Valuation
At the upper price of ₹146, available IPO analysis places the company's post-issue market capitalisation at around ₹4,200 crore.
Based on FY2026 earnings, the post-issue P/E is around the mid-teens according to offer-document-based calculations. The company reported FY2026 EPS of approximately ₹10.42.
| Particular | Details |
|---|---|
| Upper IPO Price | ₹146 |
| FY2026 EPS | ~₹10.42 |
| FY2026 PAT | ₹286.44 Cr |
| FY2026 ROE | ~32.24% |
| FY2026 ROCE | ~27.13% |
| Debt / Equity | ~0.97x |
| Post-Issue P/E | ~14.8x |
The valuation needs to be assessed alongside the company's order book, earnings growth, debt levels and dependence on government infrastructure projects.
LCC Projects IPO Anchor Investors
LCC Projects raised approximately ₹128.14 crore from anchor investors before the public issue opened.
The company allotted around 87.76 lakh shares at ₹146 per share to 11 anchor investors.
Anchor participation provides an indication of institutional interest in the issue, although it does not guarantee the stock's listing or long-term performance.
LCC Projects IPO Strengths
Large order book: The ₹7,953 crore order book provides significant revenue visibility.
Strong financial growth: Revenue and PAT have increased consistently over the last three years.
Government infrastructure exposure: The company participates in large irrigation and water-supply projects where long-term infrastructure spending can create opportunities.
Geographical expansion: Operations have expanded across 12 states.
Specialised EPC experience: The company has experience executing technically complex irrigation and water infrastructure projects.
Improving profitability: FY2026 EBITDA and PAT both increased substantially.
Debt reduction: A large portion of the fresh IPO proceeds is planned for repayment of borrowings.
LCC Projects IPO Risks
The company also has several risks that investors should consider.
Government dependence: A large portion of revenue and order book comes from government-related customers. Changes in government spending or project approvals could affect growth.
Customer concentration: The top 10 customers accounted for around 72.30% of operating revenue, creating concentration risk.
Debt levels: Borrowings have increased alongside business expansion, although the IPO intends to reduce debt.
Geographic concentration: Gujarat and Madhya Pradesh remain important markets for the company.
Working-capital pressure: EPC businesses can face delays in receivables and significant unbilled revenue, which can affect cash flow.
Project execution: Delays in obtaining approvals, land, materials or payments can affect project schedules and margins.
Government policy: Changes in infrastructure programmes and schemes can influence future project opportunities.
LCC Projects IPO Review
LCC Projects offers investors exposure to India's infrastructure and water-management spending through an established EPC business.
The strongest part of the investment story is the combination of ₹7,953 crore order book, growing revenue, rising profitability and operations across 12 states. FY2026 revenue reached around ₹3,639 crore while PAT increased to ₹286 crore.
The IPO also provides an opportunity for the company to strengthen its balance sheet. Of the ₹258 crore fresh issue, ₹180 crore is earmarked for debt repayment or prepayment.
However, investors should not overlook the company's dependence on government contracts, customer concentration, higher borrowings and working-capital requirements.
The positive GMP and strong subscription are supportive short-term signals, but the company's order execution, cash flows and ability to maintain margins will be more important for long-term investors.
What Investors Should Watch
After listing, investors should track:
- Order-book growth.
- New project wins.
- Execution of existing contracts.
- Government infrastructure spending.
- Revenue growth.
- EBITDA margins.
- Debt reduction.
- Receivables and operating cash flow.
- Customer concentration.
- Geographic diversification.
- Precast concrete manufacturing expansion.
These factors will help determine whether the company's large order book can translate into sustainable earnings and cash generation.
LCC Projects IPO Key Highlights
| Particular | Details |
|---|---|
| IPO Price Band | ₹139 – ₹146 |
| Issue Size | ₹427.14 Cr |
| Fresh Issue | ₹258 Cr |
| OFS | ₹169.14 Cr |
| Latest GMP | ~₹45* |
| Indicative GMP Price | ~₹191* |
| Lot Size | 102 Shares |
| Minimum Investment | ₹14,892 |
| Day 2 Subscription | 3.84x |
| Order Book | ₹7,953 Cr |
| FY2026 Revenue | ₹3,639.45 Cr |
| FY2026 PAT | ₹286.44 Cr |
| IPO Closes | 11 September 2026 |
| Allotment | 15 September 2026 |
| Listing | 17 September 2026 |
| Exchange | NSE & BSE |
| Business | EPC – Irrigation & Water Infrastructure |
*GMP is unofficial and can change before listing.
Conclusion
LCC Projects IPO is a ₹427.14 crore mainboard issue from a Gujarat-based EPC company focused mainly on irrigation and water-supply infrastructure.
The company's ₹7,953 crore order book, 103 ongoing projects, 12-state presence and strong FY2026 financial growth are key positives. Revenue increased to ₹3,639.45 crore and PAT reached ₹286.44 crore in FY2026.
The fresh issue also has a clear balance-sheet objective, with ₹180 crore planned for debt repayment and ₹14.69 crore for equipment purchases.
At the same time, investors should carefully evaluate government dependence, customer concentration, debt, working-capital requirements and project-execution risks. The current GMP indicates positive market sentiment, but GMP should not be considered a guaranteed listing return.
The IPO closes today, September 11, 2026, with allotment expected on September 15 and listing scheduled for September 17, 2026.
Disclaimer: Grey Market Premium is unofficial and can change at any time. GMP-based listing estimates are not guaranteed. IPO information is provided for informational purposes only and should not be considered investment advice.
Loading comments...