
Lumino Industries IPO 2026 – Final Day Update
The Lumino Industries IPO has entered its final bidding day today, August 31, 2026. The mainboard issue opened on August 27 and will close today, with shares expected to list on both BSE and NSE on September 3.
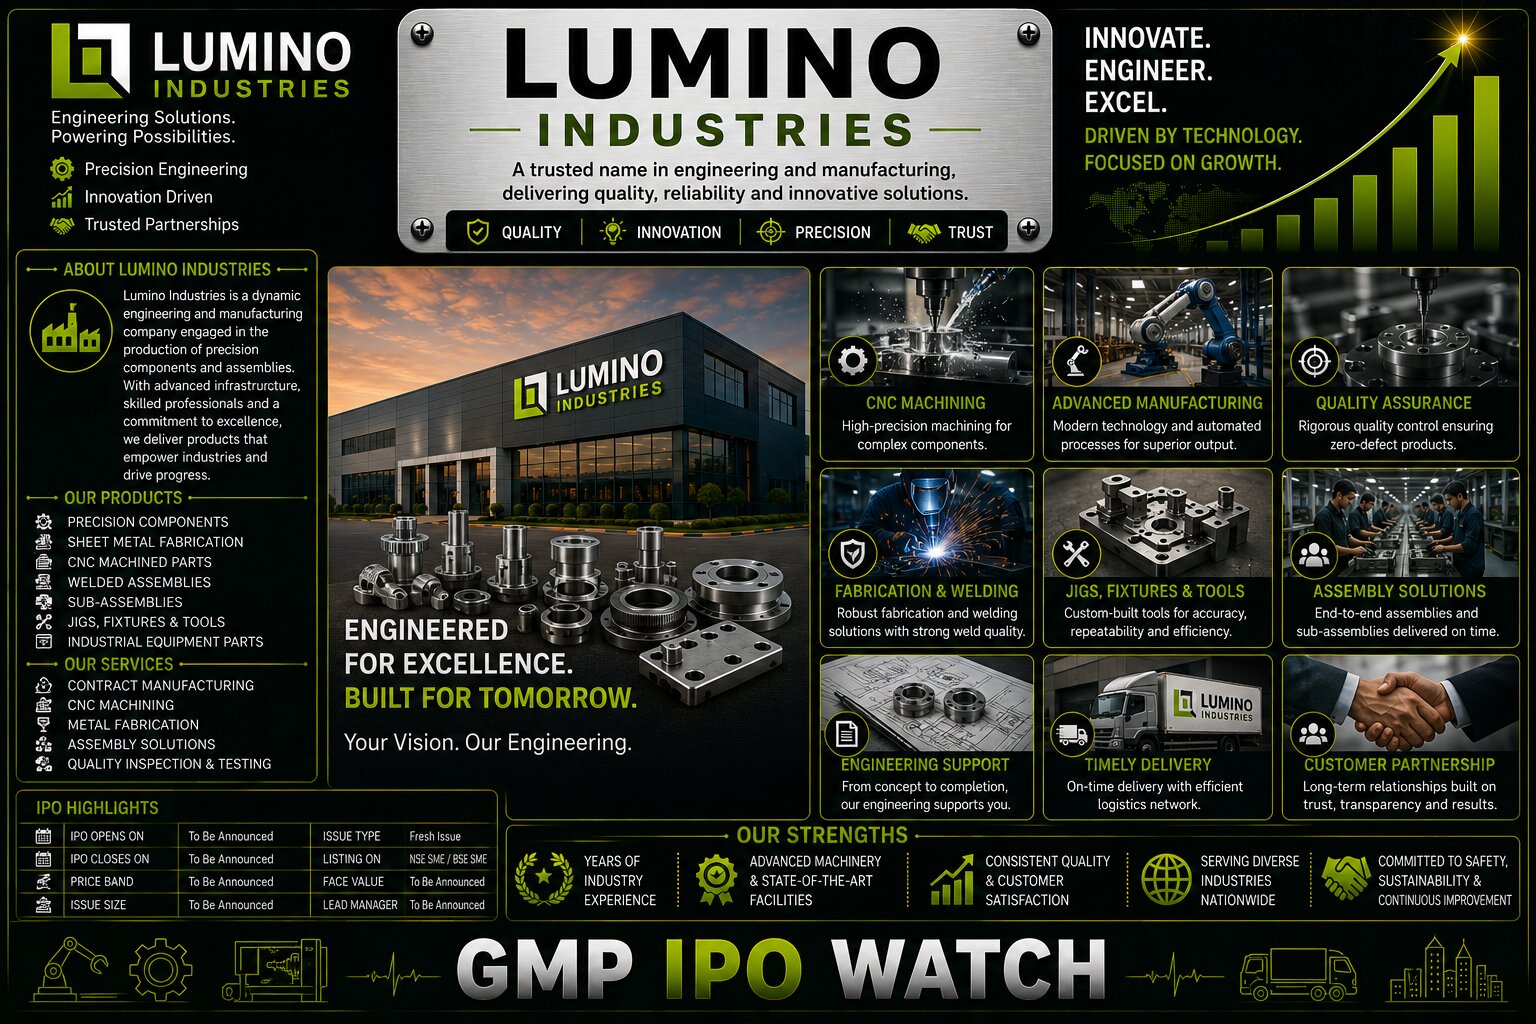
Lumino Industries is an integrated power transmission and distribution products manufacturer and EPC company, supplying conductors, power cables, electrical wires and specialised products while also executing infrastructure projects.
Lumino Industries IPO Details
| Particular | Details |
|---|---|
| IPO Type | Mainboard IPO |
| Issue Size | ₹700 Crore |
| Fresh Issue | ₹500 Crore |
| Offer for Sale | ₹200 Crore |
| Total Shares | ~8.54 Crore |
| Price Band | ₹78 – ₹82 |
| Face Value | ₹5 |
| Lot Size | 182 Shares |
| Minimum Investment | ₹14,924 |
| IPO Open Date | August 27, 2026 |
| IPO Close Date | August 31, 2026 |
| Allotment Date | September 1, 2026 |
| Listing Date | September 3, 2026 |
| Listing | BSE & NSE |
| Registrar | Bigshare Services |
At the upper price of ₹82, one lot of 182 shares requires ₹14,924.
Lumino Industries IPO Subscription
Demand has strengthened sharply during the IPO.
By approximately 10:10 AM on August 31, the issue had received bids for around 40.48 crore shares against 6.32 crore shares available, taking overall subscription to 6.4x.
| Category | Subscription |
|---|---|
| QIB | Yet to fully build |
| NII | 12.53x |
| Retail | 7.59x |
| Overall | 6.40x |
The first day itself ended with approximately 1.38x subscription, driven by NII and retail demand, while QIB participation was initially limited.
The final subscription figure can rise further before the bidding window closes.
Lumino Industries IPO GMP Today
Grey-market sentiment remains very strong.
The latest available update reports a GMP of approximately ₹61 per share. At the ₹82 upper issue price, this implies an unofficial indicative price of around ₹143.
| GMP Indicator | Latest |
|---|---|
| Upper Issue Price | ₹82 |
| GMP | ~₹61 |
| Indicative Price | ~₹143 |
| Indicative Premium | ~74% |
| Sentiment | Strong |
The GMP has risen significantly from around ₹61 at the IPO's opening to higher levels during the issue period, with another report putting the final-day premium around 74%.
GMP is unofficial and can change before listing, so the indicated ₹143 price should not be considered a guaranteed listing price.
What Does Lumino Industries Do?
Lumino Industries operates in the power transmission and distribution infrastructure sector.
Its manufacturing portfolio includes:
conductors + power cables + electrical wires + HTLS conductors + specialised electrical products.
The company also undertakes EPC activities related to power infrastructure.
This creates two major business streams:
electrical-product manufacturing
and
power-infrastructure EPC execution.
The combination gives Lumino exposure to India's continuing investment in electricity transmission and distribution networks.
HTLS Conductors Provide a Specialised Product Opportunity
Lumino also manufactures High Temperature Low Sag (HTLS) conductors, which are designed to carry higher electrical loads while controlling sag at elevated temperatures.
The company has entered into a strategic collaboration with CTC Global Corporation for manufacturing, selling and distributing ACCC conductors.
These specialised products can help Lumino participate in transmission-capacity upgrades rather than relying only on conventional conductors.
FY2026 Revenue Crossed ₹2,000 Crore
Lumino Industries has shown strong financial growth over the past three years.
| Financial Metric | FY2024 | FY2025 | FY2026 |
|---|---|---|---|
| Revenue from Operations | ₹1,407.32 Cr | ₹1,917.97 Cr | ₹2,041.07 Cr |
| PAT | ₹86.61 Cr | ₹124.59 Cr | ₹159.99 Cr |
| Net Worth | ₹445.97 Cr | ₹570.45 Cr | ₹729.71 Cr |
| Total Assets | ₹1,175.44 Cr | ₹1,718.66 Cr | ₹2,174.88 Cr |
Lumino's FY2026 revenue reached approximately ₹2,041 crore, while PAT increased to nearly ₹160 crore.
Revenue growth slowed compared with the previous year, but profitability continued to improve.
Profitability Is a Key Positive
PAT increased from:
₹86.61 Cr → ₹124.59 Cr → ₹159.99 Cr
between FY2024 and FY2026.
The company therefore delivered substantial earnings growth even though FY2026 revenue growth was more moderate.
This makes margin sustainability an important factor for investors after listing.
Lumino Industries IPO Valuation
At the upper price band of ₹82, Lumino Industries is seeking a valuation of approximately ₹2,500 crore.
Based on FY2026 EPS of around ₹6.57, the upper-band valuation works out to roughly 12.5x earnings.
| Valuation Metric | Approx. |
|---|---|
| Upper Issue Price | ₹82 |
| FY2026 EPS | ₹6.57 |
| P/E | ~12.5x |
| Approx. Market Cap | ₹2,500 Cr |
The valuation therefore needs to be assessed alongside the company's order-book growth, debt position and future power-sector demand.
Order Book Reached ₹3,149.8 Crore
One of the most important indicators for Lumino is its order book.
As of March 2026, the company's order book stood at approximately ₹3,149.8 crore, up from ₹2,436.2 crore a year earlier.
| Period | Order Book |
|---|---|
| March 2025 | ₹2,436.2 Cr |
| March 2026 | ₹3,149.8 Cr |
| Growth | ~29% |
The order book is significantly larger than FY2026 revenue, providing a degree of future revenue visibility.
However, the actual benefit depends on project execution and timely customer payments.
₹337 Crore Will Be Used for Debt Repayment
The largest portion of the fresh issue is earmarked for reducing debt.
Lumino plans to use approximately ₹337 crore to prepay or repay certain outstanding borrowings.
| IPO Use | Amount |
|---|---|
| Debt Repayment / Prepayment | ₹337 Cr |
| Manufacturing Capex | ₹15.01 Cr |
| General Corporate Purposes | Balance |
| Fresh Issue | ₹500 Cr |
This means the IPO is primarily intended to strengthen the balance sheet rather than finance a very large greenfield expansion.
Why Debt Reduction Matters
Lumino has experienced increasing borrowing requirements as its operations and capacity have expanded.
Reducing debt with IPO proceeds could potentially lower finance costs.
The expected benefit is:
₹337 Cr debt reduction → lower interest burden → improved cash flow → stronger balance sheet.
However, investors should monitor whether the company takes on new debt again as it expands.
Working Capital Remains Important
Power-equipment manufacturing and EPC businesses generally require substantial working capital.
The cycle can involve:
raw-material procurement → manufacturing/project execution → invoicing → customer certification → payment collection.
If receivables remain outstanding for longer periods, the company may need additional working capital despite the IPO infusion.
This makes operating cash flow and receivable days important post-listing indicators.
Government Customers Remain Significant
Government and public-sector entities remain an important customer group for Lumino.
Government-related infrastructure projects can provide large opportunities as India invests in:
transmission networks + distribution infrastructure + renewable-energy evacuation + grid expansion.
At the same time, government tenders can involve long approval and payment cycles.
The company's ability to diversify its customer base therefore remains important.
Raw Materials Are a Major Cost
Raw materials represent a significant portion of Lumino's cost structure.
The company's electrical products are exposed to fluctuations in metals and other inputs.
The risk is straightforward:
higher raw-material prices → higher manufacturing costs → margin pressure.
The company may be able to pass some cost increases to customers through contractual mechanisms, but this cannot always completely eliminate margin volatility.
Anchor Investors Added Institutional Support
Ahead of the public issue, Lumino Industries raised approximately ₹206.99 crore from anchor investors.
Anchor participation provided institutional support before the IPO opened.
However, anchor participation should be viewed as one factor among many rather than an assurance of post-listing performance.
Key Strengths of Lumino Industries
The main positives include:
- Integrated manufacturing and EPC business
- Exposure to India's power-infrastructure expansion
- FY2026 revenue above ₹2,000 crore
- PAT of approximately ₹160 crore
- Order book of around ₹3,149.8 crore
- Specialised HTLS/ACCC conductor capabilities
- Large fresh-issue component
- ₹337 crore planned debt repayment
- Institutional anchor participation
- Strong IPO subscription
- Strong grey-market sentiment
The combination of order-book growth and debt reduction is particularly important for the company's post-IPO outlook.
Major Risks
Investors should also consider:
- High working-capital requirements
- Raw-material price volatility
- EPC project execution risks
- Government/customer concentration
- Receivable delays
- Debt-related financial costs
- Competition in cables and conductors
- Dependence on infrastructure spending
- Margin sustainability
- Customer concentration
Strong subscription and GMP do not remove these underlying business risks.
What Investors Should Track After Listing
| Metric | Why It Matters |
|---|---|
| Order Book | Future revenue visibility |
| Order Execution | Conversion into revenue |
| Revenue Growth | Business expansion |
| EBITDA Margin | Cost control |
| PAT Growth | Earnings sustainability |
| Borrowings | Deleveraging |
| Finance Cost | IPO debt-repayment benefit |
| Receivable Days | Collection efficiency |
| Operating Cash Flow | Earnings quality |
| Raw Material Costs | Margin protection |
| ROCE | Capital efficiency |
| New Orders | Future growth |
Final View on Lumino Industries IPO
The Lumino Industries IPO closes today, August 31, 2026, after attracting strong demand. The ₹700 crore mainboard issue has a price band of ₹78–₹82 and comprises ₹500 crore fresh issue and ₹200 crore OFS. Shares are expected to list on September 3 on BSE and NSE.
By around 10:10 AM on the final day, subscription had reached 6.4x, with NII at 12.53x and retail at 7.59x.
The latest GMP is around ₹61, suggesting an unofficial indicative listing price of approximately ₹143 and a premium of about 74% over the ₹82 upper issue price.
Fundamentally, Lumino reported ₹2,041.07 crore FY2026 revenue and ₹159.99 crore PAT, while its order book stood at approximately ₹3,149.8 crore.
Loading comments...