
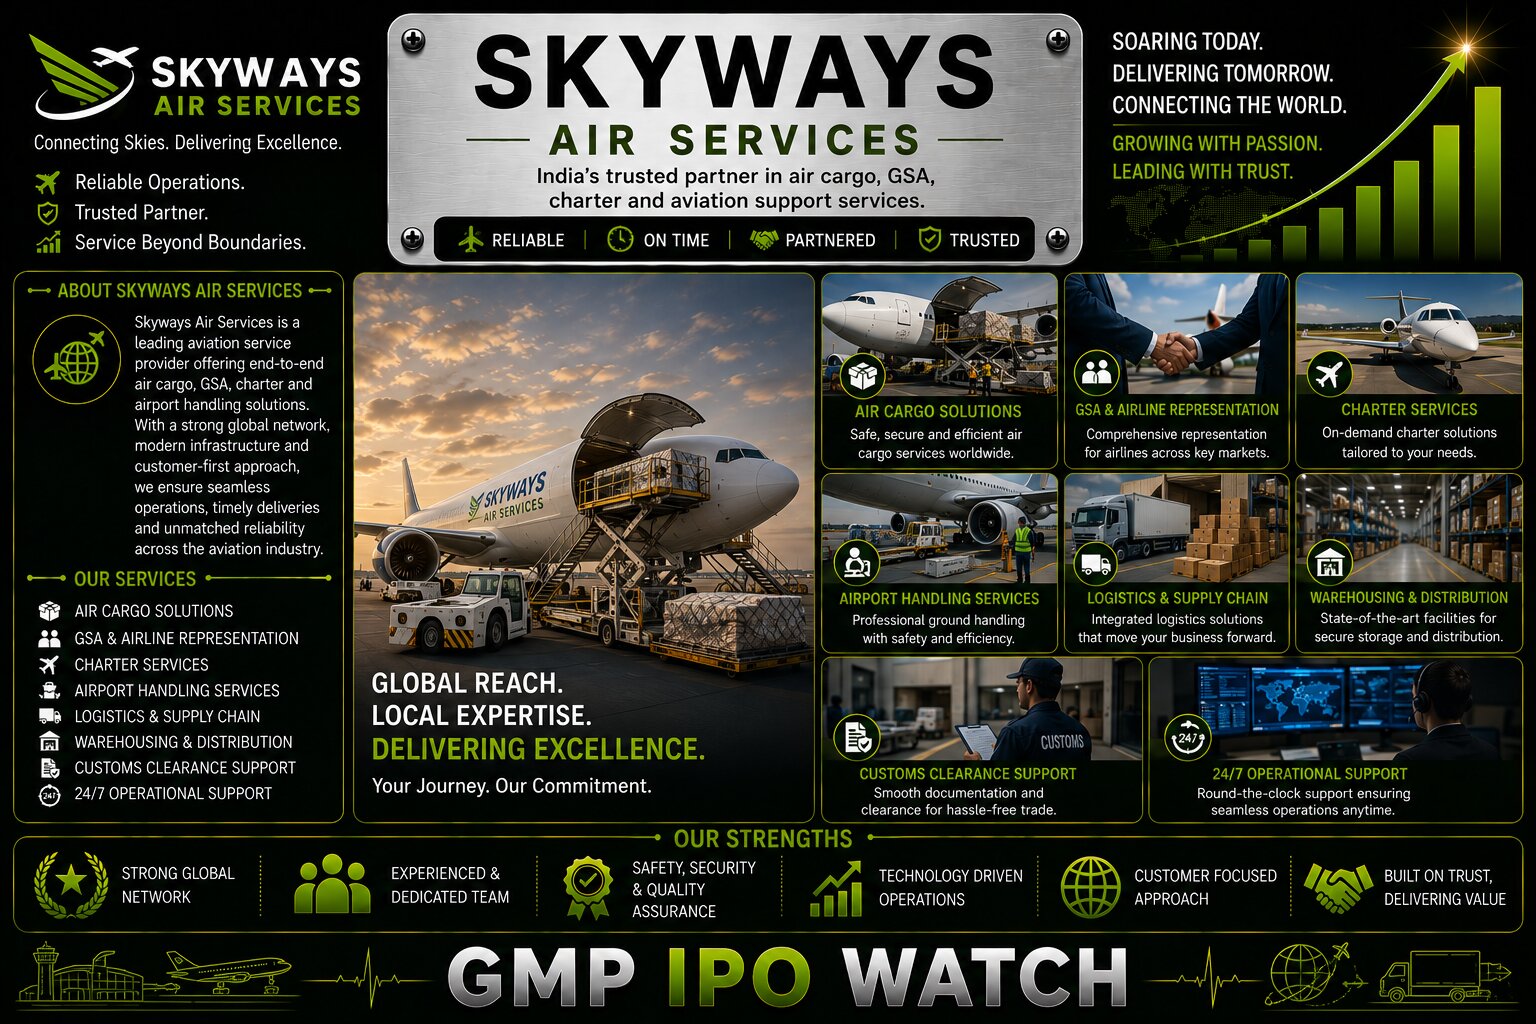
Skyways Air Services IPO 2026 – Logistics Player Enters Day 2
Skyways Air Services Limited's mainboard IPO entered its second bidding day today, August 25, 2026. The issue opened on August 24 and will close on August 27, with the shares scheduled to list on BSE and NSE on September 1.
The company has been operating since 1984 and has built an integrated logistics network covering air freight, ocean freight, road transportation, warehousing, customs clearance, express delivery and other value-added logistics services.
Skyways Air Services IPO Details
| Particular | Details |
|---|---|
| Company | Skyways Air Services Limited |
| IPO Type | Mainboard IPO |
| Issue Type | Book Built Issue |
| Total Issue Size | ₹582.80 Crore |
| Fresh Issue | ₹398.80 Crore |
| Offer for Sale | ₹184.00 Crore |
| Fresh Issue Shares | 2,88,98,300 |
| OFS Shares | 1,33,33,300 |
| Total Shares Offered | 4,22,31,600 |
| Price Band | ₹131 – ₹138 |
| Face Value | ₹10 |
| Lot Size | 100 Shares |
| Minimum Investment at ₹138 | ₹13,800 |
| IPO Open Date | August 24, 2026 |
| IPO Close Date | August 27, 2026 |
| Allotment | August 28, 2026 |
| Refund / Demat | August 31, 2026 |
| Expected Listing | September 1, 2026 |
| Listing Exchange | BSE & NSE |
The IPO comprises a ₹398.80 crore fresh issue along with an OFS of 1.33 crore shares worth approximately ₹184 crore at the upper price band.
Skyways Air Services IPO GMP Today
Grey-market sentiment remains positive on Day 2.
The latest reported trend indicates an unofficial potential listing premium of around 23.19% for Skyways Air Services.
| GMP Indicator | Latest Position |
|---|---|
| Upper Price Band | ₹138 |
| Indicative GMP | ~₹32 |
| Approx. Estimated Price | ~₹170 |
| Indicative Premium | ~23.2% |
| IPO Status | Day 2 – Open |
The GMP is unofficial and can change before listing, so it should not be considered a guaranteed return.
What Does Skyways Air Services Do?
Skyways Air Services is fundamentally an integrated logistics and supply-chain company, despite the word "Air" in its name.
Its service portfolio includes:
air freight + ocean freight + road transportation + warehousing + customs brokerage + express parcel delivery + value-added logistics services.
This allows customers to use Skyways for multiple stages of the logistics process rather than dealing with different providers for each part of a shipment.
Air Freight Is the Core Business
Air freight remains the most important part of Skyways' operations.
More than 75% of revenue is derived from air-freight services, making this segment the company's primary earnings driver.
The company's position in this market is noteworthy. Skyways has been ranked India's No. 1 Air Freight Forwarder by Air Waybill generation for four consecutive calendar years from 2022 through 2025, according to World ACD data cited in its IPO material.
| Business Area | Role |
|---|---|
| Air Freight | Core business |
| Ocean Freight | International cargo |
| Road Transport | Domestic movement |
| Warehousing | Storage & distribution |
| Customs Brokerage | Import/export clearance |
| Express Delivery | Time-sensitive shipments |
| Value-Added Services | Integrated logistics support |
FY2026 Revenue Crossed ₹2,800 Crore
Skyways has recorded strong revenue growth over the past three financial years.
| Financial Metric | FY2024 | FY2025 | FY2026 |
|---|---|---|---|
| Total Income | ₹1,316.81 Cr | ₹2,270.99 Cr | ₹2,839.67 Cr |
| EBITDA | ₹48.34 Cr | ₹86.49 Cr | ₹125.65 Cr |
| PAT | ₹34.49 Cr | ₹48.14 Cr | ₹63.52 Cr |
| Net Worth | ₹154.26 Cr | ₹247.14 Cr | ₹332.64 Cr |
| Borrowings | ₹357.34 Cr | ₹558.43 Cr | ₹624.06 Cr |
Skyways' total income increased from ₹1,316.81 crore in FY2024 to ₹2,839.67 crore in FY2026, while PAT increased from ₹34.49 crore to ₹63.52 crore.
FY2026 PAT Increased Around 32%
The latest year also delivered healthy earnings growth.
PAT increased from ₹48.14 crore in FY2025 to ₹63.52 crore in FY2026, representing growth of approximately 32%.
EBITDA also increased significantly:
₹48.34 crore → ₹86.49 crore → ₹125.65 crore
over FY2024–FY2026.
This indicates that the company has expanded operating earnings alongside revenue.
Borrowings Have Increased Alongside Growth
One financial metric requires particular attention: debt.
Skyways' reported borrowings increased from:
₹357.34 crore in FY2024 → ₹558.43 crore in FY2025 → ₹624.06 crore in FY2026.
The increase reflects the capital and working-capital requirements of a rapidly growing logistics operation.
This also explains why debt repayment is the largest specified use of fresh IPO proceeds.
₹216.78 Crore Planned for Debt Repayment
Skyways plans to allocate approximately ₹216.78 crore toward repayment or prepayment of borrowings of the company and its subsidiary, Forin Container Line Private Limited.
Use of Fresh IPO Proceeds
| Purpose | Amount |
|---|---|
| Debt Repayment / Prepayment | ₹216.78 Cr |
| Working Capital | ₹130.00 Cr |
| General Corporate Purposes | Balance |
| Fresh Issue | ₹398.80 Cr |
Debt repayment represents the largest identified IPO objective.
If implemented successfully, the financial progression could be:
IPO capital → lower borrowings → lower finance costs → stronger cash flow → improved balance sheet.
₹130 Crore Will Support Working Capital
The company also plans to use ₹130 crore for incremental working-capital requirements.
Working capital is especially important in freight forwarding.
Skyways may need to pay airlines, shipping lines, transport operators and other logistics partners before it receives payment from customers.
That creates a cycle such as:
book freight capacity → move shipment → invoice customer → wait for collection → recycle cash.
As shipment volumes grow, the amount of capital tied up in this cycle can also increase.
Fresh Issue Is Larger Than the OFS
The IPO structure is relatively favourable from a capital-raising perspective because fresh shares represent the larger portion of the issue.
| IPO Component | Amount | Approx. Share |
|---|---|---|
| Fresh Issue | ₹398.80 Cr | 68.4% |
| Offer for Sale | ₹184.00 Cr | 31.6% |
| Total Issue | ₹582.80 Cr | 100% |
Around two-thirds of the IPO therefore represents fresh capital going into the company.
The OFS portion, by comparison, represents shares being sold by existing shareholders.
Promoters Will Retain Majority Control
The promoter group's stake is expected to decline after the IPO from approximately 79.1% to 56.8%.
| Shareholding | Approx. Stake |
|---|---|
| Promoter Group – Pre IPO | 79.1% |
| Promoter Group – Post IPO | 56.8% |
Despite the dilution, promoters are expected to retain majority ownership following the public issue.
Anchor Investors Put in ₹174.5 Crore
Ahead of public bidding, Skyways raised approximately ₹174.5 crore from anchor investors.
Reported participants included institutional investors such as Citi and Nomura.
This provided institutional participation before the IPO opened to other investor categories.
Air Freight Provides Speed Advantage
Air cargo is typically more expensive than sea freight, but it provides one major advantage: speed.
This makes it important for shipments such as:
electronics + pharmaceuticals + automotive components + fashion + perishables + high-value goods + urgent industrial components.
Companies are often willing to pay more for air freight when shipment timing matters more than transportation cost.
Skyways' long operating history and scale in this segment give it exposure to this specialised logistics demand.
Ocean Freight Adds Diversification
Skyways is not completely dependent on air cargo.
Its ocean-freight operations allow the company to serve customers whose shipments are larger, heavier or less time-sensitive.
This creates two different logistics propositions:
Air freight → faster + higher cost
Ocean freight → slower + lower cost for bulk cargo
Having both capabilities allows Skyways to provide customers with different transportation options based on urgency, shipment size and budget.
International Trade Is Both an Opportunity and a Risk
Skyways benefits when India's cross-border trade expands.
More exports and imports can create additional demand for:
freight forwarding + customs clearance + warehousing + transportation + supply-chain management.
But this creates an important risk as well.
Because Skyways is heavily exposed to cross-border freight, global economic slowdowns, trade restrictions, tariffs, geopolitical disruptions and currency volatility can affect shipment volumes.
Acquisitions Have Expanded the Platform
Skyways has also used acquisitions to strengthen its logistics platform.
During FY2024-25, the company acquired interests in C T C Air Carriers Private Limited and Odyssey Logistics Private Limited, according to its annual-report disclosures.
Acquisitions can help a logistics company quickly add:
customers + routes + infrastructure + capabilities + geographic reach.
However, they also introduce integration and capital-allocation risks.
Investors should therefore monitor how acquired businesses contribute to consolidated revenue and profitability.
Margins Remain Relatively Thin
Despite generating more than ₹2,800 crore of annual income, Skyways earned PAT of ₹63.52 crore in FY2026.
This is typical of many freight-forwarding businesses where shipment values and pass-through transportation costs can create large revenue numbers while net margins remain comparatively small.
Sushil Finance's IPO analysis notes that PAT margins have remained around 2.1–2.6%, even as EBITDA margins improved.
For Skyways, investors should therefore look beyond headline revenue and focus on:
EBITDA margin + PAT margin + operating cash flow + return ratios.
Debt Reduction Could Be More Important Than Revenue Growth
Given FY2026 borrowings of approximately ₹624 crore, the planned ₹216.78 crore debt repayment could materially alter the balance sheet.
The next few financial results should therefore reveal whether the IPO produces the intended benefit.
Investors should watch:
total borrowings → finance costs → PAT margin → operating cash flow.
If debt falls significantly while operating growth continues, the quality of future earnings could improve.
Key Strengths of Skyways Air Services
Skyways enters the IPO with an established operating history dating back to 1984, leadership in India's air-freight forwarding market by AWB generation, a broader integrated logistics platform and strong recent revenue growth.
Total income more than doubled between FY2024 and FY2026, reaching ₹2,839.67 crore, while PAT increased to ₹63.52 crore.
Another positive is the IPO structure: ₹398.80 crore of the ₹582.80 crore issue is fresh capital, with ₹216.78 crore earmarked for debt repayment and ₹130 crore for working capital.
Major Risks
The biggest areas to watch include high dependence on air freight, exposure to global trade conditions, relatively thin profit margins, large working-capital requirements and elevated borrowings.
More than 75% of revenue comes from air freight, meaning disruption in international cargo markets can materially affect the business.
Other risks include airline freight-rate volatility, foreign-exchange movements, customer concentration, competition from global logistics companies and integration of acquired businesses.
What Investors Should Track After Listing
| Metric | Why It Matters |
|---|---|
| Air Freight Volumes | Core business demand |
| Total Income Growth | Business expansion |
| EBITDA Margin | Operating efficiency |
| PAT Margin | Earnings quality |
| Air Freight Revenue Share | Business concentration |
| International Cargo Volumes | Trade exposure |
| Borrowings | IPO deleveraging |
| Finance Cost | Debt repayment benefit |
| Working Capital | Funding efficiency |
| Receivable Days | Cash collection |
| Operating Cash Flow | Profit-to-cash conversion |
| ROCE | Capital efficiency |
For Skyways, debt reduction and operating cash flow could become just as important as shipment and revenue growth after listing.
Final View on Skyways Air Services IPO
The Skyways Air Services IPO is on Day 2 today, August 25, 2026, and will close on August 27. The ₹582.80 crore mainboard IPO is priced at ₹131–₹138 per share, with shares expected to list on BSE and NSE on September 1.
The latest grey-market indication suggests approximately 23.19% potential premium, showing positive sentiment around the issue, although GMP remains unofficial and can change before listing.
Fundamentally, Skyways has delivered strong recent growth. Total income increased from ₹1,316.81 crore in FY2024 to ₹2,839.67 crore in FY2026, while PAT increased from ₹34.49 crore to ₹63.52 crore. At the same time, borrowings rose to ₹624.06 crore.
This makes IPO fund utilisation particularly important. Approximately ₹216.78 crore is planned for debt repayment and ₹130 crore for working capital.
Loading comments...