Manika Plastech IPO 2026 Overview
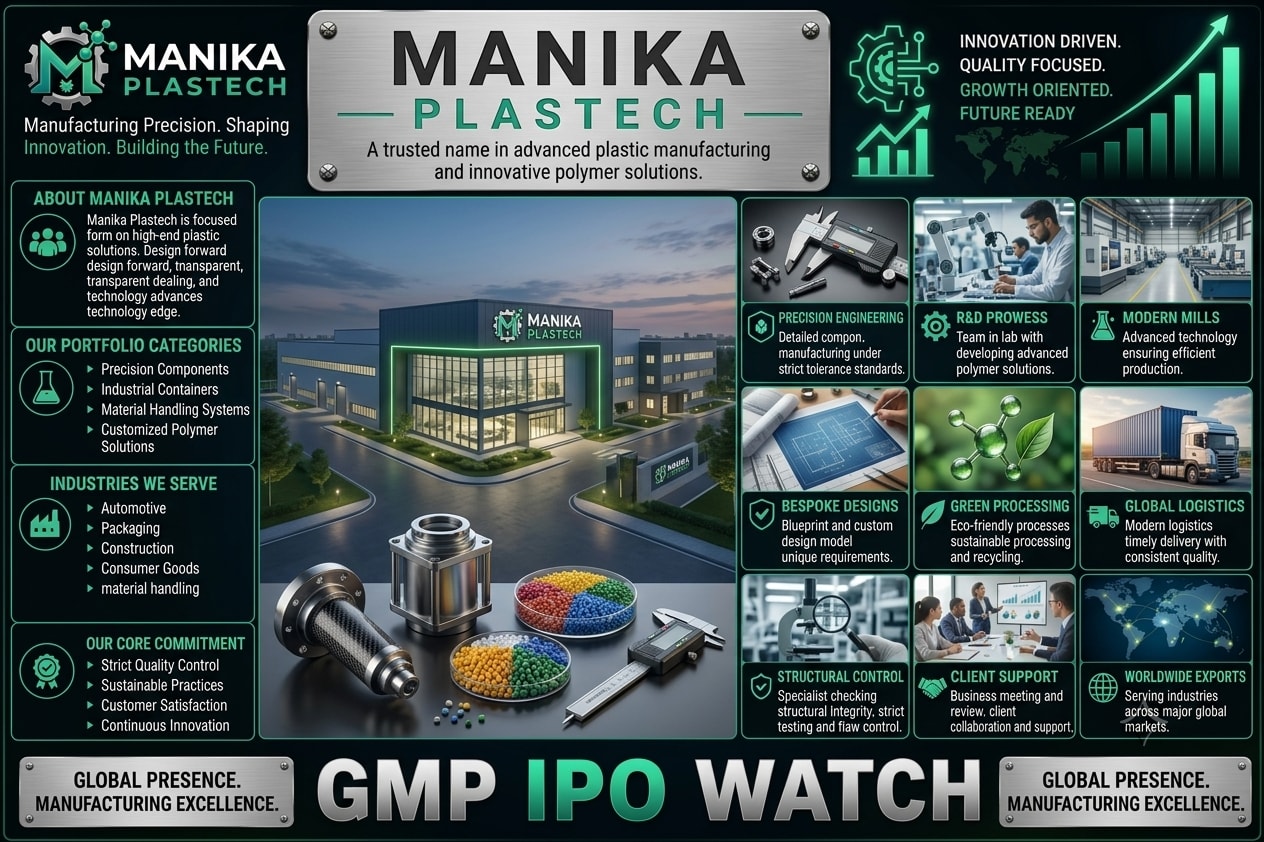
Manika Plastech Limited is a manufacturer of rigid polymer packaging products serving industries such as automotive, energy storage, paints, lubricants, agrochemicals, construction chemicals, food and dairy.
The company provides an end-to-end packaging solution covering product design and development, raw-material sourcing, manufacturing, labelling, quality assurance and delivery. Its portfolio includes battery casings, heavy-duty pails, thin-wall containers and other customised polymer products. The company operates six manufacturing facilities and one painting facility across locations including Dehradun, Hosur, Panipat, Una and Dadra.
The IPO opened on September 11, 2026 and will close on September 16, 2026. The shares are proposed to be listed on both BSE and NSE on September 21, 2026.
| Particular | Details |
|---|---|
| IPO Name | Manika Plastech IPO |
| IPO Date | 11–16 Sep 2026 |
| Allotment | 17 Sep 2026 |
| Refund | 18 Sep 2026 |
| Demat Credit | 18 Sep 2026 |
| Listing Date | 21 Sep 2026 |
| IPO Type | Book Built Issue |
| IPO Size | ₹125.50 Cr |
| Price Band | ₹40–₹43 |
| Lot Size | 348 Shares |
| Min. Investment | ₹14,964 |
| Fresh Issue | ₹92.50 Cr |
| OFS | ₹33.00 Cr |
| Listing | BSE & NSE |
| Lead Manager | Pantomath Capital |
| Registrar | MUFG Intime India |
Manika Plastech IPO GMP Today
The latest available grey-market data for September 14, 2026 shows Manika Plastech IPO GMP at around ₹11 per share. At the upper price band of ₹43, this indicates an estimated listing price of approximately ₹54 and an indicative premium of about 25.58%.
Other IPO trackers have reported GMP levels between ₹9 and ₹11, while earlier quotes were higher. This shows that the grey-market premium has been volatile during the IPO period.
| Particular | Details |
|---|---|
| IPO Price | ₹43 |
| Latest GMP | ~₹11 |
| Estimated Listing | ~₹54 |
| Indicative Gain | ~₹11 |
| GMP Return | ~25.58% |
| GMP Status | Positive |
GMP is an unofficial and unregulated indicator. The actual listing price can be materially different from the GMP-based estimate.
Manika Plastech IPO Important Dates
The IPO bidding period runs from September 11 to September 16. The basis of allotment is expected on September 17, followed by refunds and demat credit on September 18. The shares are scheduled to begin trading on September 21.
| Event | Date |
|---|---|
| IPO Opens | 11 Sep 2026 |
| IPO Closes | 16 Sep 2026 |
| Allotment | 17 Sep 2026 |
| Refund | 18 Sep 2026 |
| Demat Credit | 18 Sep 2026 |
| Listing | 21 Sep 2026 |
Manika Plastech IPO Lot Size and Investment
The price band is ₹40–₹43 and the minimum bid is 348 shares. At the upper price band, one lot requires ₹14,964, which keeps the minimum retail application within the usual ₹15,000 IPO application range.
Retail investors can apply for up to 13 lots, or 4,524 shares, requiring ₹1,94,532 at the upper price band.
| Particular | Details |
|---|---|
| Lot Size | 348 Shares |
| Upper Price | ₹43 |
| 1 Lot Value | ₹14,964 |
| Retail Minimum | 348 Shares |
| Retail Maximum | 4,524 Shares |
| Retail Maximum Lots | 13 |
Manika Plastech IPO Issue Structure
The ₹125.50 crore IPO consists of a ₹92.50 crore fresh issue and a ₹33 crore offer for sale. The fresh issue consists of approximately 2.15 crore shares, while the OFS comprises approximately 76.74 lakh shares.
The fresh issue proceeds will be available to Manika Plastech for its stated expansion and financial objectives. The OFS proceeds will go to the selling shareholder rather than the company.
| Particular | Details |
|---|---|
| Total Issue | ₹125.50 Cr |
| Fresh Issue | ₹92.50 Cr |
| OFS | ₹33.00 Cr |
| Face Value | ₹2 |
| Issue Type | Book Built |
| Exchange | BSE & NSE |
Manika Plastech Company Business
Manika Plastech has been involved in rigid polymer packaging since its incorporation in 1996. Its products are designed for applications where durability, dimensional accuracy and customised packaging are important.
The company's major product categories include battery casings, pails and thin-wall containers. Battery casings are used in energy-storage applications, while pails and containers serve industries including paints, lubricants, chemicals, food and dairy.
The company also provides painting and other value-added services, giving it an integrated product offering rather than operating only as a basic plastic-moulding manufacturer.
As of July 31, 2026, the company had 352 employees and 809 contract labourers. Its customer base spans several industrial sectors, reducing dependence on a single end market, although customer concentration remains an important factor to monitor.
Manika Plastech Manufacturing Network
Manika Plastech operates seven facilities, comprising six manufacturing facilities and one painting facility. Manufacturing operations are spread across Dehradun, Hosur, Panipat, Una and Dadra, while the painting facility is located in Hosur.
This geographical spread allows the company to serve customers across different industrial regions and provides manufacturing capacity for multiple product categories.
The company's integrated approach includes design, development, sourcing, moulding, heat sealing, labelling, quality control and delivery. This can help improve customer stickiness when clients require customised packaging solutions rather than standard off-the-shelf products.
Manika Plastech IPO Financial Performance
Manika Plastech has recorded consistent improvement in revenue and profitability over the last three financial years.
Total income increased from ₹368.76 crore in FY2024 to ₹412.59 crore in FY2025 and ₹437.26 crore in FY2026. PAT increased from ₹11.53 crore in FY2024 to ₹19.33 crore in FY2025 and further to ₹22.40 crore in FY2026.
| Financial Year | Total Income | EBITDA | PAT |
|---|---|---|---|
| FY2024 | ₹368.76 Cr | ₹30.86 Cr | ₹11.53 Cr |
| FY2025 | ₹412.59 Cr | ₹45.30 Cr | ₹19.33 Cr |
| FY2026 | ₹437.26 Cr | ₹58.14 Cr | ₹22.40 Cr |
Revenue growth has been moderate, but profitability has grown faster. PAT increased by approximately 16% in FY2026 compared with FY2025.
Manika Plastech IPO Q1 FY2027 Performance
The company reported a strong first quarter of FY2027. For the three months ended June 30, 2026, total income was approximately ₹162.71 crore, EBITDA was ₹24.38 crore and PAT reached ₹13.07 crore.
| Period | Total Income | EBITDA | PAT |
|---|---|---|---|
| Q1 FY2027 | ₹162.71 Cr | ₹24.38 Cr | ₹13.07 Cr |
| FY2026 | ₹437.26 Cr | ₹58.14 Cr | ₹22.40 Cr |
The Q1 PAT is unusually high compared with the full-year FY2026 number, so investors should be cautious about simply annualising the first-quarter performance. IPO Watch also highlighted the unusually strong Q1 earnings and rising trade receivables as areas worth monitoring.
Manika Plastech IPO Financial Ratios
For FY2026, Manika Plastech reported ROE/RoNW of around 15.18%, ROCE of 18.77%, EBITDA margin of 13.34% and PAT margin of 5.12%. Debt-to-equity stood at approximately 0.60x.
| Ratio | FY2026 |
|---|---|
| EPS | ₹2.36 |
| RoNW | 15.18% |
| ROCE | 18.77% |
| EBITDA Margin | 13.34% |
| PAT Margin | 5.12% |
| Debt/Equity | 0.60x |
| NAV | ₹15.54 |
The company's operating cash flow has remained positive. Net cash generated from operating activities was ₹44.30 crore in FY2026, compared with ₹36.88 crore in FY2025 and ₹35.42 crore in FY2024.
Manika Plastech IPO Objects of the Issue
The fresh issue proceeds are primarily intended for capital expenditure and debt reduction.
The company plans to invest in plant and machinery, including injection moulding machines, injection blow-moulding machines, injection stretch blow-moulding machines, moulds, IML robots and auxiliary equipment. The stated purpose is to increase manufacturing capabilities, expand product offerings and increase capacity.
A portion of the proceeds will also be used for repayment or prepayment of existing borrowings, which can reduce interest costs and strengthen the balance sheet.
| Use of Funds | Purpose |
|---|---|
| Plant & Machinery | Capacity expansion |
| Moulding Equipment | Product capability |
| Existing Borrowings | Debt reduction |
| General Corporate Purpose | Business requirements |
Manika Plastech IPO Subscription Status
Manika Plastech IPO received a positive initial response. The latest available tracker shows overall subscription of approximately 1.49x, with retail demand around 2.24x and NII demand around 2.55x. QIB participation was lower at around 0.36x in the Day 1 data.
| Category | Latest Available |
|---|---|
| QIB | ~0.36x |
| NII | ~2.55x |
| Retail | ~2.24x |
| Overall | ~1.49x |
Subscription figures can change materially during the remaining bidding period, so the final exchange-reported numbers should be checked after the issue closes.
Manika Plastech IPO Strengths
Manika Plastech operates in a specialised rigid-polymer packaging segment with customers across several industries. Battery casings are particularly important, with battery products contributing a significant portion of FY2026 revenue.
The company also has an established manufacturing footprint and a broad product portfolio, which can help it serve different customer requirements.
Key strengths include:
- Established rigid polymer packaging manufacturer
- Operating since 1996
- Six manufacturing facilities and one painting facility
- Battery casing, pail and thin-wall packaging portfolio
- Exposure to energy-storage applications
- Diversified industrial customer base
- Integrated design-to-delivery capabilities
- Revenue and PAT growth over FY2024–FY2026
- Positive operating cash flow
- Planned capacity expansion
- IPO proceeds partly earmarked for debt reduction
- Positive initial IPO subscription response
Manika Plastech IPO Risks
The company operates in a competitive plastics and packaging industry where raw-material prices can materially affect margins. Polymer prices and other input costs can fluctuate, while customers may resist immediate price increases.
Another consideration is the company's debt position. Total borrowings were approximately ₹88.19 crore at March 2026, with a debt-to-equity ratio of about 0.60x. The IPO's debt-repayment component should help, but leverage remains relevant to the investment case.
The company's customer base also spans multiple industries, but demand remains linked to industrial production, automotive activity, energy-storage growth and consumer-product demand.
Other risks include:
- Raw-material price volatility
- Competition in rigid plastic packaging
- Customer concentration
- Dependence on industrial demand
- Working-capital requirements
- Existing borrowings
- Execution risk in capacity expansion
- Environmental and regulatory requirements for plastics
- Volatility in margins
- Q1 FY2027 earnings may not be sustainable at the same rate
Manika Plastech IPO Valuation
At the upper price band of ₹43, FY2026 diluted EPS is reported at approximately ₹2.36. On this basis, the simple FY2026 earnings multiple is around 18.2x.
The company reported FY2026 NAV of ₹15.54, putting the price-to-book value at roughly 2.77x at the upper band.
The disclosed listed peers include Hitech Corporation, Mold-Tek Packaging and Shaily Engineering Plastics. Their business scale, product mix and profitability differ from Manika Plastech, so peer P/E comparison should be treated as a reference rather than a direct valuation conclusion.
IPO Watch's analysis described the issue as fully priced when considering the company's recent average earnings, despite the attractive valuation based on FY2026 earnings alone.
Manika Plastech IPO GMP Trend
The GMP has moved considerably during the pre-listing period. InvestorGain reported ₹17 on September 8, falling to ₹13 on September 9 and 10, then moving to ₹7 on September 11, ₹15 on September 12 and ₹11 on September 13–14.
| Date | GMP |
|---|---|
| 8 Sep 2026 | ₹17 |
| 9 Sep 2026 | ₹13 |
| 10 Sep 2026 | ₹13 |
| 11 Sep 2026 | ₹7 |
| 12 Sep 2026 | ₹15 |
| 13 Sep 2026 | ₹11 |
| 14 Sep 2026 | ₹11 |
The recent GMP indicates positive but volatile grey-market sentiment. It should not be treated as a guaranteed listing-gain indicator.
Manika Plastech IPO Review
Manika Plastech IPO Review: Positive with Valuation and Execution Caution
Manika Plastech has a reasonably established business in rigid polymer packaging, with applications spanning automotive, energy storage, paints, lubricants, agrochemicals, construction chemicals, food and dairy. Its seven-facility manufacturing network and integrated product-development capabilities provide a solid operating base.
Financially, the company has shown consistent improvement. Total income increased from ₹368.76 crore in FY2024 to ₹437.26 crore in FY2026, while PAT nearly doubled from ₹11.53 crore to ₹22.40 crore. Operating cash flow has also remained positive.
The IPO has two clear uses that could support the business: investment in new machinery and repayment of existing borrowings. The current GMP of around ₹11 also indicates positive unofficial sentiment, while initial subscription demand was encouraging.
The main caution is valuation. At ₹43, the stock is valued at roughly 18x FY2026 earnings, while FY2026 ROCE and RoNW are respectable rather than exceptional. The unusually strong Q1 FY2027 profit also needs to be monitored before assuming the same profitability will continue for the full year.
Overall, Manika Plastech IPO looks fundamentally positive, with a diversified packaging business, improving profits, positive cash generation and capacity-expansion plans. However, investors should consider the valuation, debt, raw-material risks and sustainability of the recent earnings acceleration before investing.
Manika Plastech IPO Key Highlights
- ₹125.50 crore mainboard IPO
- IPO opens September 11 and closes September 16, 2026
- Price band ₹40–₹43
- Lot size 348 shares
- Minimum investment ₹14,964
- Fresh issue ₹92.50 crore
- OFS ₹33 crore
- Listing expected September 21, 2026
- Listing on BSE and NSE
- FY2026 total income ₹437.26 crore
- FY2026 PAT ₹22.40 crore
- FY2026 EBITDA ₹58.14 crore
- FY2026 RoNW 15.18%
- FY2026 ROCE 18.77%
- FY2026 debt/equity 0.60x
- FY2026 operating cash flow ₹44.30 crore
- Q1 FY2027 PAT ₹13.07 crore
- Latest GMP around ₹11
- Indicative GMP-based listing around ₹54
- Latest available subscription around 1.49x
- Fresh proceeds to fund machinery and debt reduction
Manika Plastech IPO Conclusion
Manika Plastech IPO gives investors exposure to a diversified rigid polymer packaging manufacturer with applications across automotive, energy storage, chemicals, food and other industrial segments. The company has an established operating history, multiple manufacturing facilities and an integrated packaging solution.
The financial trend is encouraging, with total income increasing from ₹368.76 crore in FY2024 to ₹437.26 crore in FY2026 and PAT rising from ₹11.53 crore to ₹22.40 crore. Positive operating cash flow and planned capital expenditure are additional positives.
At the same time, investors should not overlook valuation, raw-material sensitivity, debt and the sustainability of the unusually strong Q1 FY2027 earnings. The GMP is positive but volatile and should not be used as the sole basis for an investment decision.
Manika Plastech IPO appears fundamentally positive for investors seeking exposure to industrial packaging, but valuation and earnings-sustainability risks should be considered carefully.
Disclaimer: Grey Market Premium (GMP) is an unofficial and unregulated indicator and does not guarantee the actual listing price. Subscription figures and GMP can change until the IPO closes. This article is for informational purposes only and is not investment advice.
Loading comments...